An Arkansas corporation that expects its income tax for the year to be more than $1,000 has to declare and pay estimated tax in four quarterly installments. AR1100ESCT is the set of vouchers for that, and DFA publishes a new set for each tax year. The 2026 set comes with instructions revised June 27, 2025.
Due dates for the four vouchers
Each of the four vouchers carries one quarter of the year’s estimate. Voucher 1 is due on the 15th day of the 4th month of the tax year, voucher 2 on the 15th day of the 6th month, voucher 3 on the 15th day of the 9th month and voucher 4 on the 15th day of the 12th month.
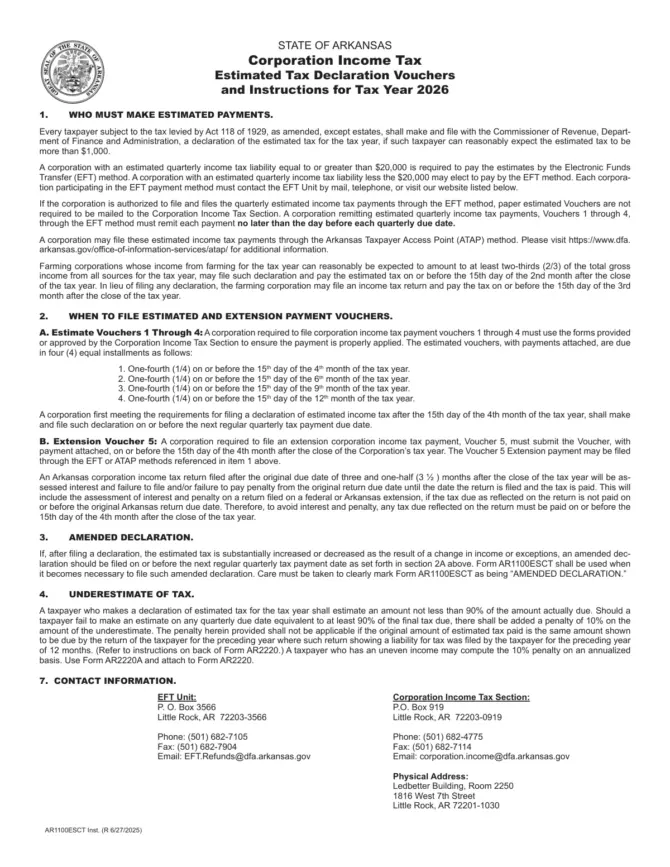
For a calendar year: April 15, June 15, September 15, December 15. A corporation that only meets the $1,000 test after the first due date starts with the next quarterly date. Estates are excluded. Farming corporations have their own rule.
Voucher 5 is the extension payment
The set also includes Voucher 5, for tax paid with an extension, due on the 15th day of the 4th month after the tax year ends. The instructions explain why that date matters even for a corporation on extension. The return is due three and a half months after the year end. Interest and penalties run from that original date on any tax not paid by then, whether or not a federal or Arkansas extension was granted.
Paying electronically
A corporation with an estimated quarterly liability of $20,000 or more must pay by electronic funds transfer (EFT); smaller ones may choose to. EFT payers do not mail paper vouchers, but each EFT payment must be made no later than the day before the quarterly due date. Payments can also be made through ATAP, the Arkansas Taxpayer Access Point.
The 90% rule and the 10% penalty
The estimate must be at least 90% of the tax actually due. Fall short on any quarterly date and a penalty of 10% of the underestimate is added. No penalty applies if the estimates paid match the tax shown on the previous year’s 12-month return, where that return showed a liability. The calculation is on Form AR2220, and a corporation with uneven income can annualize it on Form AR2220A.
Changing the estimate mid-year
If income changes substantially, file an amended declaration on an AR1100ESCT by the next quarterly date, clearly marked “AMENDED DECLARATION”. Page 2 has an amended computation: the new estimated tax, less what has been paid, divided by the installments left.
Page 2 also has an estimated tax worksheet (expected taxable income, estimated tax, number of installments, amount of each) and a record of payments to keep with your files.
Farming corporations
A corporation that expects at least two-thirds of its gross income from farming can file its declaration and pay the estimate by the 15th day of the 2nd month after the year ends. It can also skip the declaration and file the return and pay by the 15th day of the 3rd month.
Addresses
Corporation Income Tax Section, P.O. Box 919, Little Rock, AR 72203-0919, phone (501) 682-4775, corporation.income@dfa.arkansas.gov. The EFT Unit is at P.O. Box 3566, Little Rock, AR 72203-3566, phone (501) 682-7105.
Official PDF: Form AR1100ESCT — Official PDF (dfa.arkansas.gov)
Official sources
- Arkansas Department of Finance and Administration, AR1100ESCT Corporation Income Tax Estimated Tax Declaration Vouchers and Instructions for Tax Year 2026, Inst. R 6/27/2025 (dfa.arkansas.gov)