When a Nebraska taxpayer dies with a state refund still owed to them, the Department of Revenue will not simply send the money to whoever files the final return. Form 1310N is the short statement that says who you are in relation to the person who died and why the refund should be paid to you.
It is one page, form number 8-226-1972, revision 10-2023, with the instructions printed on the back. Most of the work is choosing the right box in Part I. The rest is quick.
Two cases where you do not file it
The instructions name two situations that need no Form 1310N:
- You are the surviving spouse and you are filing an original or amended joint return with the person who died. If you file on paper, write “surviving spouse” on the signature block of Form 1040N or 1040XN instead.
- You are the personal representative, you are filing an original Form 1040N for the deceased person, and the court certificate showing your appointment is attached to that return.
Everyone else files it. That includes a personal representative who is filing an amended return (1040XN).
Part I: which box is yours
Check one box only. The three boxes cover very different people:
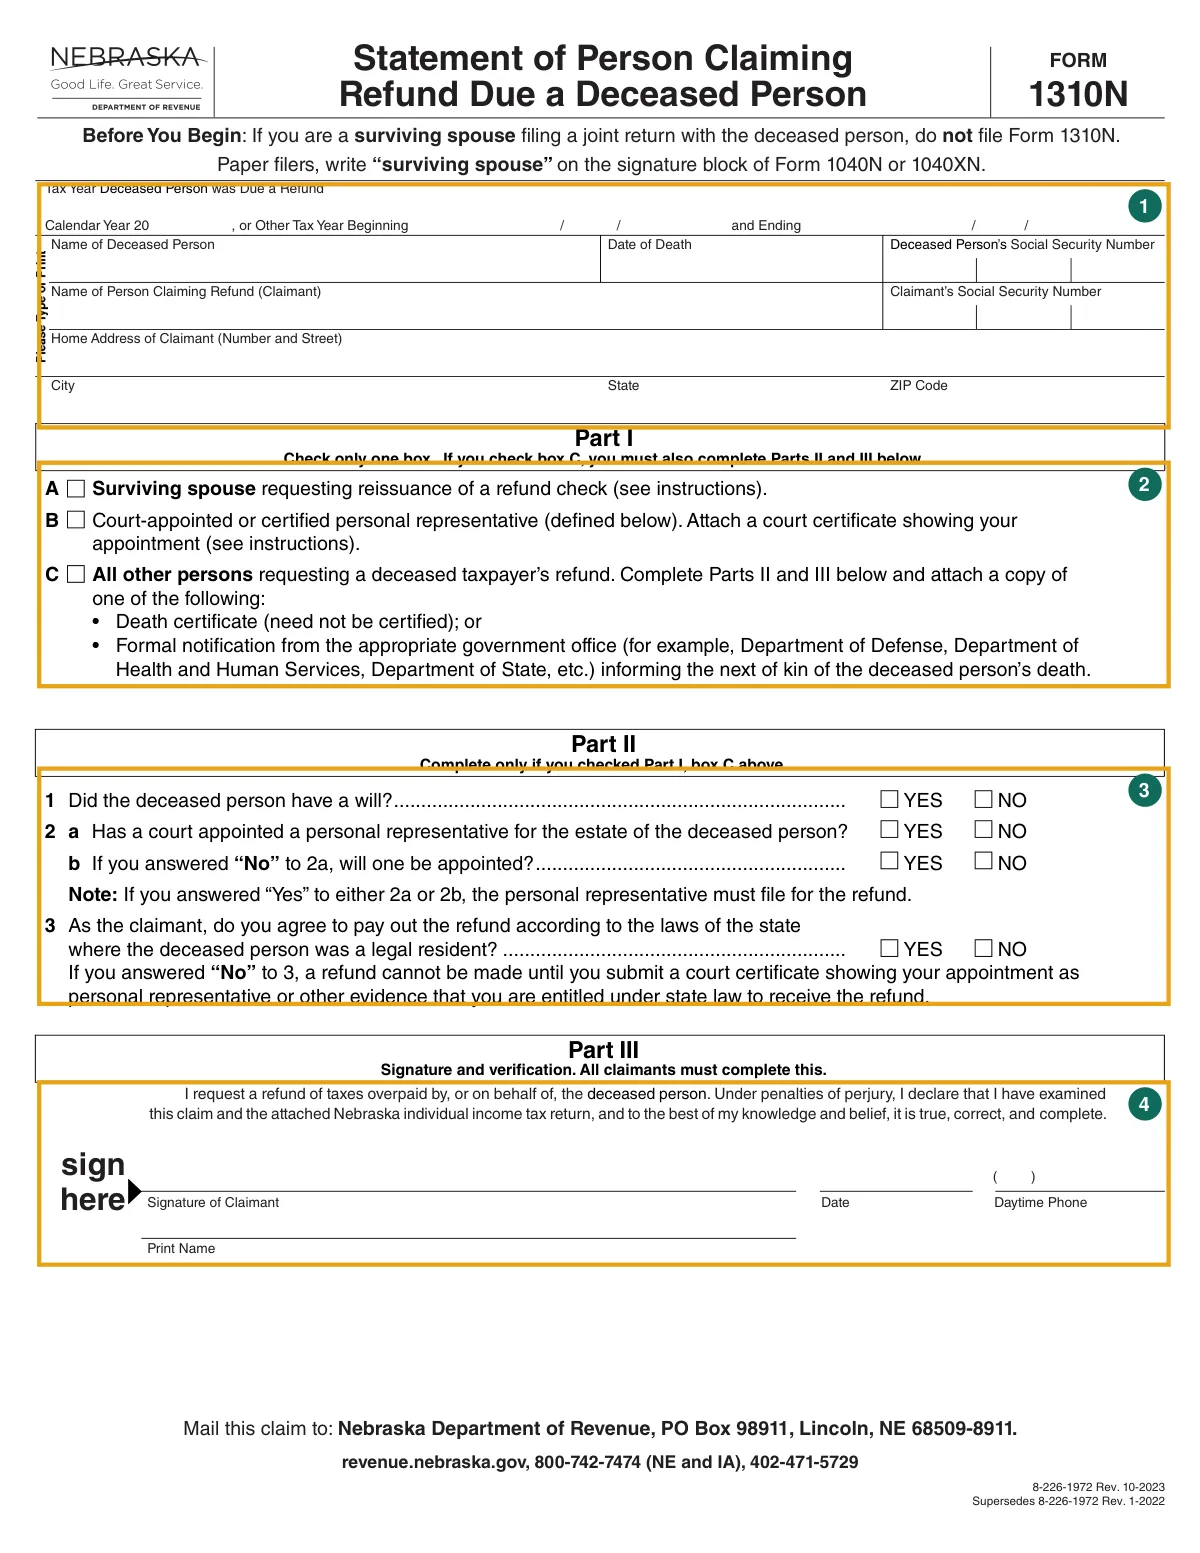
| Box | Who checks it | What goes with the form |
|---|---|---|
| A | A surviving spouse who received a refund check made out to both spouses and needs it reissued | The joint-name check itself. The department sends a new check in your name only. |
| B | The executor or administrator appointed or certified by a court, claiming the refund on Form 1040N or 1040XN | A copy of the court certificate showing the appointment, attached to the return |
| C | Anyone else in charge of the deceased person’s affairs, when there is no court-appointed representative and no joint return | Proof of death, plus Parts II and III completed |
Box B is the one people get wrong. “Personal representative” on this form means someone a court has appointed or certified. Being named as executor in a will is not enough: the instructions say a copy of the will cannot be accepted as evidence of the role.
Proof of death for box C
Either a copy of the death certificate, which does not have to be a certified copy, or the formal notice of death that a government office sent to the next of kin (the instructions give the Department of Defense, the Department of Health and Human Services and the Department of State as examples). If proof of death has already been sent to the department, write “Proof of Death Previously Filed” at the bottom of the form.
Part II, only after box C
Three questions, each answered yes or no:
Line 1
Did the person who died have a will?
Line 2a and 2b
Has a court appointed a personal representative for the estate, and if not, will one be appointed? A yes to either one ends the box C claim. The personal representative files instead.
Line 3
Do you agree to pay the refund out according to the laws of the state where the deceased person was a legal resident? Answer no and nothing is paid yet. The refund waits until you send a court certificate showing your appointment, or other evidence that state law entitles you to the money.
The rest of the form
The header asks for the tax year the refund belongs to. That is the year of the return showing the overpayment, which is often not the year of death. Someone who died in March 2026 may be owed a refund for tax year 2025, and a second one for 2026 if tax was withheld from pay or pension before the death. For a fiscal-year filer there is space for the start and end dates instead of a calendar year.
Below it go the deceased person’s name, date of death and Social Security number, then your own name, Social Security number and home address. Part III is the signature, and every claimant signs it, whichever box was checked in Part I. By signing you also declare that you have examined the attached Nebraska return.
What usually delays the refund
- E-filing the return without the 1310N and its attachments. You can attach them as a PDF if your software allows it. If they are missing, the department may write to ask for them, and the instructions warn this can delay the refund.
- Checking box C when a court has appointed a representative, or is about to. Line 2 sends the claim back to that person.
- Sending a copy of the will as proof of appointment under box B.
- Leaving out the death certificate or notice under box C, with no “Proof of Death Previously Filed” note.
- Checking more than one box in Part I.
Where Form 1310N goes
On paper, it is attached to the deceased person’s Form 1040N or 1040XN, together with the documents for your box, and mailed to:
Nebraska Department of Revenue
PO Box 98911
Lincoln, NE 68509-8911
A surviving spouse returning a joint-name check under box A sends the check and the form to the same address. For questions, the department lists 800-742-7474 (calls from Nebraska and Iowa) and 402-471-5729.
Official PDF: Form 1310N — Official PDF (revenue.nebraska.gov)
Questions
Does this form also claim the federal refund?
No. Form 1310N covers the Nebraska refund only. A federal refund owed to someone who has died is claimed from the IRS on its own Form 1310.
Who signs if the surviving spouse files a joint return?
The spouse signs the 1040N as usual and writes “surviving spouse” in the signature area. Form 1310N is not used at all in that case.
Sources
- Nebraska Department of Revenue, Form 1310N, Statement of Person Claiming Refund Due a Deceased Person, 8-226-1972 Rev. 10-2023, form and instructions (revenue.nebraska.gov)
Last checked: October 23, 2026