A Nebraska corporation expecting at least $400 of income tax after allowable credits must make estimated payments. Form 1120N-ES supplies the worksheet and four vouchers for those payments. This guide uses the 2026 booklet, revision December 2025, including its separate payment boxes for corporations that distribute or operate cash devices.
Which corporations need 1120N-ES?
The requirement covers corporate taxpayers and S corporations that elect to pay Nebraska income tax. An S corporation without that election can make voluntary estimated payments; Nebraska treats those payments as withholding for its shareholders. A company whose worksheet line 5 is below $400 has no estimated-payment requirement under the booklet’s general rule, but a later increase in its expected tax can create an obligation during the year.
A unitary business filing one Nebraska corporate return may make combined estimated payments. It uses a combined Nebraska identification number, which the group can request from the Department of Revenue in writing. The same number belongs on the group’s return.
When are the installments due?
Regular estimated payments fall on the fifteenth day of the fourth, sixth, ninth and twelfth months of the corporation’s tax year. You can pay the full estimate with the first installment or pay equal installments at the applicable dates. A missed payment or an earlier underestimate calls for a catch-up payment with the next installment, according to the booklet.
Corporate distributors and operators of cash devices also have quarterly income tax payments, effective July 19, 2024. The booklet lists January 1, April 1, June 1 and October 1 for those payments. Distributor payments depend on the distributor’s income tax liability; operator payments depend on income from each device. These obligations are separate from the quarterly Net Operating Revenue tax on each device. If one voucher includes an ordinary estimated payment and a cash-device payment, select every applicable payment-type box.
How to complete the worksheet and voucher
Prepare the expected federal and Nebraska taxable income figures, estimated credits, the prior return’s overpayment election and the record of payments already made. The 2026 booklet applies a 4.55% rate to Nebraska taxable income for corporate taxpayers and electing S corporations. Keep the worksheet for your records; it is not submitted with the payment.
| Worksheet line | What to enter | Record to use |
|---|---|---|
| 1 | Expected federal taxable income. | The corporation’s federal income projection. |
| 2 | Expected Nebraska taxable income. | The state income calculation supporting the estimate. |
| 3 | Line 2 multiplied by 4.55%. | The 2026 rate printed in this booklet. |
| 4 | Expected credits. | The credit calculations for the tax year. |
| 5 | Line 3 less line 4. | The preceding worksheet entries. |
| 6 | The installment amount: one-quarter, one-third, one-half or all of line 5, depending on whether the original payment becomes due in month four, six, nine or twelve. | The first applicable payment date. |
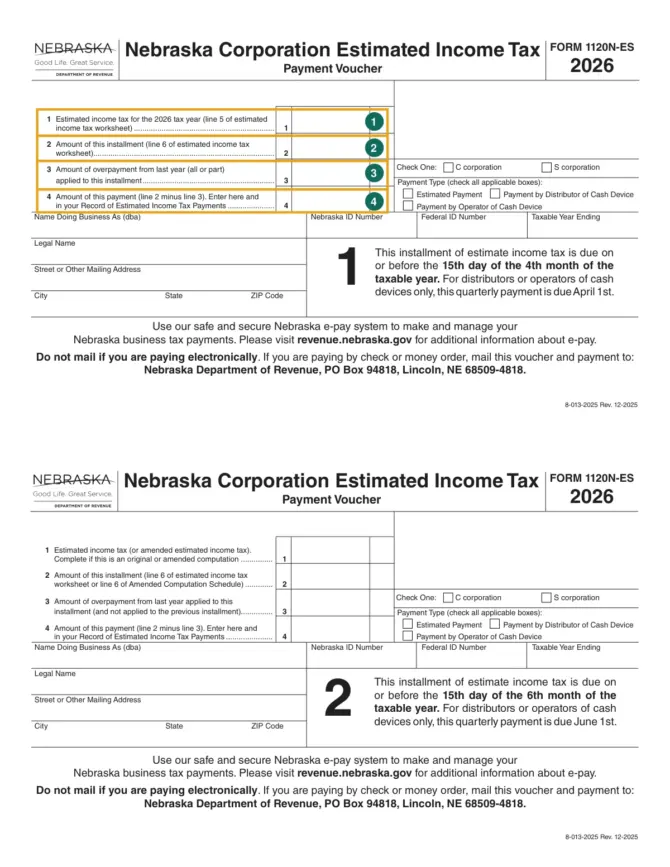
On the voucher, identify the corporation as C or S. Enter its doing-business-as name, legal name, Nebraska ID, federal ID, tax-year ending date and mailing address, including city, state and ZIP code. Choose Estimated Payment, Payment by Distributor of Cash Device, Payment by Operator of Cash Device, or the applicable combination. The vouchers have no signature field.
Voucher line 1 carries the annual estimate. On vouchers two through four, complete that line for an original or amended computation. Line 2 carries the installment from worksheet line 6, or amended-schedule line 6 if you have revised the estimate. Line 3 is the portion of the 2025 overpayment you are assigning to this installment. Subtract line 3 from line 2 to obtain the payment on line 4.
A prior-year overpayment is available here only if the 2025 Form 1120N or Form 1120-SN showed an overpayment and you elected to apply it to 2026 estimated tax. Allocate that credit once: amounts already used against earlier installments cannot be reused on a later voucher.
Recording payments and revising the estimate
The payment record on page 4 has a row for each installment. Column A records the filing date, B the actual payment from voucher line 4, C the overpayment credit from voucher line 3, and D their sum. Add the payments and credits for the amount claimed on the 2026 Form 1120N or 1120-SN.
If expected income or another item changes substantially, use all six lines of the Amended Computation Schedule. Enter the revised annual tax on line 1, the 2025 credit already applied on line 2 and actual 2026 estimated payments already made on line 3. Add lines 2 and 3 on line 4; subtract that result from line 1 for the unpaid balance on line 5. Divide the balance by the number of payments remaining on line 6. Transfer the revised annual tax and installment to lines 1 and 2 of the next voucher.
Paying online or mailing the official voucher
Download the 2026 Form 1120N-ES booklet. A corporation subject to a Nebraska electronic-payment mandate must use an electronic method. Other corporations can use the paper voucher with a check or money order payable to the Nebraska Department of Revenue. Mail it to Nebraska Department of Revenue, PO Box 94818, Lincoln, NE 68509-4818. An electronic payment does not require a mailed voucher.
The booklet describes Nebraska e-pay, ACH credit, Nebraska Tele-pay, credit cards and electronic funds withdrawal through an electronically filed return. With e-pay, enter the bank and payment details and choose the debit date; the service emails confirmation. Tele-pay, at 800-232-0057, takes those details by phone and provides a confirmation number. Both allow a debit date up to a year ahead. ACH credit requires you or your bank to originate a file in the required ACH format.
For cards, the booklet directs taxpayers to ACI Payments or 800-272-9829 and lists American Express, Discover, MasterCard and Visa. The processor charges a separate convenience fee. Telephone card payments use Nebraska jurisdiction code 3700; retain the transaction confirmation.
To cancel a scheduled electronic funds withdrawal, the booklet requires contact with Taxpayer Assistance at 800-742-7474 or 402-471-5729 before 4 p.m. Central Time two business days before the debit. Cancel an e-pay transaction through its cancel-payment option. The card-cancellation paragraph names Official Payments, while the payment paragraph names ACI Payments; use the provider and contact details on the transaction confirmation to resolve a card cancellation.
Underpayments and an early refund of excess estimates
An underpayment can produce a penalty. The booklet directs corporations with an underpayment to attach Form 2220N to their Nebraska Form 1120N or 1120-SN. That form contains the methods that can avoid a penalty; the $400 estimated-payment threshold alone does not calculate an underpayment penalty.
A corporation can request an adjustment of excess estimates on Form 4466N when the overpayment is at least $500 and at least 10% of expected income tax liability. File that application by the fifteenth day of the third month after the tax year ends, before filing the income tax return.
If the corporation’s name or address on its tax account needs updating, see Nebraska Form 22. For the corporate return calculation, use the Department’s corporation income tax forms page.