Nebraska’s 1041N-ES is a voluntary estimated-payment voucher for an estate or trust. The 2026 form contains identification fields, a taxable-year ending date and an amount remitted; it does not calculate the estate’s income tax.

Who uses the fiduciary voucher?
The Nebraska fiduciary instructions say estates and trusts are not required to make estimated tax payments. An estate or trust choosing to make a voluntary estimated payment uses 1041N-ES. This differs from treating every estimated-tax voucher as a compulsory quarterly installment.
The official fiduciary forms page identifies this copy as the 2026 voucher. Although its download address includes a 2025 directory, the PDF itself is printed “2026” and carries document number 8-683-2025. Use the year on the form when checking which voucher you downloaded.
Fill in the estate and fiduciary details
The voucher distinguishes the estate or trust from the person acting for it. Use the name of the estate or trust in its own field and the fiduciary’s name and title in the following field. The highlighted areas in the image show the identification block and the year/payment block.
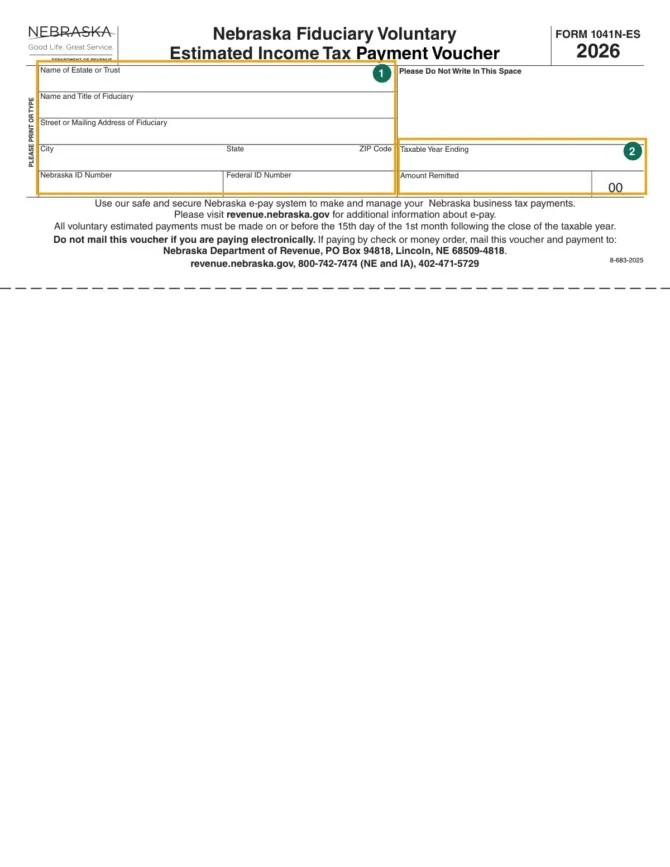
| Voucher field | Entry | Where to find it |
|---|---|---|
| Name of estate or trust | The entity for which the payment is being made | The fiduciary tax records |
| Name and title of fiduciary | The person acting for the estate or trust and their capacity | The fiduciary appointment records |
| Address | The fiduciary’s street or mailing address, city, state and ZIP Code | Current correspondence details |
| Nebraska ID and federal ID | The entity’s respective state and federal identifiers | Its tax registration records |
| Taxable year ending | The end date of the tax year receiving the payment | The estate’s or trust’s accounting period |
| Amount remitted | The amount being paid with this voucher | The check or money order and payment records |
Print or type the information. Leave the area labelled for department use empty. There is no calculation schedule on this one-page voucher, so complete the tax calculation using the relevant fiduciary return instructions before choosing a payment amount.
When a voluntary payment must arrive
The voucher states that all voluntary estimated payments must be made on or before the 15th day of the first month following the close of the taxable year. For a calendar year ending December 31, 2026, that wording gives January 15, 2027.
A fiscal-year estate should apply the wording to its own year end, which also belongs in the taxable-year field. The form does not print a four-installment calendar. Do not substitute dates from an individual’s estimated-tax voucher for the deadline stated on 1041N-ES.
Pay electronically or mail the voucher
The form directs taxpayers to Nebraska e-pay as an electronic option. It explicitly says not to mail the voucher when paying electronically. A mailed check or money order travels with the voucher to Nebraska Department of Revenue, PO Box 94818, Lincoln, NE 68509-4818.
Keep the payment confirmation or a copy of the mailed payment with the estate’s tax records. The 2025 fiduciary instructions show estimated payments in the return’s payment section, line 27; for a 2026 return, check that year’s final instructions before transferring the total.
A refund due to a deceased individual uses a different process. Form 1310N documents the person claiming that refund; it does not serve as the estate’s voluntary estimated-tax payment slip.
Official PDF: Form 1041N-ES — Official PDF (revenue.nebraska.gov)