Nebraska Form 33 can authorize a representative to receive confidential tax information and deal with the Department of Revenue (DOR). It also contains two revocation choices. Leaving both unchecked keeps prior powers of attorney in force, so completing a new appointment does not automatically remove existing representatives.

Who needs a Nebraska power of attorney?
A taxpayer appointing someone to act before DOR must file Form 33 or another properly completed and signed power of attorney. DOR must have the authorization before the representative acts in matters involving confidential tax information. The department’s listed Form 33 is the April 2022 revision.
The form calls the representative an attorney-in-fact, which its instructions define as a person or firm acting for another. You can appoint a firm by entering All members in the name field and supplying the firm name. There is room for two appointees; additional appointees go on an attached sheet with their contact information.
Completing the taxpayer and authority sections
Use the taxpayer’s identification details and state exactly which taxes, issues and periods the appointment covers. The form separates those three parts of the authorization.
| Section | What to enter | Instruction to apply |
|---|---|---|
| Taxpayer | Name, address and identifying numbers. | Individuals supply an SSN. For a joint return, enter both spouses’ SSNs. |
| Business or fiduciary details | Business information, or the fiduciary’s name, title and address for an estate or trust. | Include the taxpayer’s own name and ID number or SSN; label information placed in a repurposed field. |
| Attorney-in-fact | Each appointee’s name, firm and contact details. | Attach a separate list when appointing more than two. |
| Tax category | The tax type, such as income or sales and use. | Identify every category covered. |
| Tax matter | The issue, such as an audit assessment, refund claim or penalty abatement. | A brief description defines the subject of representation. |
| Tax period | The year or period involved. | The instructions permit all years or all periods. The table has three rows. |
| Authorized acts | Keep the powers you intend to grant and strike through excluded powers. | Add a specific statement for an act not already listed. |
Authority to receive a refund check does not include endorsing or collecting it. For notices, strike through the correspondence authorization if you want to receive those communications yourself. Deficiency determinations and amended notices still go directly to the taxpayer, with a copy to the designated representative.
Choosing revocation box A or B
The marked area shows the two choices near the signature block. Box A describes revocation for the same tax matters and periods, with space for exceptions. List the representatives you want to retain, their addresses and the dates of the earlier authorizations, or attach copies of those authorizations.
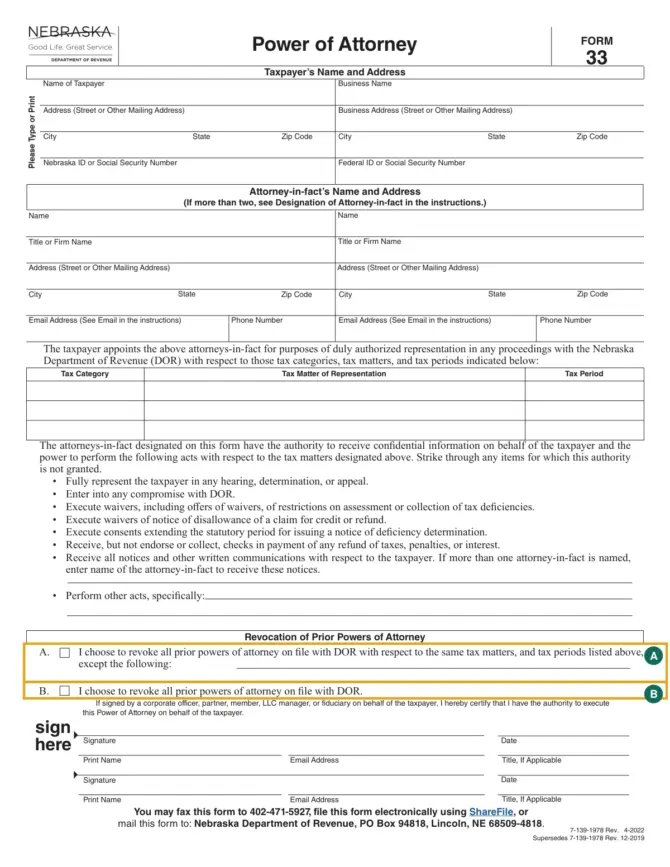
Box B revokes all prior powers of attorney filed with DOR. If you select neither box, the instructions say all prior authorizations remain effective. Read the choice before signing rather than treating revocation as a required part of every appointment.
Who signs, and where is Form 33 filed?
The taxpayer signs and dates the form. For a jointly filed return signed by both spouses, both must sign Form 33; they can use separate forms if necessary. A corporation’s signing officer must have authority to bind it and state the official title. A Nebraska LLC uses a member’s signature. Partnerships, foreign LLCs and fiduciaries should follow the specific signature rules on page 2.
All authorizations must contain the original signature of a person authorized to sign. The form permits submission by fax to 402-471-5927, by mailing to Nebraska Department of Revenue, PO Box 94818, Lincoln, NE 68509-4818, or by uploading a copy of the original through the department’s ShareFile system. Follow the electronic filing link in the official PDF for that route.
The form may be filed at any time, but must be on file before confidential representation begins. Keep the tax procedure itself separate from the authorization: for example, a deceased taxpayer’s Nebraska refund claim has its own Form 1310N requirements.