A business move and a change of ownership take different routes on Nebraska Form 22. A move can be reported in the new-address section. A change of ownership or federal employer identification number requires cancellation of the old certificates, licenses and permits, followed by a Form 20 application for the new entity.

Who uses Nebraska Form 22?
Form 22 covers changes to Nebraska tax registrations, including cancellation, reinstatement, filing frequency and changes in officers, members or partners. One request can cover several tax programs when they share the same Nebraska ID number. Individual income tax name and address changes use Form 22A.
This guide uses the PDF marked Rev. 9-2026. The department’s multi-use forms index still labels its Form 22 link 09/2021, but the linked document carries the September 2026 revision. Its program list includes kratom product retailer excise tax and remittance transfer excise tax.
How to complete the identification and action boxes
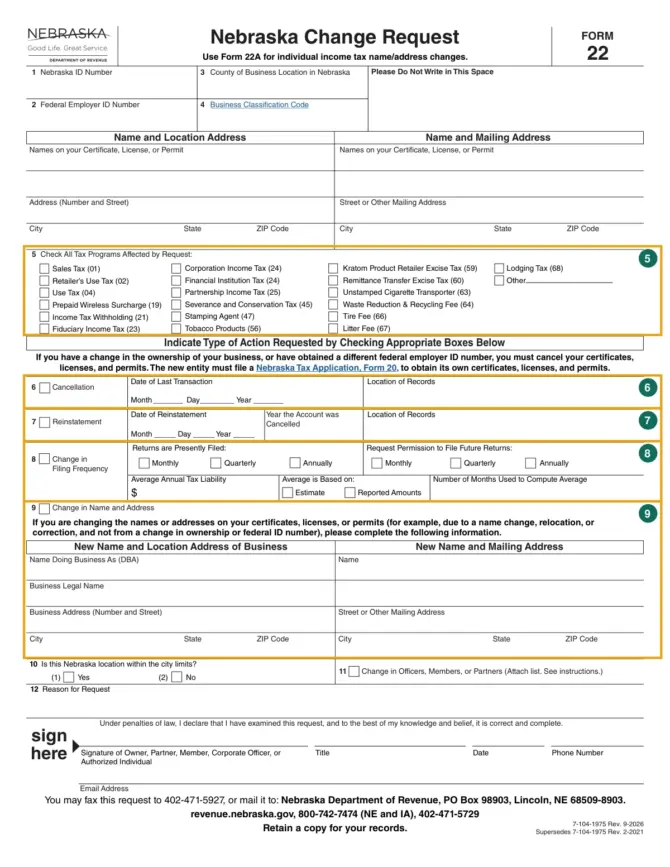
Put the existing names and addresses at the top, as last filed with the Department of Revenue (DOR) or printed on the certificate. The replacement name or address goes below line 9. Select both the tax programs affected and the action requested.
| Line | Entry | Record to use |
|---|---|---|
| 1–4 | Nebraska ID, federal employer ID, Nebraska county and business classification code. | Your registration details. Line 1 is not for an SSN; line 2 has separate instructions when no EIN is held. |
| 5 | Every tax program affected by the request. | The certificates, licenses or permits being changed. |
| 6 | Cancellation date based on the last transaction, and location of records. | The business’s closing or last-activity records. |
| 7 | Reinstatement date, year canceled and records location. | The previously canceled account. |
| 8 | Current and requested filing frequency, annual tax liability, calculation basis and number of months. | Reported amounts or the estimate used for the request. |
| 9–10 | New business and mailing details, plus whether the Nebraska location is within city limits. | The new physical location and chosen mailing address. |
| 11–12 | Officer, member or partner changes and an explanation of the request. | An attached list and the reason for the change. |
The business location must be a street address, not a PO Box. A preparer or another recipient can be entered in the separate mailing-address area. For line 11, attach the names, street addresses, email addresses, titles and SSNs of the officers, members or partners; identify removals and the effective dates.
Requesting a different filing frequency
The line 8 instructions allow quarterly requests for sales tax, use tax or tire fee liabilities of $900 to $3,000 annually, and annual requests below $900. Lodging tax filers remitting $99 or less annually may request annual filing. Employers withholding less than $500 of Nebraska income tax annually may request annual filing instead of quarterly filing.
A request does not change the schedule immediately. DOR approval must arrive first, and the taxpayer must file the preidentified returns received for periods before approval.
When and where to send Form 22
The instructions say to submit the request before the change. Fax it to 402-471-5927 or mail it to Nebraska Department of Revenue, PO Box 98903, Lincoln, NE 68509-8903. An owner, partner, member, corporate officer or person authorized by a power of attorney on file with DOR must sign.
Closing a business does not remove its final-return requirements. File through the last transaction or wage-payment date. Employers canceling withholding should file the final Form W-3N with employee W-2 state copies within 30 days after discontinuing business.
Reinstatement is available only if no business change has occurred that would require a new certificate, license or permit. Download both pages below: the second page supplies the eligibility and signature instructions used for the request.