Nebraska Form 7004N combines a filing-extension request with a tentative tax payment. Its August 2025 revision provides different extension choices for corporations, estates, trusts and partnerships. A federal extension and an electronic extension payment can change which paperwork you need to send now and with the final return.
Who files 7004N and which extension box applies?
A corporation, fiduciary, partnership or limited liability company uses this form when the federal Form 7004 route has not been properly completed and granted, when a tentative Nebraska payment is needed, or when a corporation needs Nebraska filing time beyond its federal extension. If you have filed for a federal extension and are making no tentative Nebraska payment, the instructions say this application need not be completed. Attach the filed federal Form 7004 or approved extension when submitting the Nebraska return.
At the top, enter the taxable year’s beginning and ending dates, doing-business-as name, legal name, mailing address, city, state, ZIP code, federal ID and Nebraska ID.
The six-month section has separate boxes for Form 1041N and Form 1065N. Federal extensions carry through for the period allowed for partnerships; estates and trusts receive up to six months. The instructions permit no additional Nebraska extension for these filers.
For Forms 1120N and 1120-SN, select the applicable seven-month choice: an automatic extension from the original deadline or additional time beyond the federal extension, capped at seven months from the original Nebraska deadline. Attach the filed federal Form 7004 for the additional-time choice. Answer each corporate classification question: exempt organization, cooperative under IRC section 6072(d), S corporation and foreign corporation without U.S. offices.
How to fill out the tentative payment calculation
Fiduciary and partnership filers skip lines 1 through 10 and complete line 11. Corporate filers use the full calculation. The marked lines show the initial liability, the amount after nonrefundable credits and the final tentative payment.
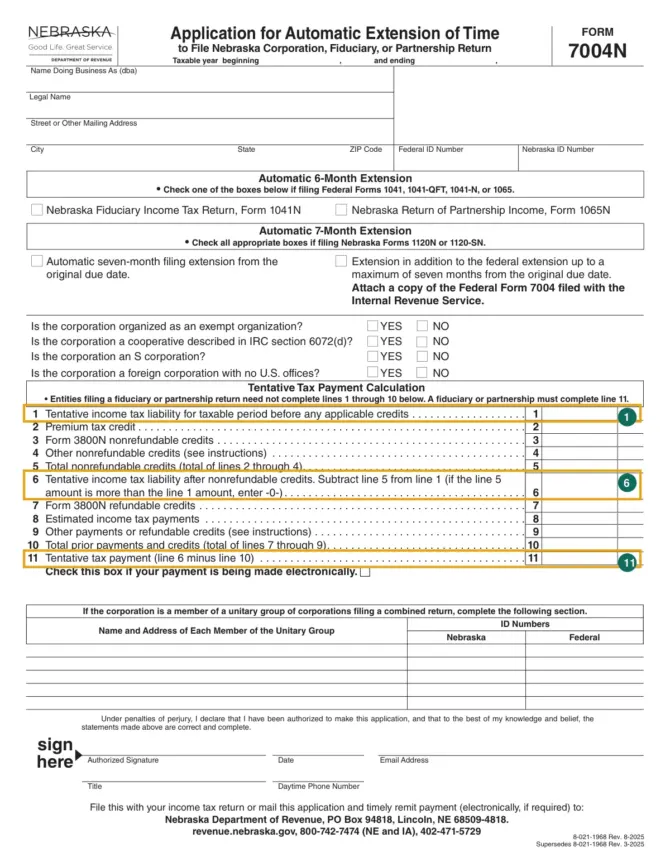
| Line | Entry | Calculation or record |
|---|---|---|
| 1 | Estimated income tax liability before credits | Tax-period calculation |
| 2 | Premium tax credit | Eligible credit records |
| 3 | Form 3800N nonrefundable credits | Incentive credit calculation |
| 4 | Other nonrefundable credits listed in the instructions | Eligible credit schedules and certificates |
| 5 | Total nonrefundable credits | Lines 2 through 4 added together |
| 6 | Tentative liability after nonrefundable credits | Line 1 less line 5; enter zero if credits exceed liability |
| 7 | Form 3800N refundable credits | Refundable incentive credit calculation |
| 8 | Estimated tax payments | Payments already made for this period |
| 9 | Other payments or refundable credits | Eligible payments and credits under the line 9 instructions |
| 10 | Total prior payments and credits | Lines 7 through 9 added together |
| 11 | Tentative tax payment | Line 6 less line 10 for the full calculation; fiduciaries and partnerships enter their payment directly |
Line 4 covers the TANF/ADC employer expense credit, School Readiness provider credit, CDAA, convicted-felon employment credit, Opportunity Scholarship contributor credit, Child Care contributor credit, CHIEF and Pregnancy Help Act credit. Include amounts for which the filer qualifies.
Line 9 includes Beginning Farmer credit, Nebraska withholding, Property Tax Incentive Act credits and PTET credit. The instructions specify that, from 1 January 2024, the property-tax credit here covers community college taxes; school district relief is applied directly on the property-tax statement. A partnership ownership share of Nebraska PTET can belong here. For fiduciary estimated payments, retain the records supporting Form 1041N-ES.
When to sign and pay, including a federal extension
Without a properly filed and granted federal extension, sign by the original return due date. Tentative tax must be remitted by that original deadline regardless of payment method. A corporation requesting additional Nebraska time after a federal extension signs by the federal extension’s expiry date. The extension does not move the original payment deadline.
For a combined unitary group, request one extension for the group and list every member’s name, address, federal ID and Nebraska ID. An authorized corporate officer, fiduciary, partner, member or qualifying tax professional signs. Another authorized signatory needs a power of attorney on file with DOR. Add the date, title and daytime phone number. An email address permits email contact; write “Opt Out” in that field if you decline it.
Pay electronically or mail the form with payment
Electronic options listed in the form are Nebraska e-pay, ACH credit and Nebraska Tele-pay. Credit cards are available for corporations through the provider named in the instructions, with a separate convenience fee. Keep the confirmation number or email. DOR notifies mandated taxpayers in writing. Its EFT FAQs state that paying by check or money order while mandated attracts a $100 penalty. Check the mandate notice before using paper. No zero-dollar EFT transfer is needed, although return filing obligations remain. Schedule electronic payments in time for the method-specific submission and bank settlement rules in those FAQs. Select the applicable FTA tax type code for an extension payment.
Check the form’s electronic-payment box when paying electronically. Retain and attach Form 7004N and/or the applicable federal Form 7004 to the final Nebraska return, and check that return’s “7004/7004N Attached” box. The instructions warn that an omitted checkbox can cause processing delays or an incorrect balance-due notice.
For a permitted check or money-order payment, make it payable to Nebraska Department of Revenue and mail it with Form 7004N to Nebraska Department of Revenue, P.O. Box 94818, Lincoln, NE 68509-4818. The department may present a check electronically.
DOR sends a denial notice if the request is refused, but no approval notice for an accepted extension. It can terminate a C corporation’s extension by notice allowing ten days from the notice date to file. Keep the signed application and federal extension evidence rather than waiting for an approval letter.
Official PDF: Form 7004N — Official PDF (revenue.nebraska.gov)