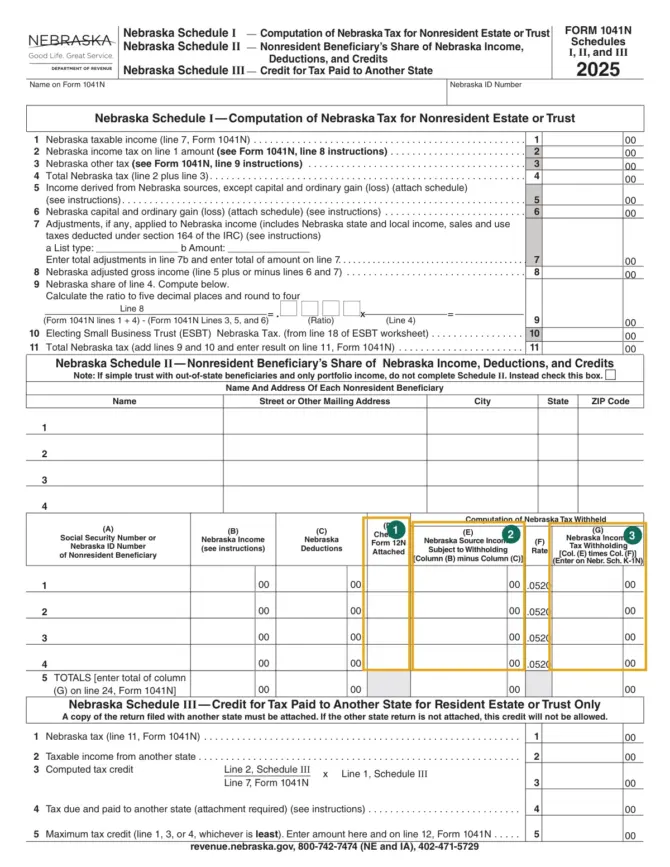
An estate or trust distributing Nebraska-source income to a nonresident individual beneficiary uses Schedule II of Form 1041N to calculate beneficiary withholding. The schedule connects the fiduciary return’s line 24 with each beneficiary’s Nebraska Schedule K-1N.
This guide covers tax year 2025. Schedule II appears on page 3 of the official Form 1041N PDF, between Schedules I and III. The 2025 booklet supplies the source-income rules and Form 12N exception.
Who must complete Nebraska fiduciary Schedule II?
The schedule identifies nonresident beneficiaries and computes withholding on distributable net income from Nebraska sources for nonresident individuals. The booklet gives two exceptions to completing it: all beneficiaries are Nebraska residents, or a simple trust has nonresident beneficiaries and receives only portfolio income. In the simple-trust case, check the box immediately below the Schedule II heading.
For this purpose, portfolio income generally includes interest, dividends and royalties outside the ordinary course of a trade or business. The column B instructions exclude portfolio income and accumulation distributions. A distribution that includes both Nebraska business earnings and investment income therefore needs a source breakdown before the schedule is prepared.
How to complete columns A through G
Enter each nonresident beneficiary’s name and address in the upper part of Schedule II. Match each person to the corresponding numbered row in the calculation table. Attach another schedule in the same format when more space is needed.
| Column | Entry | Supporting record |
|---|---|---|
| A | Social Security number or Nebraska ID for the nonresident individual | Beneficiary identification |
| B | Beneficiary’s current distributable net income from Nebraska sources | Income allocation excluding portfolio income and accumulation distributions |
| C | Beneficiary’s deductions related to column B income | Deduction allocation to that Nebraska income |
| D | Check when a signed, properly completed Form 12N is attached | Beneficiary’s 2025 nonresident income tax agreement |
| E | Column B less column C, or zero if the difference is negative | Net Nebraska income subject to withholding |
| F and G | 2025 rate .0520; multiply column E by it for column G | 2025 schedule and booklet |
The illustration marks column D as frame 1, column E as frame 2 and column G as frame 3. When column D is checked for a properly completed Form 12N, the instructions say not to complete columns E and G. Withholding is not remitted for that beneficiary under this agreement procedure.
Calculating the 2025 amount and transferring it
For an illustrative beneficiary without Form 12N, $18,000 of qualifying Nebraska income in column B and $3,000 of related deductions in column C leave $15,000 in column E. Multiplying by .0520 gives $780 in column G. These example figures are hypothetical; the 5.20% rate comes from the 2025 instructions.
Report each beneficiary’s withholding on their Nebraska Schedule K-1N. Add all column G entries and carry the total to Form 1041N, line 24. That total is beneficiary withholding; the return separately calculates the estate or trust’s own income tax liability.
Where to get and submit Schedule II
Download the complete 2025 Form 1041N and fiduciary booklet from the Nebraska Department of Revenue. Schedule II is part of the fiduciary return, so submit it with Form 1041N and the required supporting schedules. The return directs paper filings and payment to Nebraska Department of Revenue, P.O. Box 94818, Lincoln, NE 68509-4818, and requires a copy of the federal return and schedules.
Keep the beneficiary allocation and signed Form 12N records with the return preparation papers. Source-income classification and the agreement procedure can affect both the trust and its beneficiaries; consult the fiduciary’s tax preparer when the allocation is disputed or involves several states.
Official PDF: Schedule II (1041N) — Official PDF (revenue.nebraska.gov)