Houses, flats, farmland, a garage block, fishing rights: anything the deceased owned in land or rights over land goes on schedule IHT405 when a full IHT400 account is needed. The edition in use, HMRC 04/26, also sets out the cap on 100% Agricultural and Business Relief for deaths on and after 6 April 2026.

Who HMRC talks to about the valuation
Boxes 1 to 5 on page 1 are optional. Fill them in only if HMRC should contact someone about the property values other than the person in box 17 of the IHT400. That person must have the personal representatives’ authority to be contacted.
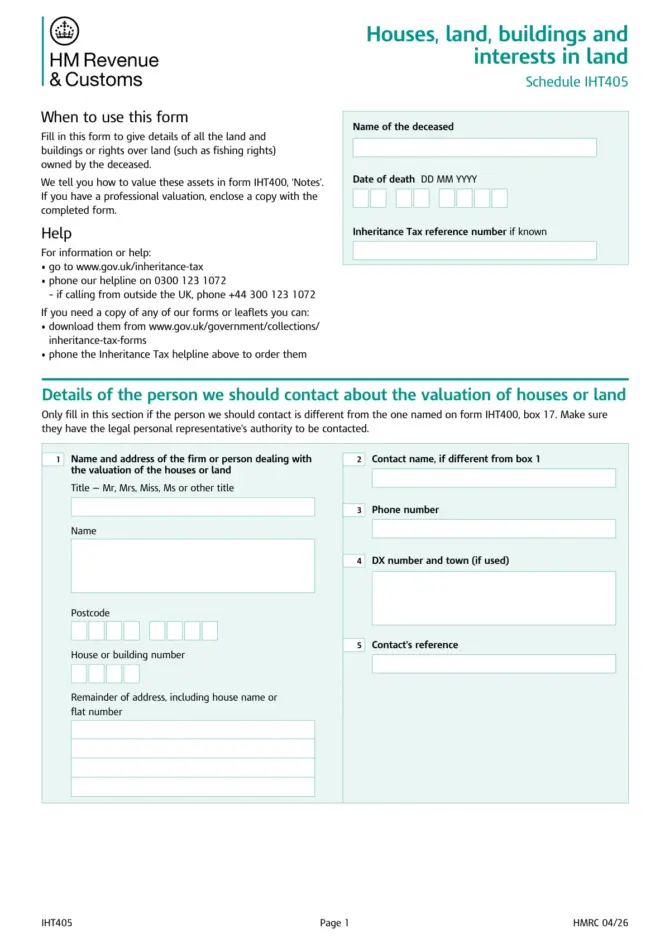
If you have a professional valuation, send a copy with the schedule. How HMRC expects these assets to be valued is in the IHT400 notes.
Columns A to H, property by property
Pages 2 and 3 are tables. Page 2 is for the deceased’s residence; page 3 for other land, buildings and rights over land. Use extra copies if there are many properties.
| Column | What goes in it |
|---|---|
| A | Item number, used again on page 4 |
| B | Full address or description. Land without a street number, such as farmland, needs a plan showing the boundaries. |
| C | Postcode |
| D | Tenure: freehold, or leasehold with years left and annual ground rent |
| E | Lettings: a copy of any lease or tenancy, or the start and end dates, rent, review terms, who pays outgoings and the tenant’s name. “Vacant” if empty at the death. |
| F | Value qualifying for Agricultural or Business Relief at 100%, Woodlands Relief or heritage exemption |
| G | Value qualifying for Agricultural or Business Relief at 50% |
| H | Open market value at the date of death |
The column H total on page 2 goes to IHT400 box 51. The page 3 total is included in boxes 68 to 70. Relief claimed goes in box 93. For rights over land, such as fishing or mineral rights, describe the rights as well as the land.
The £2.5 million cap
The 04/26 form sets out the rule. For deaths on and after 6 April 2026, 100% relief on the combined value of qualifying agricultural and business property is limited to £2.5 million. That figure counts gifts of qualifying property made on or after 30 October 2024 within 7 years of the death, and other property treated as part of the estate, trust property included. Value above £2.5 million gets relief at 50%, and the form has separate columns for the two rates (F and G).
A late spouse’s or civil partner’s unused £2.5 million allowance can be transferred, if the claim is made within 4 years of the survivor’s death or within 6 months of the personal representatives starting to act.
Business Relief cannot be deducted for a business dealing in property or investments. If you deduct Business Relief, also complete IHT413; for Agricultural Relief, IHT414.
Page 4: anything that changes the value
The first question asks about special factors, such as major damage or development potential. Give details by item number and enclose a survey, structural engineer’s report or planning approval notice where relevant. Damage covered by building insurance can change how HMRC values the property, so boxes 9 and 10 ask whether the deceased’s insurance covered the repairs and whether a claim will be made. Copies of correspondence with insurers or loss adjusters go with the form.
Box 11: a sale within 12 months
If any property has been sold, or will be sold within 12 months of the death, list it. For each: whether it is sold, on the market or to be sold later, with the exchange date (or date missives were concluded in Scotland); the asking or agreed price before selling costs; whether the buyer is a relative, friend or business colleague; any price for fixtures, carpets and curtains; and whether you want to use the sale price as the value at death.
With the IHT400
IHT405 goes in with the IHT400 and the other schedules, and its totals must agree with the IHT400 boxes above. The Inheritance Tax helpline printed on the form is 0300 123 1072, or +44 300 123 1072 from abroad.
Official PDF: IHT405 — Official PDF (assets.publishing.service.gov.uk)
Where this comes from
- HM Revenue and Customs, Schedule IHT405 Houses, land, buildings and interests in land, HMRC 04/26 (assets.publishing.service.gov.uk)