If you inherit furniture, clothing or other personal possessions and decide to give them to charity, IHT408 can record that gift for the estate’s charity exemption claim. It deals with a decision by the beneficiaries after the death. Goods already left to a charity in the will do not belong on this form.

Who should use IHT408?
The beneficiaries must have inherited the household or personal goods and want to give some or all of them to a qualifying charity. The May 2024 form states that, from 1 April 2023, the charity must be established for charitable purposes, be UK registered for Inheritance Tax purposes and have fit and proper managers.
HMRC describes IHT408 as the standard way to make this variation for household goods without submitting a separate formal Instrument of Variation. Its declaration invokes section 142(1) of the Inheritance Tax Act 1984 and section 62(6) of the Taxation of Chargeable Gains Act 1992. Ask the estate’s solicitor or tax adviser about eligibility if the proposed recipient or beneficiaries’ entitlement is uncertain.
How to complete the IHT408 declaration
Identify the deceased at the top of page 1. Then decide whether the gift covers all the inherited goods or only the items listed on page 2. The numbered highlights below refer to the areas in this table; the printed form itself uses named sections.
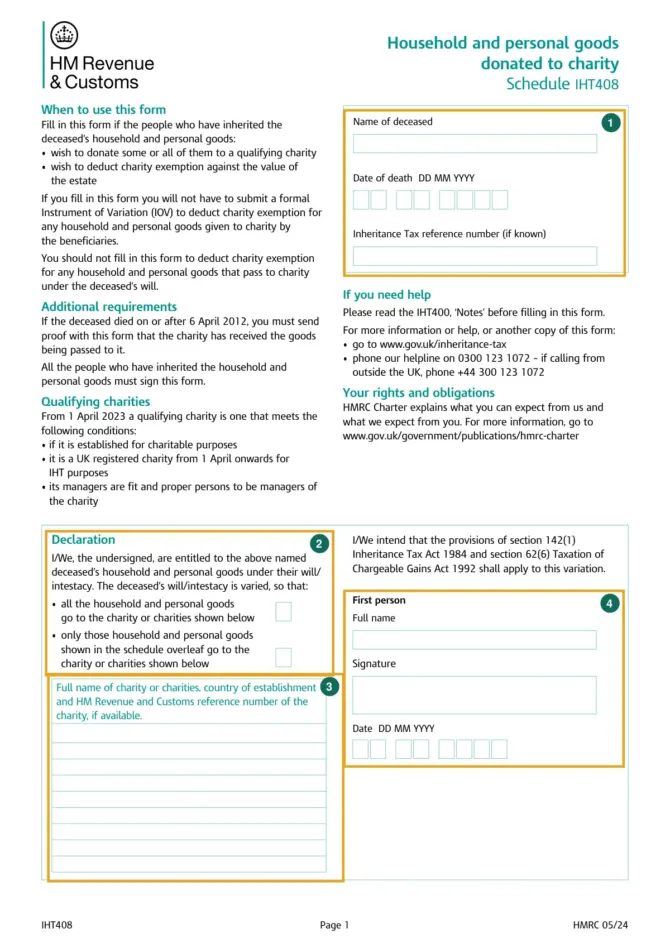
| Marked area | What to enter | Information to use |
|---|---|---|
| 1: Estate details | Name, date of death and Inheritance Tax reference if known. | The estate’s records and HMRC reference. |
| 2: Declaration choice | Select all goods or only the goods listed in the schedule. | The beneficiaries’ agreed donation. |
| 3: Charity details | Full name of each charity, country of establishment and HMRC charity reference if available. | Details supplied by the recipient charity. |
| 4: First beneficiary | Full name, signature and date. Further signature spaces are on page 2. | Each beneficiary who inherited the goods. |
All the people who inherited the household and personal goods must sign. Page 2 provides spaces for the second, third and fourth person. The declaration is not completed solely by an executor unless the required beneficiaries have also signed.
Listing a partial donation and claiming its value
If the beneficiaries keep some possessions and donate the rest, fill in the schedule of items on page 2. It asks for a description, the charity receiving the goods and their value. You can describe identifiable pieces separately, such as a wardrobe, and group suitable items under descriptions such as clothing.
The donated items must also remain in the household-goods valuation on IHT407. The IHT400(2022) Notes direct you to show the charity exemption in box 92 of IHT400. Record the goods and the exemption in their respective places; do not simply leave the donated goods out of the estate’s asset schedule.
Evidence to obtain from the charity
For deaths on or after 6 April 2012, the May 2024 IHT408 asks for proof that the charity has received the goods. Keep a receipt identifying what was handed over and send a copy with the form.
The IHT400(2022) Notes use broader wording: correspondence showing that a charity is to receive, or has received, the goods is sufficient, and a charity-shop receipt is acceptable. This differs from the form’s receipt requirement. If the goods have not yet been delivered, confirm with HMRC what evidence it will accept before relying on an agreement to receive them.
Official PDF and time limits
The official IHT408 publication page below provides the two-page PDF for use with IHT400. Download both pages, including the additional signatures and item schedule.
The government’s variation guidance sets a two-year limit from death for completing changes to an inheritance. This is separate from the IHT400 reporting deadline: the IHT400 Notes require the account within 12 months of death. If the account has already been sent, ask HMRC how to submit the additional schedule and revise the exemption claim.
For an estate that also includes a house, IHT405 deals with the property details. The IHT408 household-goods donation does not replace that property schedule.
Official PDF: IHT408 — Official PDF (assets.publishing.service.gov.uk)
Sources
- IHT408 – Household and personal goods donated to charity
- Inheritance Tax: household and personal goods donated to charity (IHT408) – GOV.UK
- IHTM11139 – Procedure: household and personal goods donated to charity (Form IHT408) – HMRC internal manual – GOV.UK
- IHT400(2022) Notes, accessed 27 October 2026
- Change a will after a death