IHT421 summarises the property covered by a Northern Ireland grant of representation. Its probate figures can differ from the estate values used to calculate Inheritance Tax. The January 2024 form is for Northern Ireland; estates in England and Wales use HMRC probate figures and a unique reference, while Scottish confirmation uses form C1.
Who needs IHT421 with an estate account?
Personal representatives preparing a full IHT400 account for a Northern Ireland grant complete the summary after filling in and signing IHT400. The Probate Registry needs the values from that account before issuing the grant.
An excepted estate follows a different reporting route. NIdirect directs deaths on or after 1 January 2022 that qualify as excepted estates to Estate Summary Form NIPF7, without a separate HMRC account form. For deaths on or before 31 December 2021, it points to IHT205. Where tax is due or full details are required, use the IHT400 route. Confirm the estate category before preparing IHT421.
Complete the contact details and deceased’s identity
Page 1 asks for a contact name, full address and postcode, the Inheritance Tax reference if known, your own reference where applicable, a named contact and a telephone number. Use details through which the estate’s correspondence can be handled.
Enter the deceased’s title, surname, first names and date of death in day-month-year order. Use capital letters for their details. The address fields separate the postcode, house or building number, and the rest of the address, including a flat or house name. Answer where the deceased was domiciled at death. Obtain advice on domicile if the estate has cross-border circumstances; it is a specific field on this form.
How to fill in the six summary boxes
Use the completed IHT400 and IHT404 figures as the source for the summary. The marked illustration follows boxes 1, 3 and 5 from the UK estate amount through to the net probate value.
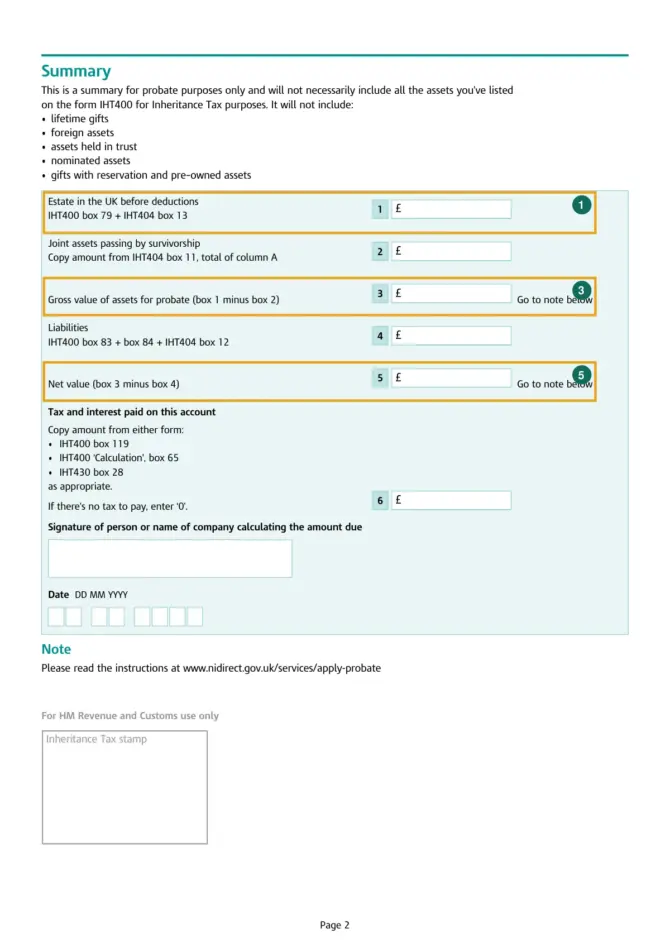
| IHT421 box | Entry or calculation | Where it comes from |
|---|---|---|
| 1 | UK estate before deductions | IHT400 box 79 plus IHT404 box 13 |
| 2 | Joint assets passing by survivorship | IHT404 box 11, total of column A |
| 3 | Gross probate assets: box 1 less box 2 | The preceding two entries |
| 4 | Liabilities included in the summary | IHT400 boxes 83 and 84 plus IHT404 box 12 |
| 5 | Net probate value: box 3 less box 4 | Gross probate value and liabilities |
| 6 | Tax and interest paid on the account; zero where no tax is payable | IHT400 box 119, IHT400 Calculation box 65 or IHT430 box 28, as applicable |
The summary excludes lifetime gifts, foreign assets, assets held in trust, nominated assets, gifts with reservation and pre-owned assets. Keep these exclusions in mind when reconciling IHT421 to the tax account. An asset being reported elsewhere for tax does not automatically put it into the probate summary.
For a hypothetical reconciliation, box 1 of £460,000 less box 2 of £60,000 gives a £400,000 gross value in box 3. If box 4 contains £24,000 of liabilities, box 5 is £376,000. These example values illustrate the printed arithmetic; they are not allowances or tax thresholds.
Finish the section asking for the signature of the person, or the name of the company, calculating the amount due, then enter the date. Leave the Inheritance Tax stamp area for HMRC.
When and where to send the probate summary
Prepare IHT421 after the IHT400 account is completed and signed. Print the form and send it with the account and applicable schedules to Inheritance Tax, HMRC, BX9 1HT, United Kingdom. Assemble the supporting papers using the checklist on IHT400, including any schedules needed for the estate’s assets, liabilities and reliefs.
The Northern Ireland procedures on printed pages 64 and 67 of the IHT400 notes say HMRC completes its part of IHT421 and returns it to you once the requirements are met. Where you ask HMRC to calculate the tax, it sends a calculation first; pay the amount due before the completed summary is released. Follow HMRC’s reply and the Northern Ireland probate application instructions when proceeding with the court application. IHT421 itself does not issue the grant or finalise the estate’s tax position. NIdirect separately lists the court application documents, original will where applicable, identity checks and fee.
The ordinary estate tax payment deadline is the end of the sixth month after death, and interest runs on late payment. The amount required before the grant can depend on whether instalments are available for particular assets; use the IHT400 calculation and HMRC payment instructions for the estate.
Use the asset schedules to support the underlying account: for example, IHT405 for land and buildings or IHT406 for bank and building society accounts. If an estate value or liability later changes and alters the tax, the IHT400 notes require you to tell HMRC.
Official PDF: IHT421 — Official PDF (assets.publishing.service.gov.uk)