Listed shares and UK government stock go into different tables on IHT411. The market values then feed separate boxes on IHT400, while interest and dividends due at death feed box 64. Keeping those amounts separate at the valuation stage makes the transfer to the main account easier to follow.

Which holdings belong on IHT411?
Use the schedule with IHT400 for the listed holdings described in the form, including UK government and municipal securities. This guide uses HMRC’s September 2022 revision, available from the publication page updated in December 2022.
Private-company shares, holdings on markets HMRC does not recognise as listed, and listed holdings that gave the deceased control of the company belong on IHT412. A share being traded does not, by itself, place it in IHT411. Check the market’s classification and the nature of the holding.
The second table includes unit trusts, investment trusts, open-ended investment companies and the listed ISA investments described by the form. Its foreign-share entry covers shares listed on the London Stock Exchange or other UK exchanges. Use the IHT400 notes to classify assets outside that description.
Preparing the date-of-death figures
Record the holding’s full description, quantity, market price per unit and total value. Also identify dividends or interest that were due at death but unpaid. A nominal or face value is not automatically the market value requested by the schedule.
HMRC’s valuation guidance explains how stock-exchange markings affect the calculation. For example, an ex-dividend marking can mean a dividend remains payable to the deceased. For gilts and other fixed-interest securities, accrued interest may need a separate calculation. Use the relevant valuation instructions for the holding.
If you have a stockbroker’s valuation, or have completed Scotland’s C1 inventory, the form allows you to transfer the totals for each category and enclose a copy of the valuation. Retain the category split; a single combined portfolio figure does not supply both tables’ totals.
How the two tables feed IHT400
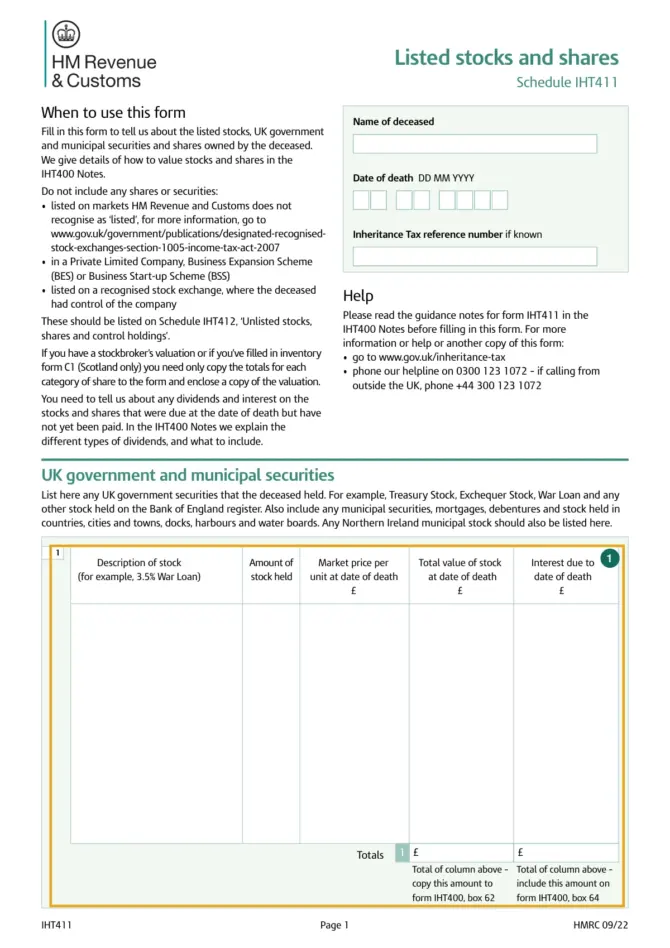
The marked form section shows table 1 for government and municipal securities. Table 2 continues on the next page for listed investments without a controlling holding.
| IHT411 entry | Amount to enter | Main account destination |
|---|---|---|
| Table 1, stock value | Total date-of-death value of the government and municipal holdings | IHT400 box 62 |
| Table 1, interest | Interest due at death | Include in IHT400 box 64 |
| Table 2, investment value | Total value of the listed holdings covered by this table | IHT400 box 63 |
| Table 2, dividend or interest | Amounts due at death in the final column | Include in IHT400 box 64 |
For unit trusts, give the full fund name and type of unit. For an ISA, the form asks for uninvested cash with the shareholding information, but excludes other cash or insurance policies from that entry. Obtain the fund manager’s valuation to identify the components.
When the market was closed
HMRC permits the lower closing price from the last trading day before death or the first trading day after death when the exchange was closed on the date of death. Its guidance allows the choice to be made for each separate shareholding. Keep the dates used with the valuation records.
Official PDF and supporting schedules
The GOV.UK publication supplies the two-page interactive PDF and says to use Adobe Reader. Gather the figures before completing it; the publication warns that a partly completed form cannot be saved through the described workflow.
Submit IHT411 as part of the IHT400 account. Other estate assets have their own schedules: for land and buildings, see IHT405. Use the sources below for the investment classification and valuation rules rather than applying a property valuation method to shares.
Official PDF: IHT411 — Official PDF (assets.publishing.service.gov.uk)