After the IRS accepts an e-filed return, certain supporting documents still travel on paper with Form 8453. For example, an investor whose transaction details are not sent electronically can transmit the permitted Form 8949 statement this way. The transmittal is limited to the documents printed beside its checkboxes.
This article follows the 2026 tax-year form, created on April 29, 2026, and its reverse-side instructions. Use the form for the tax year of the electronically filed return.
Who sends Form 8453 and which documents are excluded?
Taxpayers and electronic return originators use 8453 only when one or more listed paper attachments are required. Do not send Forms W-2, W-2G or 1099-R, and do not mail a duplicate e-filed Form 1040, 1040-SR, 1040-NR or 1040-SS.
The instructions say that if required paper documentation is not among the listed 8453 attachments, the tax return cannot be filed electronically using this route. Confirm document eligibility before choosing e-file rather than adding an unlisted statement to the envelope afterward.
How to complete the identity fields and attachment boxes
Enter the taxpayer’s first name, middle initial, last name and SSN. For a joint return, complete the spouse’s names and SSN in the same order as the names on the return. The address must match the accepted e-filed return: street, apartment, city, state and ZIP, or the foreign country, province/state/county and postal code fields. Do not abbreviate a foreign country name. Use a P.O. box only where the post office does not deliver to the home address.
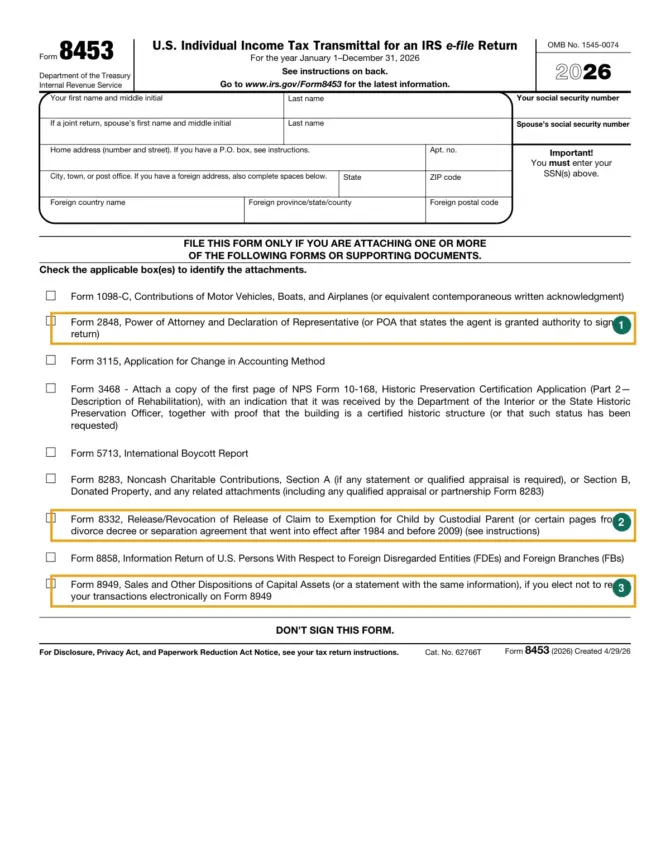
| Attachment checkbox | Document covered by the printed choice |
|---|---|
| 1098-C | Vehicle, boat or airplane contribution form, or equivalent contemporaneous written acknowledgment |
| 2848 | Power of attorney specifically authorizing the agent to sign the return |
| 3115 | Application for a change in accounting method |
| 3468 | First page of NPS Form 10-168 Part 2, showing receipt by the Interior Department or State Historic Preservation Officer, plus proof of certified historic status or a request for it |
| 5713 | International Boycott Report |
| 8283 | Section A when a statement or qualified appraisal is required, or Section B donated property and related attachments, including a required appraisal or partnership Form 8283 |
| 8332 | Custodial-parent release or revocation, or permitted older decree/agreement pages under the conditions below |
| 8858 | Information return for foreign disregarded entities and foreign branches |
| 8949 | Capital-asset transactions, or a statement containing the same information, where the transactions are not reported electronically on Form 8949 |
The illustration marks the 2848, 8332 and 8949 choices. Check every applicable attachment box. The form expressly says not to sign Form 8453; an attachment’s own signature requirements remain part of that attachment.
Special rules for an agent or older divorce agreement
Where an agent signs the electronically transmitted return, attach a power of attorney specifically granting authority to sign. A general permission to obtain information is not the authority described in the 8453 instructions.
The decree alternative to Form 8332 is confined to a divorce decree or separation agreement effective after 1984 and before 2009. It must say that the noncustodial parent can claim the child without a condition such as support payment, that the other parent will not claim the child, and which years are released.
Attach the decree’s cover page with the other parent’s SSN, the pages containing all those terms, and the signature page with the other parent’s signature and agreement date. The required pages must be supplied even if they accompanied an earlier year’s return. If these conditions are not met, do not assume the decree replaces Form 8332.
When to mail the transmittal and where it goes
Mail within three business days after acknowledgment that the IRS accepted the electronic return. For an ERO, the acceptance acknowledgment starts the period. An online filer uses the acceptance acknowledgment from the intermediate service provider and/or transmitter; contact that provider if it has not arrived. Merely pressing Submit is not the acceptance event specified in the instructions.
Send Form 8453 and its permitted attachments to Internal Revenue Service, Attn: Shipping and Receiving, 0254, Receipt and Control Branch, Austin, TX 73344-0254.
Official PDF: Form 8453 — Official PDF (irs.gov)
Keep tax payment separate from the attachments
Do not enclose payment with 8453. The 2026 form’s instructions direct a mailed tax payment to the applicable address on Form 1040-V by April 15, 2027. They recommend electronic payment where available, through Direct Pay, debit or credit card, a digital wallet or the IRS Online Account.
Keep the acceptance acknowledgment, transmittal copy and attachment records together. Ask the ERO or tax preparer to resolve uncertain attachment eligibility before mailing; 8453 is not a general-purpose channel for additional tax papers.