Form AR1100S is the annual Arkansas income tax return of a corporation that has an S election in effect with the IRS. The 2025 version (revision June 24, 2025) has two pages: page 1 carries the header, income and deductions on lines 7 to 27 and the tax and payment lines 28 to 37; page 2 holds Schedule A for multistate apportionment and Schedule D for the capital gains and built-in gains tax. The election generally lets the corporation’s taxable income be taxed to its shareholders, so the return goes in together with an Arkansas Schedule AR K-1 for every shareholder and a copy of the federal return.
Who files Form AR1100S, and who files something else
Arkansas follows the federal election. Ark. Code Ann. § 26-51-409(b) treats a federal Subchapter S election as made for Arkansas too, and for tax years beginning on or after January 1, 2018 a federal S corporation can no longer choose to file in Arkansas as a C corporation. The instructions require Form AR1100S when the corporation is treated as an S corporation by the IRS and the election remains in effect, and it has to file if it is organized or registered in Arkansas or has Arkansas-source income.
Several situations lead somewhere else:
- An S corporation that elected the Arkansas pass-through entity tax does not file the AR1100S. It files the PET return instead and, when paying by check with a paper return, the Form AR1100PTV voucher.
- A qualified subchapter S subsidiary (QSSS) may not file its own Arkansas corporation return. The parent includes it on the parent’s AR1100S, checks filing status 4 and attaches a schedule listing each QSSS by name and FEIN, writing “NO FEIN” where an entity has none.
- A composite return for nonresident shareholders is filed on Form AR1000CR with the Individual Income Tax Section, (501) 682-1100, and composite estimated payments use the AR1000CRES voucher.
Filing the AR1100S does not settle the shareholders’ tax. The instructions say every resident and nonresident shareholder of an S corporation doing business in Arkansas files an individual return: AR1000 for residents, AR1000NR for nonresidents, or inclusion in an AR1000CR composite return. If a nonresident shareholder fails to report and pay, the Director may revoke the corporation’s S election and collect the tax from the corporation (ACA 26-51-409(c)(2)).
What goes in the envelope or the e-file upload
The return itself says to attach a completed copy of the federal return, to attach all AR K-1 forms, and not to staple anything. The 2025 instructions and the form’s line captions add the rest:
- A copy of the federal income tax return (ACA 26-51-409(b)(3)).
- One Schedule AR K-1 for each shareholder.
- Balance sheets as of the beginning and close of the year and a reconciliation of surplus. If the opening balance sheet differs from last year’s closing one, a reconciliation schedule.
- Schedules for line 8 (cost of goods sold, with the inventory method explained), line 11 (other income), line 16 (bad debts) and line 25 (other deductions), and federal Form 4562 for line 20.
- For multistate filers: Form AR1100ADJ for the add and deduct adjustments on Schedule A, a schedule of income directly allocated to Arkansas, and Form AR-718 if special industry or alternative apportionment applies.
- The QSSS schedule for filing status 4, and Form AR1100-WH if line 32 has an amount.
- Any Arkansas extension (Form AR1155), which the instructions say must be attached to the return.
- A copy of any IRS approval to change the accounting method or income year.
Filling in page 1 of the AR1100S
The image marks the parts of page 1 that the sections below refer to: E for the two extension checkboxes, F for the filing status, the line numbers for the lines discussed, and S for the officer’s signature. Lines 7 to 27 have two columns, TOTAL and ARKANSAS; lines 28 to 37 have only the Arkansas column.
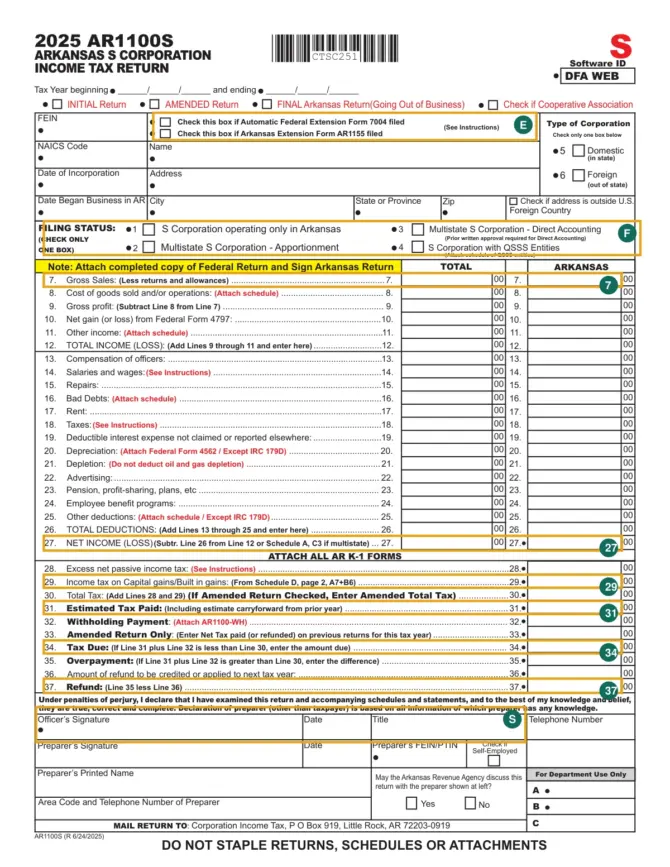
Header boxes
The instructions list the header items that speed up processing: tax year beginning and ending dates; name, address, city, state and ZIP; date of incorporation; FEIN; NAICS code, the same one used on the federal return; date business began in Arkansas; filing status; and type of corporation, domestic (in state) or foreign (out of state), one box only. Above them, check INITIAL, AMENDED or FINAL (going out of business) when it applies, and the cooperative association box if the corporation is one.
The two boxes marked E tell DFA that federal Form 7004 or Arkansas Form AR1155 was filed. No copy of Form 7004 is needed any more.
Filing status (F) takes one box: 1 for an S corporation operating only in Arkansas, 2 for a multistate S corporation using apportionment, 3 for multistate direct accounting, which needs DFA’s prior written approval, and 4 for an S corporation with QSSS entities. A note on Schedule A says that if all the factors in its Section B are 100%, the return should be filed as status 1 and Schedule A is not completed.
Income and deductions, lines 7 to 27
Lines 7 to 27 take trade or business activity only. Rental activity and portfolio income and expenses stay off these lines; the Arkansas portion of them goes to each shareholder on the AR K-1.
| Line | Printed caption | What the 2025 instructions say |
|---|---|---|
| 7 | Gross sales | Gross receipts less returns, allowances and discounts, if the corporation trades or manufactures. |
| 8 | Cost of goods sold and/or operations | Attach a schedule explaining the method; inventories at the start and end of the year, valued at the lower of cost or market. If they do not agree with the balance sheet, explain the difference. |
| 9 | Gross profit | Line 7 minus line 8. |
| 10 | Net gain (or loss) from federal Form 4797 | Gains and losses on trade or business assets, including the corporation’s share from a partnership. Leave out Section 179 recapture. |
| 11 | Other income | Other taxable trade or business income, explained on an attached schedule. |
| 12 | Total income (loss) | Lines 9 through 11. |
| 13 | Compensation of officers | In whatever form paid. |
| 14 | Salaries and wages | Not deducted elsewhere on the return, and not reduced by the federal jobs credit. |
| 15 | Repairs | Incidental repairs for the trade or business. |
| 16 | Bad debts | Specific charge-off method only; attach a schedule. |
| 17 | Rent | Rent for business property in which the corporation has no equity. |
| 18 | Taxes | Taxes paid or accrued in the year, without Arkansas income tax, federal income tax, or assessments for local benefits that raise property value. |
| 19 | Deductible interest | Business interest not reported elsewhere; no interest tied to rental, portfolio or investment income. |
| 20 | Depreciation | No federal bonus depreciation; IRC 167 and 168(a) to (j) as of January 1, 2019. No 179D deduction. Section 179 is discussed below. |
| 21 | Depletion | Federal depletion as of January 1, 2019; oil and gas wells follow IRC 613A as of that date. The form prints “Do not deduct oil and gas depletion” on this line. |
| 22 | Advertising | Business advertising. |
| 23 | Pension, profit-sharing plans, etc. | Amounts for those plans. |
| 24 | Employee benefit programs | Benefit programs for the business. |
| 25 | Other deductions | Business deductions without their own line; attach a schedule. The 179D energy efficient buildings deduction is not allowed. |
| 26 | Total deductions | Lines 13 through 25. |
| 27 | Net income (loss) | Line 12 minus line 26. A multistate filer enters Schedule A, Part C, line 3 in the Arkansas column. |
Tax and payments, lines 28 to 37
| Line | Printed caption | Where the amount comes from |
|---|---|---|
| 28 | Excess net passive income tax | Line 11 of the worksheet in the instructions (see the next section). Does not apply to a corporation that has always been an S corporation. |
| 29 | Income tax on capital gains/built-in gains | Schedule D, page 2: Part A line 7 plus Part B line 6. |
| 30 | Total tax | Lines 28 and 29. On an amended return, the amended total tax. |
| 31 | Estimated tax paid | Including any estimate carried forward from the prior year. |
| 32 | Withholding payment | Only when withholding is to be applied to the S corporation’s return and not to the shareholders. Attach AR1100-WH. |
| 33 | Amended return only | Net tax paid, or refunded, on earlier returns for the same tax year. |
| 34 | Tax due | When line 31 plus line 32 is less than line 30. |
| 35 | Overpayment | When line 31 plus line 32 is more than line 30, the difference. |
| 36 | Credit to next year | The part of the overpayment to apply to next year’s tax. |
| 37 | Refund | Line 35 minus line 36. |
The officer’s signature (S) is required. Under ACA 26-51-804(b) the president, vice-president, treasurer or another principal officer certifies the return; a receiver, trustee in bankruptcy or assignee running the business signs instead. A paid preparer signs below, gives a FEIN or PTIN, and the corporation answers whether DFA may discuss the return with that preparer.
Line 28 and Schedule D: the taxes the corporation pays itself
The S corporation pays Arkansas tax at the entity level only through lines 28 and 29.
Line 28 can apply only to a corporation that has C corporation earnings and profits at the close of the year, passive investment income above 25% of gross receipts and taxable income at year end. The worksheet in the instructions starts with Arkansas gross receipts (line 1), passive investment income (line 2) and 25% of line 1 (line 3); if line 2 is less than line 3, there is no tax. Otherwise lines 4 to 10 work out the excess net passive income, and line 11 is 4.3% of line 10. Taxable income on worksheet line 9 follows IRC 1374(d) and is figured on lines 9 to 27 of page 1 or on Schedule A of Form AR1100CT; that AR1100CT computation is attached with the worksheet.
Schedule D on page 2 has two parts. The instructions say a corporation whose Arkansas net capital gain is $25,000 or less does not owe the capital gains tax, and $25,000 is printed as the statutory minimum on Part A, line 4.
- Part A, for elections made before 1987: taxable income and the tax on it (lines 1 and 2), net long-term capital gain less net short-term capital loss (line 3), the $25,000 minimum (line 4), 4.3% of the remainder (lines 5 and 6), and the smaller of line 2 or line 6 on line 7.
- Part B, for elections made after December 31, 1986: taxable income (line 1), recognized built-in gain (line 2), the smaller of the two (line 3), the Section 1374(b)(2) deduction (line 4), and 4.3% of what is left on line 6.
Multistate corporations multiply Part A line 3 and Part B line 2 by the Schedule A apportionment percentage. Both parts send the reader to the IRS instructions to decide whether the corporation is liable at all.
Schedule A for a multistate S corporation
A multistate S corporation that apportions its income completes Schedule A on page 2. Part A starts from page 1, line 27, Total column, then adds and deducts the federal to Arkansas adjustments from Form AR1100ADJ (lines 2 and 3) to reach total apportionable income on line 4. Examples in the instructions: Arkansas income taxes deducted, federal bonus depreciation and partnership losses are added; Arkansas depreciation, Arkansas charitable contributions and partnership income are deducted.
Part B is a single sales factor, required for all multistate taxpayers since tax years beginning in 2021 unless an alternative method is required or approved in advance. Column A is Arkansas, column B is everywhere, and column C is A divided by B, carried to six decimal places (the instructions’ example is 26.123456%). Receipts are gross, not net.
- Lines 1a and 1b: destination sales to Arkansas buyers, shipped from inside or outside the state.
- Line 1c: sales shipped from Arkansas to a buyer in a state where the corporation is not taxable. The throwback is being phased out under Act 485 of 2023, and for 2025 the instructions put 71.42% of these sales in Arkansas.
- Lines 3d to 3j: capital and ordinary gains, dividends, interest, rents, royalties, services, and other business gross receipts with a schedule. Line 3k totals everything.
- Line 4: check the box and carry the percentage from Form AR-718, line 5, column C, when special industry or alternative apportionment applies. The instructions list construction contractors, broadcasters, publishers, airlines, bus and trucking companies, pipelines, railroads and private railcar operators.
- Line 5: the Arkansas percentage, from line 3k column C or from AR-718.
Part C multiplies Part A line 4 by Part B line 5 (line 1), adds income directly allocated to Arkansas (line 2) and gives total income taxable to Arkansas on line 3, which is also entered on page 1, line 27, Arkansas column. Partnership income is handled in two steps: it is deducted on Part A line 3 (a partnership loss is added on line 2), and the Arkansas share from the partnership’s AR K-1 goes on Part C line 2, with Forms AR K-1 and, if withholding is claimed, AR1099PT attached.
Depreciation and Section 179: where the 2025 documents differ
Arkansas does not follow federal bonus depreciation, and the AR1100REC instructions add that the provisions of P.L. 119-21, the One Big Beautiful Bill Act, have not been adopted. When the Arkansas Section 179 deduction differs from the federal one, the booklet asks for a Form 4562 schedule showing the Arkansas computation. Section 179 carryforwards from earlier years count only if Arkansas depreciation was not claimed in those years.
Two DFA documents disagree on the details. The line 20 instructions in the 2025 S corporation booklet give a Section 179 limit of $1,220,000 with the phaseout starting at $3,050,000 for tax years beginning on or after January 1, 2024, and say Form AR1100REC must be completed by any taxpayer filing a corporation income tax or pass-through entity tax return that claims Section 179. The same booklet’s reminders on page 5, and the AR1100REC instructions revised September 19, 2025 under “Current limitations (2025)”, give $1,250,000 and $3,130,000. The AR1100REC instructions also say S corporations are not required to complete AR1100REC but may attach it, and that an S corporation reports its Section 179 expense on AR K-1, line 13a. Until DFA reconciles the two, a corporation claiming Section 179 can ask the Corporation Income Tax Section at (501) 682-4775 or corporate.income@dfa.arkansas.gov which limit and attachment apply.
The shareholders’ Schedule AR K-1
The AR K-1 is required with the return, one for each shareholder. Items A and B identify the corporation, items C and D the shareholder, item E asks whether the shareholder is an Arkansas resident (and the state of residence if not; it may not be left blank), item F gives the percentage of stock owned, and item H the Arkansas apportionment percentage, which should match the return. Boxes 1 to 20 carry the shareholder’s share of each item, including the Section 179 deduction in box 13 and Arkansas withholding or other payments in box 20. The booklet says each amount is the Arkansas total for the item multiplied by the shareholder’s ownership percentage.
What changed for 2025
The “What’s New for 2025” page of the S corporation instructions lists these acts:
- Act 696 of 2025 exempts USDA relief payments under the American Relief Act of 2025 from income tax.
- Act 701 of 2025 amends the Wood Energy Products and Forest Tax Credit.
- Act 838 of 2025 amends the Natural State Opportunity Zone incentive.
- Act 881 of 2025 creates a credit for relocating a corporate headquarters to Arkansas, and Act 882 a credit for modernization and automation.
- Act 719 of 2025 brings market-based sourcing for services and intangibles, apportionable income in place of business income, alternative apportionment rules on the MTC model, and a $250,000 receipts nexus threshold. These take effect for tax years beginning on or after January 1, 2026, so the 2025 Schedule A still uses the current rules.
The 2025 AR K-1 instructions also note that the column order has changed: column (a) now holds the full amounts for Arkansas residents and column (b) the amounts allocated or apportioned to Arkansas for nonresidents and part-year residents.
Due date, extensions and payment
The AR1100S is due on or before the 15th day of the fourth month after the tax year closes: April 15, 2026 for a calendar 2025 return. With an automatic federal extension on Form 7004, the Arkansas return is due on the federal extended due date, and the box at the top of the return is checked. Form AR1155 requests 180 days from the original Arkansas due date, or 60 days beyond the federal extended date; the Form AR1155 guide covers both choices.
No extension moves the payment date. Tax not paid by the original due date carries interest at 10% a year, figured at a daily rate of .00027397, and a failure to pay penalty. The 2025 instructions list these penalties:
- Failure to file on time, and failure to pay on time: 5% per month each, up to 35%.
- Underestimate: 10% of the underestimated amount.
- Failure to file a return, and failure to comply: $50 each.
- Failure to make a required EFT payment: 5% of the tax due.
- Incomplete electronic payment: 10% of the draft or $20, whichever is greater.
A balance due on line 34 is paid by check or money order payable to “Department of Finance and Administration”, with the corporation’s FEIN written on it and attached to the return, or online through ATAP. Payments sent with the return cannot be made by EFT. A check for an e-filed return, or one mailed with a paper AR1100S, travels with the Form AR1100CTV voucher, whose instructions name the AR1100S. Estimated tax is required from any taxpayer who can reasonably expect to owe more than $1,000.
Amended returns and IRS changes
An amended return uses the same form with the AMENDED box checked, the amended total tax on line 30 and the tax paid or refunded so far on line 33. A federal Revenue Agent Report must be reported to Arkansas within 180 days of receipt, and an amended return filed on or after the 181st day after the IRS notice cannot produce a refund (ACA 26-18-306(b)(3)(B)). If an RAR is not disclosed, the assessment period stays open for three years.
Getting the 2025 AR1100S and filing it
The 2025 AR1100S, the 2025 Subchapter S Corporation Income Tax Instructions, the AR K-1, AR1100ADJ and AR-718 are posted on DFA’s Small Business Corporate (Sub-S) page, dated January 8, 2026.
Arkansas e-file and ATAP both take the return. ATAP also accepts an XML return upload; the federal return and other schedules are attached to the ATAP filing or mailed separately on CD, in PDF or on paper. Under Act 143 of 2021, a tax practitioner who files federal returns electronically must also file Arkansas returns electronically unless DFA waives it for undue hardship. A paper return goes to the address printed on the form:
Corporation Income Tax
P.O. Box 919
Little Rock, AR 72203-0919
Walk-in help is at 1816 W. 7th Street, Room 2250, Ledbetter Building, Little Rock, Monday to Friday 8:00 a.m. to 5:00 p.m., arriving before 4:00 p.m.; staff answer questions but do not prepare returns. This guide describes the form and DFA’s published instructions; for questions about built-in gains, apportionment or a revoked election, a tax adviser or DFA can look at the corporation’s own facts.
Questions about the AR1100S
Can a federal S corporation file Form AR1100CT in Arkansas instead?
For tax years beginning on or after January 1, 2018, the instructions say a federal S corporation must also file as an Arkansas S corporation. In the AR1100S instructions, Form AR1100CT comes up only as the way to figure taxable income for the line 28 worksheet.
Does a QSSS file its own Arkansas return?
It may not. The parent files one AR1100S, checks filing status 4 and attaches a schedule of every QSSS with its FEIN, or “NO FEIN”.
Is the federal return really required with an e-filed AR1100S?
The statute and the form require it. With an ATAP filing, the instructions allow the federal return to be attached online or mailed separately to the Corporation Income Tax Section.
Official sources
- Arkansas DFA, 2025 AR1100S, Arkansas S Corporation Income Tax Return (R 6/24/2025)
- Arkansas DFA, 2025 Sub-Chapter S Corporation Income Tax Instructions
- Arkansas DFA, Small Business Corporate (Sub-S) forms page
- Arkansas DFA, 2025 Schedule AR K-1 and AR K-1 instructions
- Arkansas DFA, AR1100ADJ instructions (R 10/10/2025)
- Arkansas DFA, AR-718 instructions, 2025
- Arkansas DFA, AR1100REC instructions (R 9/19/2025)
- Arkansas DFA, AR1100CTV Corporation Income Tax Payment Voucher, 2025