Kentucky Schedule A (Form 740) is where a full-year Kentucky resident lists itemized deductions instead of taking the $3,270 standard deduction. The total from line 15 goes to line 10 of Form 740, and Kentucky taxes what is left at 4 percent. The 2025 schedule is numbered 42A740-A (10-25), and the Department of Revenue’s forms library tags it as the current version.
The Kentucky list is shorter than the federal one. Mortgage interest, investment interest, charitable gifts, gambling losses and four narrow miscellaneous items are all that the schedule has room for. State and local income taxes, real estate and personal property taxes, medical and dental expenses and casualty and theft losses are deductible on a federal Schedule A but are listed as nondeductible in the Federal/Kentucky differences chart of the 2025 Form 740 instructions. Someone who itemized federally because of a large property tax bill can therefore end up below $3,270 on the Kentucky schedule.
Who uses Schedule A (740) and who takes the standard deduction
The schedule is printed “Full-Year Residents Only” and “Enclose with Form 740.” A part-year resident or nonresident filing Form 740-NP uses a separate 2025 Schedule A for Form 740-NP, which numbers its deduction lines 1 to 14 and splits the total between spouses on its own lines 15 to 18.
Kentucky does not tie the choice to the federal return. The instructions say you may itemize for Kentucky even if you take the standard deduction on your federal return, and that, generally, itemizing helps if your deductions exceed $3,270. Three other rules from the instructions decide how a household uses the schedule:
- If one spouse itemizes, the other must also itemize.
- Amounts already deducted on Schedule C, E or F or on Kentucky Schedule M are not entered again on Schedule A.
- Married couples who filed one federal joint return but file separately or on a combined Kentucky return can either file a separate Schedule A for each spouse, or file one Schedule A and split the total with lines 16 to 20.
How to fill out Schedule A (740), line by line
Page 1 is the whole schedule; pages 2 to 4 are its instructions. The numbers in the image match the line numbers on the form.
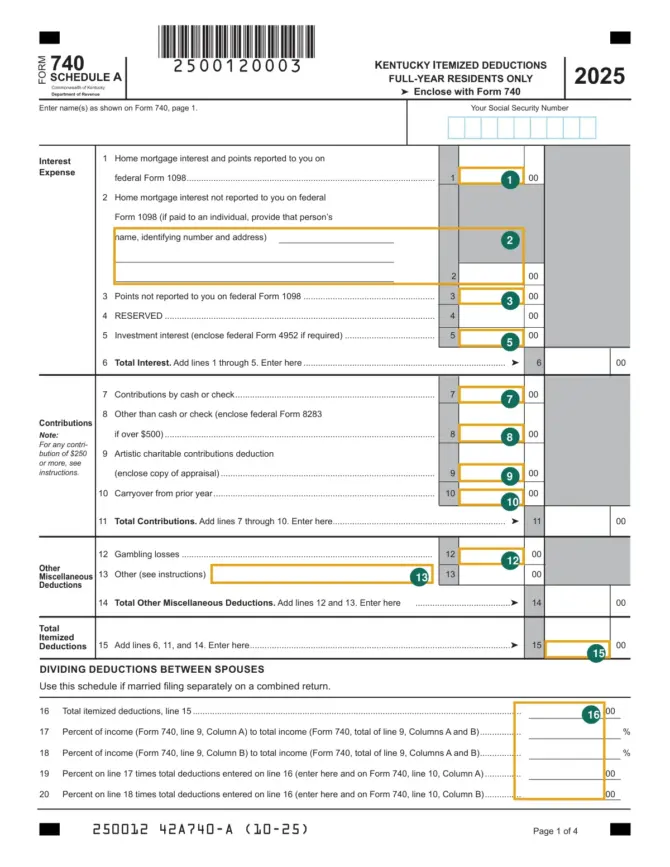
| Line | What goes on it | Where the figure comes from |
|---|---|---|
| 1 | Home mortgage interest and points, including seller-paid points | Federal Form 1098 from the lender |
| 2 | Home mortgage interest not reported on Form 1098 | Your payment records; write the payee’s name, identifying number and address on the lines provided |
| 3 | Points not reported on Form 1098 | Closing statement; see the three conditions below |
| 4 | Reserved | Leave blank |
| 5 | Investment interest | Federal Form 4952, enclosed when required |
| 6 | Total interest | Lines 1 through 5 added |
| 7 | Gifts by cash or check, including out-of-pocket volunteer costs | Receipts, cancelled checks, letters from the charity |
| 8 | Gifts of property at fair market value | Federal Form 8283 if the total is over $500 |
| 9 | Artistic charitable contributions | Appraisal by a qualified independent appraiser, copy enclosed |
| 10 | Contribution carryover from a prior year | Your earlier return; federal Publication 526 explains the computation |
| 11 | Total contributions | Lines 7 through 10 added |
| 12 | Gambling losses | Limited to winnings reported on Form 1040 or 1040-SR, Schedule 1, line 8(b) |
| 13 | Other miscellaneous deductions | Only the four items listed in the instructions, with type and amount written in |
| 14 | Total other miscellaneous deductions | Lines 12 and 13 added |
| 15 | Total itemized deductions | Lines 6, 11 and 14 added; carried to Form 740, line 10 |
| 16 to 20 | Dividing the deductions between spouses | Form 740, line 9, Columns A and B |
Interest, lines 1 to 6
Only home mortgage interest and investment interest have a line. The instructions name interest Kentucky does not allow: credit and charge card interest, interest on a life insurance loan, an automobile or other consumer loan, delinquent taxes, or a personal note held by a bank or individual. Interest on someone else’s debt that you were not legally liable for, interest on a gambling debt, and interest on money borrowed to buy tax-exempt securities or single premium life insurance are also excluded. Business interest belongs on the business schedule.
Line 2 is for a mortgage held by a person, such as a seller who financed the sale of the house. The schedule asks for that person’s name, identifying number and address on the three blank lines next to it.
Points on line 3 are normally deducted over the life of the mortgage. The instructions allow the full amount in the year paid only when all three conditions hold: the loan bought, built or improved your main home and was secured by it; the points were not more than usual in the area and were figured as a percentage of the loan; and, for a purchase or construction loan, the funds you provided at closing (down payment, escrow deposits, earnest money, other amounts paid at closing, but not borrowed money) were at least equal to the points. For an improvement loan, the points must be paid with funds other than those from the lender. A buyer can deduct seller-paid points on a main-home purchase but must reduce the home’s basis by them; the seller treats them as a selling expense. The instructions add that this generally does not apply to points on a refinance, and refer to federal Publication 936.
Line 5 needs federal Form 4952 unless all three exceptions apply: investment interest no larger than investment income from interest and ordinary dividends, no other deductible investment expenses, and no disallowed investment interest carried over from 2024.
Contributions, lines 7 to 11
Qualifying recipients are religious, charitable, educational, scientific and literary organizations, groups that work to prevent cruelty to children or animals, veterans’ and certain cultural groups, nonprofit schools and hospitals, and governments when the gift is for public purposes only. If you received something back, such as a dinner at a fundraiser, only the part of the gift above the value of that benefit counts.
Line 7 includes out-of-pocket costs of volunteer work. For driving to and from the volunteer work, the instructions allow 14 cents a mile or the actual cost of gas and oil, plus parking and tolls under either method. Line 8 takes donated property such as used clothing or furniture at fair market value on the day you gave it. Over $500 of property gifts in total requires federal Form 8283; over $5,000 may also require appraisals. A leasehold interest in property given to a charity to provide temporary housing for the homeless is also reported on line 8, with Kentucky Schedule HH enclosed.
Line 9 is a Kentucky deduction with no federal match. A writer, composer, artist or scholar who donates a literary, musical, artistic or scholarly composition, letter or memorandum they created can deduct its fair market value on the date of the gift, up to their artistic adjusted gross income for the year. The work must have been created by the taxpayer’s own effort at least one year before the gift, not as part of duties as a government officer or employee; it must be appraised in writing by a qualified independent appraiser within one year of the gift, with the appraisal enclosed; and it must go to a qualifying organization. A taxpayer who does not itemize can claim the same contribution as an “other subtraction” on Schedule M, line 14, according to the Schedule M instructions in the same packet.
Several cases send you to federal Publication 526 for special rules, among them total gifts over 60 percent of Kentucky adjusted gross income, cash gifts over 30 percent, capital gain property gifts to certain organizations over 20 percent, partial interests, and gifts for which you expect a state or local tax credit. When a Kentucky net operating loss deduction is present, the 60 percent test uses Kentucky adjusted gross income before that deduction: Form 740, line 7, minus Schedule M, line 15.
The instructions list what is not a contribution: political contributions, club and lodge dues, raffle, bingo and lottery tickets, tuition, the value of your time or of blood donated, travel with a significant element of personal pleasure, and gifts to individuals, foreign organizations, for-profit groups, lobbying groups, civic leagues, social and sports clubs, labor unions and chambers of commerce. A contribution that earns a state or local tax credit of more than 15 percent of the gift is also on the list.
That last point and the Endow Kentucky credit do not line up neatly. The Schedule A instructions in the 2025 Form 740 packet list a contribution with a state or local credit above 15 percent as not deductible. The line 18 instructions for Form 740 in the same packet describe the Endow Kentucky credit as 20 percent of an endowment gift and say you “may need to reduce” the Schedule A contribution by the amount of the credit. Neither passage says which treatment applies to an Endow Kentucky gift. If you claim that credit, ask the Department’s Individual Income Tax section at (502) 564-4581 before entering the gift on line 7 or 8.
Gambling losses and other deductions, lines 12 to 15
Line 12 cannot exceed the gambling winnings reported on Form 1040 or 1040-SR, Schedule 1, line 8(b). The 2025 instructions also flag a side effect: on Worksheet A for the credit for taxes paid to another state, gambling losses claimed on Schedule A are added back, so the credit can shrink or disappear.
Line 13 accepts only four expenses: federal estate tax on income in respect of a decedent, amortizable bond premium on bonds acquired before October 23, 1986, repayment of more than $3,000 under a claim of right (federal Publication 525), and unrecovered investment in a pension. Write the type and amount of each in the space after “Other” and put one total on line 13. Federal Publication 529 covers these items.
Line 15 adds lines 6, 11 and 14. The total goes to Form 740, line 10, unless spouses split it on lines 16 to 20.
Splitting the total between spouses, lines 16 to 20
Lines 16 to 20 are for spouses filing separately on a combined return who use one Schedule A. Line 16 repeats line 15. Line 17 is Column A income from Form 740, line 9, as a percentage of Columns A and B together; line 18 is the same for Column B. Lines 19 and 20 apply those percentages to line 16, and the two results go on Form 740, line 10, Columns A and B. If one spouse is not required to file a Kentucky return, the instructions allow the same income-based split or separate schedules.
What changed for 2025
The “What’s New” page of the 2025 Form 740 instructions has three items that affect itemizers:
- The standard deduction you compare against is $3,270 for 2025.
- HB 775 moved Kentucky’s Internal Revenue Code reference date from December 31, 2023 to December 31, 2024.
- Federal changes enacted after that date do not apply to Kentucky returns; the instructions name qualified tips, overtime income and car loan interest as not deductible on the Kentucky return. Car loan interest was already outside the interest lines of Schedule A.
Records to keep and documents to enclose
- Enclose with Form 740: federal Form 4952 when line 5 requires it, federal Form 8283 when property gifts exceed $500, the appraisal for an artistic contribution on line 9, and Schedule HH for a leasehold gift.
- Keep, but do not send: receipts, cancelled checks or other written records showing the charity’s name, the date and the amount of each gift.
- For each separate gift of $250 or more, written acknowledgment from the charity showing the date and amount, in addition to proof of payment. The instructions say to keep it in your files and not send it with the return.
- For donated property, a record of the charity’s name and address, the date and place of the gift, a description of the property, how you figured its value (a signed copy of any appraisal), and any conditions attached to the gift.
Filing Schedule A with Form 740
The schedule travels with Form 740, whether filed electronically or on paper. The Department’s Individual Income Tax page lists KY File, its free fillable-forms portal, as one electronic option; it does basic math and error checking but asks you to have your federal forms done first. For calendar year 2025, the return must be postmarked or submitted electronically by April 15, 2026 to avoid penalties and interest. Paper returns go to one of two addresses:
| Return | Address |
|---|---|
| Refund or no payment | Kentucky Department of Revenue, Frankfort, KY 40618-0006 |
| Payment enclosed | Kentucky Department of Revenue, Frankfort, KY 40619-0008 |
| Overnight delivery | Kentucky Department of Revenue, 501 High Street, Frankfort, KY 40601 |
If you find a deduction you missed after filing, the 2025 instructions allow a refund through an amended return filed within four years of the original due date; for 2017 and later years, that is Form 740 with the amended box checked and a corrected Schedule A. The Individual Income Tax page gives 20 to 24 weeks for amended returns to be processed. Questions go to the Individual Income Tax section at (502) 564-4581.
Official PDF: Schedule A (740) — Official PDF (revenue.ky.gov)
Questions about Kentucky itemized deductions
Can I deduct my property taxes on the Kentucky Schedule A?
Real estate and personal property taxes are listed as nondeductible for Kentucky in the differences chart of the 2025 Form 740 instructions, and Schedule A has no line for them. State and local income taxes are treated the same way.
I took the standard deduction on my federal return. Can I still itemize in Kentucky?
The Schedule A instructions allow it. Kentucky lets you itemize even if you did not itemize for federal purposes; your spouse must then itemize as well.
Are medical bills deductible in Kentucky?
Medical and dental expenses appear as nondeductible for Kentucky in the same chart, so they stay off Schedule A even when they were deducted federally.
Do I send the charity’s receipt with my return?
The instructions say to keep the written acknowledgment for gifts of $250 or more in your files and not send it. What does get enclosed is Form 8283 for property gifts over $500 and the appraisal for a line 9 artistic contribution.
Official sources
- Kentucky Department of Revenue, Schedule A (Form 740), Kentucky Itemized Deductions, Full-Year Residents Only, 2025, 42A740-A (10-25)
- Kentucky Department of Revenue, 2025 Kentucky Individual Income Tax Forms instruction packet, 42A740(PKT) (10-25)
- Kentucky Department of Revenue, Form 740 (2025), 42A740 (10-25)
- Kentucky Department of Revenue, Schedule A (Form 740-NP), Nonresidents or Part-Year Residents Only, 2025
- Kentucky Department of Revenue, Individual Income Tax
- Kentucky Department of Revenue, Forms