Kentucky Form PTE-WH reports a nonresident owner’s distributive share income and Kentucky income tax withheld or paid by a pass-through entity. The entity prepares a separate form for each covered owner, attaches it to Form 740NP-WH and gives the owner two copies.
Who prepares a 2025 PTE-WH?
The 2025 form, 40A200 (10-25), covers nonresident individual, estate or trust partners, members and shareholders doing business in Kentucky only through their ownership interest. The entity completes the form or an approved substitute. The 2025 NRWH instructions, page 2, explain that withholding covers distributed and undistributed distributive share income.
The same packet excludes nonresident corporate owners from this withholding requirement and says a partnership or S corporation owner is not an individual subject to withholding. It treats a single-member LLC as a pass-through entity for Kentucky purposes. Publicly traded partnerships described in the packet’s cited provisions are excluded from the Form 740NP-WH requirement. If the entity files Form 740-PTET for 2025, the packet says Form 740NP-WH is not required.
PTE-WH identifies each owner within the NRWH filing. Form 740NP-WH is the entity’s combined withholding report, with the payment and overpayment calculation. Completing the owner sheet does not transmit either the report or its payment.
What changed on PTE-WH for 2025?
The 2025 PTE instructions, page 2, list two changes to PTE-WH: line 7 is now labeled Tax Liability, and line 8 is reserved for future use. The NRWH packet directs business tax credits to Schedule TCS or Schedule ITC and the applicable tax return. Do not enter an owner’s credit on the reserved PTE-WH line.
Entering the year and identification fields
The marked form identifies lines 1 through 5. The entity and owner have separate taxpayer numbers and addresses; use each in its own section.
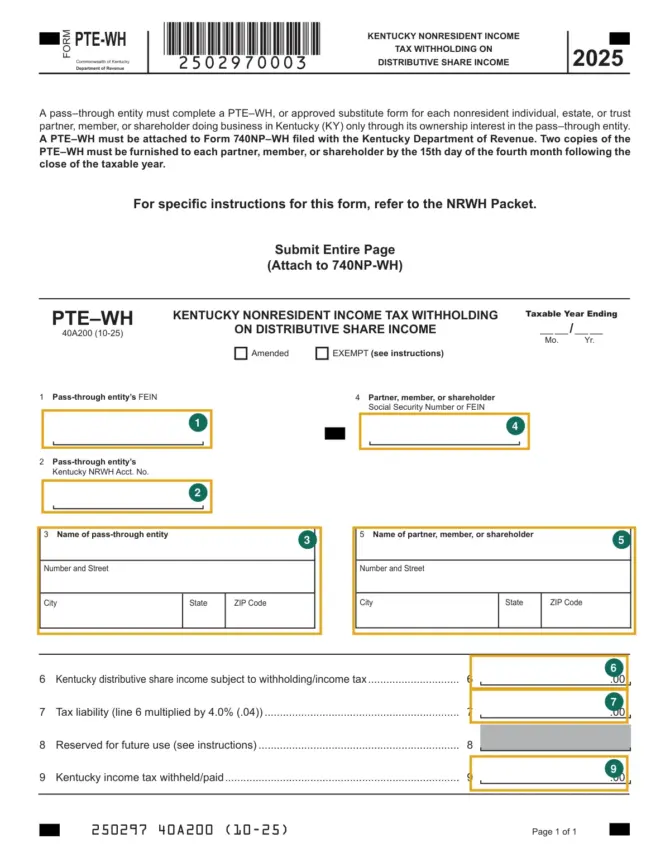
| Field | What to enter |
|---|---|
| Taxable year ending | The month and two-digit year in the Mo./Yr. spaces. |
| Amended | Check this box when correcting a previously filed return. |
| 1 | The pass-through entity’s federal employer identification number. |
| 2 | The entity’s Kentucky Nonresident Income Tax Withholding account number. If it is unknown, contact Registration at (502) 564-3306 before submitting the form. |
| 3 | The entity’s name, number and street, city, state and ZIP code. |
| 4 | The partner’s, member’s or shareholder’s Social Security number or FEIN. |
| 5 | The owner’s name, number and street, city, state and ZIP code. |
The owner sheet has no signature field. Line 2 requires the NRWH account number.
When to check EXEMPT and skip lines 7 to 9
An exempt owner still needs a PTE-WH attached to Form 740NP-WH. Check EXEMPT, complete the identification and line 6, then leave lines 7 through 9 blank. The NRWH packet, page 3, says an individual owner claiming exemption under KRS 141.206(6)(a) must have filed an appropriate Form 740-NP or Form 741 for the prior year with the department.
The 2025 PTE instructions, page 7, also list an owner exempt under KRS 141.020, an individual owner of a qualified investment partnership under KRS 141.206(14), and a partner or member that is itself a pass-through entity among the withholding exceptions. Check the applicable statutory condition before treating an owner as exempt. The entity’s status alone does not establish that every nonresident owner qualifies for the prior-return exemption.
Completing income, tax liability and withholding
Line 6 takes the owner’s Kentucky distributive share income subject to withholding or income tax. The PTE instructions, page 7, say this includes the passed-through income and deductions used in computing Kentucky adjusted gross income, including interest, dividends, capital gains or losses, guaranteed payments and rents. Reconcile the Kentucky share to the entity’s allocation and apportionment records.
| Line | Entry for a nonexempt owner |
|---|---|
| 6 | Kentucky distributive share income. |
| 7 | Line 6 multiplied by 4.0% (.04), the rate printed on the 2025 form. |
| 8 | Leave the reserved line unused. Claim eligible credits on the schedules and return specified by the NRWH packet. |
| 9 | Kentucky income tax withheld or paid for that owner. |
For example, a nonexempt owner’s line 6 amount of $25,000 produces $1,000 on line 7. This arithmetic example does not determine that owner’s Kentucky income or any exemption. Line 9 reports withholding or payment; check it against the entity’s records. The NRWH packet, page 2, requires total income tax withheld on the enclosed PTE-WH forms to equal Form 740NP-WH line 8.
If the nonresident individual’s, estate’s or trust’s only Kentucky source income is distributive share income from pass-through entities, the packet says withholding on PTE-WH and payment by the entities satisfy the Kentucky filing requirement. The PTE instructions explain that an owner may file Form 740-NP or Form 741 to take applicable credits and deductions. Other Kentucky income requires a separate filing review.
Official PDF, attachment and owner-copy deadline
Download the official one-page PTE-WH and submit the entire page as an attachment to Form 740NP-WH. Give each partner, member or shareholder two copies by the 15th day of the fourth month after the taxable year closes. The PTE instructions give the same general deadline for filing and paying Form 740NP-WH with the owner sheets.
The NRWH packet, page 2, requires electronic filing and payment for the listed entities with federal gross receipts of $1 million or more for tax years beginning on or after October 1, 2021. A filer subject to that requirement needs an approved Form 8948 (K-C) waiver before paper filing and must attach the approval. Consult the software provider about supported forms.
The PTE instructions, page 2, say eligible filers can submit Form 740NP-WH through MyTaxes. A return with more than 30 PTE-WH attachments must be filed electronically through an approved software vendor.
For payment, the packet’s page 4 directs filers to MyTaxes.ky.gov. If electronic payment is impossible, it specifies Form 740NPWH-V with a paper check and gives Kentucky Department of Revenue, Frankfort, Kentucky 40619-0006 as the payment destination. This is a payment-voucher instruction; PTE-WH remains an attachment to the entity report. Use the department’s pass-through entities page and its contact number, (502) 564-8139, for help with the filing route.
Estimated payments are a separate entity obligation. Page 4 of the NRWH packet covers the $500 expected owner-liability threshold, short-period exception and installment dates. Preparing the annual PTE-WH does not replace those payments.