SA400 puts a new partnership on HMRC’s Self Assessment records, so that it gets its own Unique Taxpayer Reference and the partnership return can be issued to it. The nominated partner fills it in and signs it. The paper version on GOV.UK is two pages long and carries the edition mark HMRC 08/23 at the foot of each page.
Does your partnership need SA400?
Page 1 of the form names two groups: ordinary partnerships, and Limited Liability Partnerships (LLPs) and Limited Partnerships (LPs) that registered with Companies House before 25 October 2010. An LLP or LP registered on or after that date does not fill in SA400, because its Companies House registration also registers it for Self Assessment. For an LLP that still has to be incorporated on paper, the Companies House step is covered in our guide to LL IN01: registering an LLP on paper.
The person completing the form has to be the nominated partner, meaning the partner the partnership has chosen to receive and submit its partnership returns. SA400 registers the business only. The nominated partner and every other partner also register themselves: an individual on SA401, and a company, trust or another partnership on SA402. This still applies to a partner who already sends a personal tax return.
Online registration or the paper form
HMRC’s SA400 page lists the online service first. To use it, the nominated partner needs a Government Gateway user ID and password (one can be created during registration) and either their Unique Taxpayer Reference or a VAT reference found in the business tax account.
Anyone who cannot register online can post SA400 instead. GOV.UK gives three ways to prepare it:
- complete the online version of the form, then print it, bearing in mind that this version cannot save your progress
- download the PDF, save it, complete it on screen in the latest free Adobe Reader and print it
- print the blank PDF and fill it in by hand
All three end with a printed form in the post. HMRC warns that the PDF may not work if it is opened inside a web browser, which is why the page asks you to save it to your computer first.
Filling in SA400 questions 1 to 10
The first ten questions sit under “About the partnership” on page 1. GOV.UK asks you to have two dates ready before you start: when the partnership began and its accounting date. These go into questions 7 and 10, each written as DD MM YYYY.
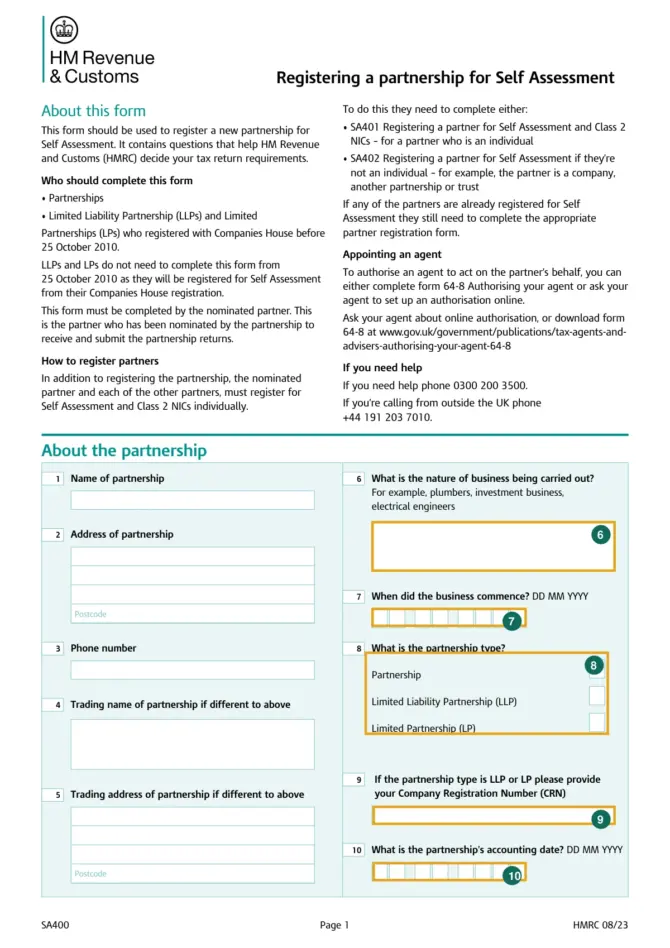
| Question | What to write | Points to check |
|---|---|---|
| 1 | Name of the partnership | Always |
| 2 and 3 | Address with postcode, and a phone number | The partnership’s details, not a partner’s |
| 4 and 5 | Trading name and trading address | Only if they differ from questions 1 and 2 |
| 6 | Nature of the business | The form’s examples: plumbers, investment business, electrical engineers |
| 7 | Date the business commenced | Day, month and four-digit year |
| 8 | Partnership type | One box: Partnership, LLP or LP |
| 9 | Company Registration Number (CRN) | Only for an LLP or LP |
| 10 | Accounting date | Day, month and four-digit year |
Question 9 applies only when question 8 is LLP or LP. Because page 1 limits SA400 to LLPs and LPs registered with Companies House before 25 October 2010, the CRN entered here is the one from that earlier registration.
The nominated partner’s details and the declaration
Page 2 continues with three questions about the nominated partner. Question 11 is their name and question 12 their correspondence address with postcode. Question 13 asks for their own UTR if they are already registered for Self Assessment; it is the 10-digit reference printed on HMRC Self Assessment letters. A note under question 13 repeats that the nominated partner must still register personally for Self Assessment and Class 2 National Insurance on SA401.
The declaration is signed and dated by the nominated partner, with their name written above the signature. By signing, they confirm the answers are complete and correct to the best of their knowledge and belief, and agree to tell HMRC straightaway if their circumstances change in a way that affects those answers.
Where to post SA400 and what can go with it
Download the SA400 PDF from GOV.UK. The completed form goes to:
HM Revenue and Customs
National Insurance Contributions and Employer Office
BX9 1AN
The envelope can also hold the partners’ completed SA401 and SA402 forms and any form 64-8 Authorising your agent. Page 2 has three count boxes, one each for 64-8, SA401 and SA402, where you enter how many of that form are enclosed. The form’s own example: a 64-8 for the partnership and for two partners means writing 3 in the 64-8 box. Nothing else should be attached.
Form 64-8 is one of two ways to give an agent authority. The other is an authorisation the agent sets up online. HMRC’s helpline for SA400 is 0300 200 3500, or +44 191 203 7010 from outside the UK.
Registration deadline and what follows
GOV.UK’s guide to setting up a business partnership says the partnership must be registered by 5 October in the business’s second tax year, or a penalty may be charged. Its example: a partnership started during the 2024 to 2025 tax year had to register before 5 October 2025. On the same rule, one started in the 2026 to 2027 tax year has until 5 October 2027.
HMRC usually replies within 15 days of receiving the form, and can take longer in busy periods. A partnership registered online may see its UTR sooner in the HMRC app or its business tax account. If nothing has arrived after 3 weeks, GOV.UK has a checker showing when to expect a reply.
Registration leads to two kinds of return. The nominated partner sends the partnership return, and each partner sends an individual Self Assessment return. GOV.UK asks the nominated partner to complete the partnership return as soon as possible, because the other partners use its figures for their own returns. A late partnership return means a penalty for each individual partner, and the Self Assessment bill is paid by 31 January. VAT is a separate registration: it is compulsory once VAT taxable turnover is more than £90,000.
Questions about SA400
Does an LLP incorporated in 2026 need to send SA400?
The form says LLPs and LPs registered with Companies House from 25 October 2010 are registered for Self Assessment through that Companies House registration. Each partner still registers on SA401 or SA402.
Can the nominated partner’s own registration go on SA400?
SA400 only covers the partnership. Question 13 takes the nominated partner’s existing UTR if they have one, and the note beneath it says they must also complete SA401.
Can SA400 be emailed or uploaded?
The paper route on GOV.UK is printing and posting to BX9 1AN. The electronic alternative is the online registration service, which needs a Government Gateway user ID.