Form 740-ES is the Kentucky estimated tax voucher for individuals, and estates and trusts use the same voucher. The 2026 version, 42A740ES (10/25), prints four vouchers on one page, one for each installment of tax on income that has no Kentucky withholding, including income from a business or pass-through entity reported on federal Schedule C, E or F. The worksheet that sets the amount is in a separate document, Instructions for Filing Estimated Tax Vouchers 42A740-S4 (9-25), and it stays with your records.
Who has to make Kentucky estimated payments for 2026
The instructions start from KRS 141.305: individuals, estates or trusts who can reasonably expect more than $5,000 of income with no Kentucky tax withheld may be required to pay estimated tax. Under the general rule you pay if both of these apply:
- You expect to owe at least $500 for 2026 after subtracting withholding and refundable credits.
- Your withholding and refundable credits will be less than the smaller of 90% of the tax on your 2026 return or 100% of the tax on your 2025 return, and the 2025 return covered all 12 months.
Two groups use different percentages. If at least two-thirds of your gross income for 2025 or 2026 is from farming, 66 2/3% replaces 90%. If your Kentucky adjusted gross income for 2025 was more than $150,000, or $75,000 if your 2026 filing status is married filing separately, 110% replaces 100%; this higher-income rule does not apply to farmers.
You owe no estimated payments for 2026 if you had no Kentucky tax liability for a full 12-month 2025 tax year, meaning your total tax was zero or you did not have to file. Owners of disregarded single member LLCs and pass-through entities that report on federal Schedule C, E or F are treated in Kentucky as they are federally, apart from differences between the two laws, and may be required to make individual estimated payments on that income.
What changed for 2026
The What’s New paragraph of the 2026 instructions lists two items. The standard deduction rises to $3,360, and that figure appears on line 6 of the worksheet. Individuals, estates and trusts that file electronically can now have estimated payments debited from a bank account; the payment section explains that this is done on Form 8879-K, must be set up when the return is filed, and covers all four installments on their due dates.
Working out the installment on the 2026 worksheet
The Estimated Tax Worksheet (2026) is on page 2 of the instructions. Its lines in order:
| Line | What to enter |
|---|---|
| 1 to 3 | Estimated wages subject to withholding, plus estimated taxable income with no withholding |
| 4 and 5 | Estimated adjustments to income; line 5 is estimated adjusted gross income |
| 6 | Estimated itemized deductions or the $3,360 standard deduction (zero for estates or trusts) |
| 7 and 8 | Estimated net income, then tax at 3.5% |
| 9 | Tax credits: $40 if you are 65 or over or blind, $20 if you are in the Kentucky National Guard |
| 10 | Family size tax credit from the table (zero for estates or trusts) |
| 11 | Kentucky tax to be withheld in 2026; the total of lines 9 to 11 goes at the right |
| 12 | Line 8 minus line 11: estimated Kentucky income tax for 2026. At $500 or less, no payment is required |
| 13(a) to 13(c) | 90% of line 12 (66 2/3% for farmers and fishermen), your 2025 tax (times 110% for higher income), and the smaller of the two |
| 14 | Line 13(c) divided by 4: the amount of each installment |
Here is how the numbers move. Suppose a freelance designer expects $50,000 of taxable income with no withholding, no adjustments and the standard deduction. Line 7 is $46,640 and line 8 is $1,632.40. With no credits and no withholding, line 12 is $1,632.40, so 90% on line 13(a) is $1,469.16. If her 2025 Kentucky tax was $1,300, line 13(b) is $1,300, line 13(c) takes the smaller figure, and each installment on line 14 is $325.
The family size credit on line 10 uses modified gross income: the greater of federal adjusted gross income plus non-Kentucky municipal bond interest and lump-sum pension distributions left out of federal AGI, or Kentucky adjusted gross income plus those lump-sum distributions. At $42,760 or less you may qualify. The table printed on page 3 is labeled Tax Year 2025, provided, the instructions say, for your convenience, so a 2026 estimate is computed with the 2025 brackets. The credit does not apply to fiduciary returns.
The worksheet’s line 9 prompt names $40 for being 65 or over or blind. Schedule ITC for 2025 gives 40 for age and a separate 40 for blindness, so a taxpayer who is both can claim 80 on the return. The 740-ES worksheet does not address that case; Taxpayer Assistance at (502) 564-4581 can confirm what to use in the estimate.
How to fill out a Form 740-ES voucher
Each of the four vouchers has the same boxes, and only the installment number and due date change. The markers on the image match the numbers below.
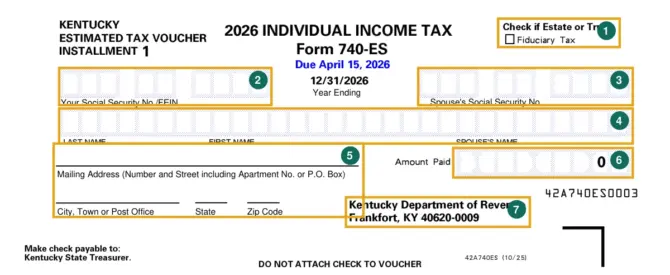
| Marker | Box on the voucher | What to enter |
|---|---|---|
| 1 | Check if Estate or Trust, Fiduciary Tax | Check only for an estate or trust paying fiduciary estimated tax |
| 2 | Your Social Security No./FEIN | Your SSN, or the FEIN of an estate or trust |
| 3 | Spouse’s Social Security No. | Your spouse’s SSN, if the payment also covers a spouse |
| 4 | Last name, first name, spouse’s name | Your last and first name, and your spouse’s name if a spouse is included |
| 5 | Mailing address, city, state, ZIP code | Your current address |
| 6 | Amount Paid | The check amount for this installment only |
| 7 | Kentucky Department of Revenue, Frankfort, KY 40620-0009 | Printed: the address the voucher and check go to |
Do not enter in Amount Paid any part of the installment covered by a 2025 overpayment credited forward. The voucher has no signature line. The year ending date is printed as 12/31/2026; fiscal year filers follow different due dates, described below.
Due dates for the four 2026 installments
Installments for calendar year 2026 are due April 15, June 15 and September 15, 2026, and January 15, 2027. You may also pay the whole year at once on the first due date that applies to you. A voucher is filed only when a payment is due.
If your income changes during the year, the instructions spread the required payment over the installments that remain:
| Estimate first required or changes | Due date | Equal installments |
|---|---|---|
| January 1 to April 1 | April 15, 2026 | 4 |
| April 2 to June 1 | June 15, 2026 | 3 |
| June 2 to September 1 | September 15, 2026 | 2 |
| September 2 to December 31 | January 15, 2027 | 1 |
When the change comes after September 1, 2026, no voucher is needed if you file the 2026 return and pay the tax due by February 1, 2027. The Amended Computation Schedule on page 3 recomputes the remaining payments: amended estimated tax, minus the 2025 overpayment credited and payments made so far, divided by the installments left. People with uneven income, such as a seasonal business or a large capital gain late in the year, can look at the annualized income installment method in chapter 2 of federal Publication 505.
Farmers and fishermen with at least two-thirds of gross income from farming or fishing in 2025 or 2026 have two other options: pay all estimated tax by January 15, 2027, or file the 2026 Form 740 or 740-NP by March 1, 2027 and pay the full tax then. Fiscal year filers pay on the 15th day of the fourth, sixth and ninth months of the fiscal year and the 15th day of the first month of the next one.
Using a 2025 overpayment first
If you credited part of a 2025 refund to 2026 (Form 740, line 40), the instructions say to use that credit before making any installment payment. The Record of Estimated Tax Payments Schedule on page 3 tracks it: column B is the line 14 installment, column C the overpayment applied, and column D the difference, which is what goes on the voucher. When D is zero or less, you do not file that voucher, and any excess credit moves to column C of the next line. The schedule and the amended computation are for your records and are not mailed.
How to pay and where to send the voucher
- Check: payable to Kentucky State Treasurer, with your Social Security number written on the face. Mail it with the voucher to Kentucky Department of Revenue, Frankfort, KY 40620-0009. Each voucher says not to attach the check to it.
- First installment with your return: if you pay installment 1 when you file Form 740, write a separate check for the voucher amount and include the voucher marked Installment 1.
- Form 8879-K: electronic filers can authorize the Department to debit all four installments on their due dates, set up at the time of filing.
- ACH debit through the Department’s website, revenue.ky.gov; the 2025 Form 740 instructions name this payment option Form EPAY.
Download the 2026 Form 740-ES PDF and the instructions with the worksheet from the Department’s forms list, where both are marked Current for 2026. On the 2025 Form 740, estimated payments and the credit carried from the 2024 return are entered on line 31(b). Other states run their own vouchers, for example Alabama Form 40ES.
Penalty for late or short installments
An installment not paid by its due date draws a penalty on the late payment at the rate set by KRS 131.183. The 2025 Form 740 instructions say that if the amount owed is more than $500 you may be subject to the underpayment penalty, entered on line 34(a). Form 2210-K computes the penalty, and qualifying farmers and others use the same form to claim an exemption from it; it is enclosed with the return with the box beside line 34(a) checked.
Questions about Kentucky Form 740-ES
Do I have to send a voucher if my 2025 refund covers the installment?
No voucher is filed when the overpayment covers the installment. The Record of Estimated Tax Payments Schedule says not to file a voucher when column D is zero or less.
Can an estate or trust use Form 740-ES?
The vouchers have a Check if Estate or Trust box for fiduciary tax, and the Social Security number box also takes an FEIN. On the worksheet, estates and trusts enter zero for the standard deduction and for the family size credit.
What tax rate does the 2026 worksheet use?
Line 8 multiplies estimated net income by 3.5%. The 2025 Form 740 instructions give 4% for tax year 2025.
Official sources
- Kentucky Department of Revenue, Form 740-ES, 2026 Individual Income Tax Estimated Tax Voucher, 42A740ES (10/25)
- Kentucky Department of Revenue, Instructions for Filing Estimated Tax Vouchers, 2026, 42A740-S4 (9-25)
- Kentucky Department of Revenue, 2025 Kentucky Individual Income Tax Forms instruction packet, 42A740(PKT) (10-25)
- Kentucky Department of Revenue, Schedule ITC (2025), 42A740ITC (10-25)
- Kentucky Department of Revenue, Forms