Form 40NR is the Alabama income tax return for people who live in another state (or abroad) and had income from Alabama sources, such as wages for work done in Alabama, rent from Alabama property or a share of an Alabama partnership. The return taxes only the Alabama part, but it asks for your income from all sources too: the ratio between the two decides how much of your personal exemption, dependent exemption, deductions and federal tax deduction you can claim. This guide follows the 2025 form and the Form 40NR booklet for tax year 2025, both published by the Alabama Department of Revenue (ALDOR).
Who files Form 40NR, and when Form 40 is the return instead
The booklet says you must use Form 40NR if you are not an Alabama resident, you received taxable income from Alabama sources or for services performed in Alabama, and your Alabama-source gross income exceeds the personal exemption prorated by your Alabama ratio. Its filing table does not give a dollar amount for nonresidents for that reason; it says “Over the allowable prorated exemption.” A single filer whose Alabama income is 25% of total income, for example, has a prorated exemption of $375 (25% of $1,500), so Alabama gross income above $375 means a return is due. The booklet also lists a married couple filing jointly under the Military Spouses Residency Relief Act as a Form 40NR case.
Even below that threshold, you must file to get back Alabama tax that was withheld from your pay. Two groups are treated separately in the booklet:
- Military personnel stationed in Alabama whose legal residence is elsewhere do not file unless they earned Alabama income other than military pay. Military pay is not taxable for nonresidents.
- A person who moved into or out of Alabama during 2025 is a part-year resident and files Form 40 for the months of residence. If that person also had Alabama-source income during the months as a nonresident, both Form 40 and Form 40NR are filed. The full personal exemption and all dependent exemptions then go on Form 40, none on Form 40NR, and each return carries only the income and deductions of its own period.
Some income is not taxed to a nonresident at all but still goes into column B so the ratio comes out right: pensions and annuities that would be taxable to a resident, alimony received, and gains on property located outside Alabama. Gains on stocks, bonds and other intangibles are ordinarily not Alabama income for a nonresident unless the property acquired what the booklet calls a business legal jurisdiction in Alabama, while a gain on real or tangible property located in Alabama is taxable even when no business was carried on in the state.
How to fill out Form 40NR, line by line
Page 1 has three money columns. Column A is Alabama tax withheld, column B is income from all sources and column C is Alabama income. Lines 5 to 9, 11 and 12 take entries in both B and C, and line 10 is a percentage; from line 13 down, single amounts follow, and line 18 is taken from column C. Round to whole dollars and write negative amounts with a minus sign, not parentheses. Above the columns go names and Social Security numbers, the home address (with a box for an address outside the U.S.), the boxes for a deceased taxpayer and the amended return box. Lines 7, 9, 12, 17, 26 and 28 are totals or subtractions printed on the form.
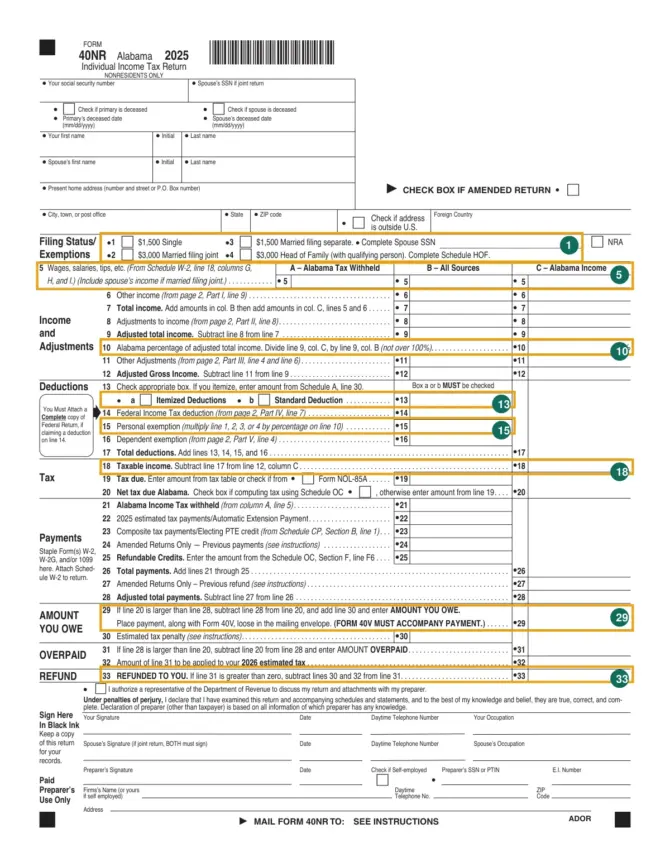
| Line | What goes there | Where it comes from |
|---|---|---|
| 1 to 4 | One filing status box: single ($1,500), married filing joint ($3,000), married filing separate ($1,500, with the spouse’s SSN or the NRA box), head of family ($3,000) | Status on December 31, 2025; head of family needs Schedule HOF |
| 5 | Alabama tax withheld (A), wages from everywhere (B), wages earned in Alabama (C) | Schedule W-2, line 18, columns G, H and I |
| 6 | Interest, dividends, business, rental, farm, pension and other income | Page 2, Part I, line 9 |
| 8 | Adjustments such as IRA, SEP and self-employed health insurance | Page 2, Part II, line 8 |
| 10 | Line 9, column C divided by line 9, column B; 100% if C is larger, 0% if C is a loss | Your own calculation |
| 11 | Alimony paid, adoption expenses, small employer health insurance | Page 2, Part III, line 4 (column B) and line 6 (column C) |
| 13 | Box a with Schedule A, line 30, or box b with the standard deduction; one box must be checked | Schedule A, or the standard deduction chart |
| 14 | Federal income tax deduction | Page 2, Part IV, line 7, with a complete copy of the federal return attached |
| 15 | $1,500 or $3,000 from lines 1 to 4 multiplied by the line 10 percentage | Lines 1 to 4 and line 10 |
| 16 | Dependent exemption | Page 2, Part V, line 4 (Schedule DS first) |
| 18 | Line 12, column C minus total deductions on line 17 | Lines 12 and 17 |
| 19 and 20 | Tax from the tax table, or the NOL-85A box; credits through Schedule OC | Booklet tax tables (pages 21 to 26) |
| 21 to 25 | Withholding, 2025 estimated and extension payments, composite or electing PTE credit, previous payments (amended only), refundable credits | Line 5 column A, Form 40ES and 40V records, Schedule CP, Schedule OC Section F |
| 29 and 30 | Amount you owe, including any estimated tax penalty | Line 20 minus line 28, plus line 30 |
| 31 to 33 | Overpayment, the part applied to 2026 estimated tax, and the refund | Line 28 minus line 20 |
The standard deduction on line 13 is read from the chart using line 12, column B, then multiplied by the line 10 percentage. For a single filer it falls in steps from $3,000 (up to $25,999) to $2,500 ($35,500 and above); for married filing jointly the range is $8,500 to $5,000. If you itemize, Schedule A deductions are prorated by the same ratio, and medical and dental expenses count only above 4% of line 12, column B. A married couple filing separately must both take the same kind of deduction unless they lived apart all year.
Line 14 starts from the Federal Income Tax Deduction Worksheet on page 27 of the booklet (federal tax from line 22 of the 2025 Form 1040, 1040-SR or 1040-NR, less refundable credits such as the earned income credit), and Part IV applies the line 10 percentage. Lines 1 to 3 of Part IV are only for someone who filed a joint federal return and a separate Alabama return. A nonresident alien uses U.S.-source income as total income for this ratio.
Line 16 uses a dependent amount that depends on line 12, column B: $1,000 per dependent up to $50,000, $500 from $50,001 to $100,000 and $300 above $100,000. Part V multiplies the number of dependents from Schedule DS by that amount and then by the line 10 percentage. Under Alabama law a dependent must get more than half of their support from you and be related to you in one of the ways the booklet lists; a friend or a cousin does not qualify.
Page 2: Parts I to VI
Part I splits other income into the same B and C columns. Interest and dividends over $1,500 need Schedule B; alimony received (line 2) and pensions (line 3, with Schedule RS) go in column B only; business and farm income come from federal Schedules C and F, property sales from Schedule D, and rents, partnerships, S corporations, estates and trusts from Schedule E. A foreign earned income exclusion goes on line 8 as a negative number, with federal Form 2555 attached.
Part II lists adjustments to income, among them payments to Alabama’s College Counts 529 Fund or PACT program (line 5) and ABLE account contributions of up to $5,000 a year (line 7); the early withdrawal penalty on line 2 is a column B entry only. Part III takes alimony paid, adoption expenses and small employer health insurance, and its column C figure is the column B total times the line 10 percentage.
Part VI must be completed by every filer: your 2025 state of legal residence and whether you filed there, your spouse’s separate income and return, whether you filed an Alabama return for 2024, your employers’ names and addresses, and your 2025 federal adjusted gross income. A driver’s license block (date of birth, issuing state, number and dates) follows, with a box for filers who have none.
Example: wages split between Alabama and another state
Take a hypothetical single filer who lives in another state and earned $60,000 in wages in 2025, of which $15,000 was for work done in Alabama. There is no other income and no adjustment. Line 9 shows $60,000 in column B and $15,000 in column C, so line 10 is 25%.
- Standard deduction: line 12, column B is $60,000, so the single chart gives $2,500; 25% of that is $625.
- Federal income tax deduction: assume the worksheet gives $5,000 of federal tax; 25% is $1,250.
- Personal exemption: 25% of $1,500 is $375. No dependents.
- Line 17 totals $2,250, and line 18 is $15,000 minus $2,250, or $12,750.
In the 2025 tax table, taxable income of at least $12,700 but less than $12,800 shows $598 in the column for single and married filing separately. That goes on line 19 and, with no credits, on line 20. Alabama tax withheld by the employer comes into line 21 from Schedule W-2, and the difference becomes line 29 or line 31.
Schedules and copies that go with the return
The booklet asks you to attach the state copies of Forms W-2, W-2G and 1099 and a completed copy of your federal return to the front of the return, and the schedules behind it in order starting with Form 40NR. Not every schedule applies to every filer:
- Schedule W-2, completed in full, or the Alabama withholding is not credited
- Schedule DS for dependents and Schedule HOF for head of family
- Schedules A, B, D and E (Form 40NR) when itemizing or reporting those income types
- Schedule RS for pensions, annuities and IRA distributions
- Schedule OC for credits, and Schedule CP for composite payments or the electing PTE credit
- Federal Schedules C and F, Form 3903 or Form 2555 where those lines are used
- Form NOL-85A for a net operating loss carried from another year, Form 2210AL for the underpayment penalty
- For a deceased taxpayer, the date of death on page 1 and a copy of the death certificate
- A statement explaining why your spouse does not file, if you file separately and your spouse files no return
The return is signed in black ink by you and, on a joint return, by your spouse; ALDOR does not treat an unsigned form as a return. A paid preparer generally signs by hand in the Paid Preparer’s Use Only area, and the box above the signature line lets ALDOR discuss the return with that preparer.
Due date, extension and late filing for the 2025 return
Form 40NR is due on the same day as the federal return, which ALDOR’s filing information page gives as April 15 for most individuals, moved to the next business day when it falls on a weekend or state holiday. For 2025 returns that was April 15, 2026. An automatic extension to October 15, 2026 applied without any form, but it covered filing only: tax you expected to owe should have been paid by the April date with Form 40V and its “Automatic Extension Payment” box checked.
Both dates have passed as of this guide’s last check, so a 2025 Form 40NR filed now is late. The booklet sets the late filing penalty at 10% of the tax due or $50, whichever is greater, and it does not apply when the return shows no tax due or a refund. Late payment adds 1% of the unpaid tax per month or part of a month, up to 25%, plus interest at the IRS rate. To get a refund, an original return must be filed within two years of the date the tax was paid.
Estimated payments for 2026 are made on Form 40ES, mailed separately from the return. The booklet says anyone who reasonably expects to owe at least $500 for 2026 must pay estimated tax, and line 30 warns that a balance due over $500 may bring an underpayment penalty.
Filing online or mailing Form 40NR
ALDOR’s My Alabama Taxes (MAT) site files an original Form 40NR at no charge after you create an account; it does not take amended individual returns. Commercial software on ALDOR’s Tax Year 2025 list of authorized e-file providers files the federal and Alabama returns together, and the list shows which products also accept an amended 40NR. A tax practitioner can e-file both returns as well.
On paper, the fillable PDF calculates the yellow fields and prints a 2-D barcode at the top when you use the green Print button on the form; the booklet says the barcode speeds processing. The mailing address depends on line 29 or line 33:
| Your return shows | Mail to |
|---|---|
| A refund on line 33 | Alabama Department of Revenue, P.O. Box 154, Montgomery, AL 36135-0001 |
| An amount owed on line 29 | Alabama Department of Revenue, P.O. Box 2401, Montgomery, AL 36140-0001, with Form 40V and the payment placed loose in the envelope |
| Neither | Alabama Department of Revenue, P.O. Box 327469, Montgomery, AL 36132-7469 |
A check or money order is payable to the “Alabama Department of Revenue” and carries your Social Security number, daytime phone number and “2025 Form 40NR”. Paying online through MAT by e-check is free; card payments carry a convenience fee, and Form 40V is not used for either. A payment drawn on a foreign bank needs an extra $25 exchange fee.
What delays a Form 40NR refund
The booklet gives 8 to 12 weeks after mailing for a complete return without errors, asks you to wait 90 days before inquiring, and lists these reasons for a refund taking longer:
- A wrong or missing Social Security number, including one your employer reported incorrectly on the W-2
- W-2 forms or supporting schedules not attached; if you notice after mailing, send them only when ALDOR asks
- A standard deduction not taken from the chart, or tax read from the wrong filing status column
- A return mailed to the wrong one of the three addresses, or more than one return filed
- A copy sent instead of the original, or a return not signed; original signatures are required
- Estimated payments claimed under a Social Security number that differs from last year’s return or the vouchers
- Unpaid tax from a prior year, or a debt reported by another state agency, which is taken from the refund
Refund status is on ALDOR’s “Where’s My Refund” page or the Refund Hotline, 1-855-894-7391. If ALDOR has not paid within 90 days of the due date or of filing, whichever is later, it adds interest to the refund.
Amended returns and a deceased taxpayer
An amended 2025 return is a new Form 40NR with the amended box checked and a page explaining every change; line 24 takes the payments already made and line 27 the refund already received. For a taxpayer who died, the spouse or personal representative checks the deceased box, enters the date of death and attaches the death certificate. A surviving spouse filing jointly writes “Filing as surviving spouse” in the signature area; Form 1310A is needed only to have a refund check reissued in the survivor’s name or when another person claims the refund.
Where to get the official 2025 Form 40NR PDF
ALDOR publishes the 2025 Form 40NR fillable package (Form 40NR with its schedules and worksheets, 40 pages), a two-page print-only version and the 29-page Form 40NR booklet with the instructions and tax tables. The fillable form’s own note asks for Adobe Reader or Acrobat, since other PDF viewers do not run its calculations and print button. ALDOR’s nine Taxpayer Service Centers, listed on page 3 of the booklet, answer questions and hand out forms.
Questions about Form 40NR
Can I claim credit on Form 40NR for tax paid to my home state?
The 40NR booklet has no Schedule CR, the Alabama schedule for credit for taxes paid to another state. Whether your home state gives a credit for the Alabama tax is a question for that state’s own return.
Can I file an amended Form 40NR in My Alabama Taxes?
ALDOR’s electronic filing page says MAT does not support amended individual income tax returns. An amended 40NR goes on paper or through one of the listed software products marked as supporting amended 40NR returns.
Official sources
- Alabama Department of Revenue, 2025 Form 40NR, Individual Income Tax Return, Nonresidents Only (fillable package)
- Alabama Department of Revenue, Form 40NR Booklet, Nonresidents Only, Forms and Instructions 2025
- Alabama Department of Revenue, 2025 Alabama Individual Income Tax Return, Nonresidents Only, form page
- Alabama Department of Revenue, 2025 Form 40NR, print-only version
- Alabama Department of Revenue, Standard Deduction Chart 40NR (2025)
- Alabama Department of Revenue, Individual Income Tax: General Information for Individuals
- Alabama Department of Revenue, Individual income tax electronic filing options