Form A4-MS, the Nonresident Military Spouse Withholding Tax Exemption Certificate, is how the spouse of an active duty servicemember tells an Alabama employer not to withhold Alabama income tax from wages. The claim rests on the Military Spouses Residency Relief Act (P.L. 111-97), and it works only when the employee can answer True to all seven statements printed on the form. The current file is revision 4/25. It goes to the employer, who keeps it with the employee’s personnel records; it is not filed with the Alabama Department of Revenue (ALDOR).
Who can use Form A4-MS
ALDOR’s withholding booklet (revised January 2026) describes the exemption as covering nonresident employees whose spouse is an active member of the US Armed Services present in Alabama in compliance with military orders. Rule 810-3-73-.01(4) of the Alabama Administrative Code puts it the same way: the exemption applies to the spouse of a service member who is in Alabama under military orders and who keeps a domicile in another state.
Take a nurse whose legal home is Texas. Her husband, an Army sergeant, receives orders to a post in Alabama, she moves with him, and she takes a job at a hospital nearby. She is not in the military herself, they share an address, and her domicile and his are both Texas. Every statement on the form is True for her, so she can give the hospital a signed A4-MS together with the documents listed in Part II.
The same form rules out several situations. A spouse who is also a servicemember answers False to statement 2. A spouse who was already living and working in Alabama before the orders came, and is not there solely to be with the servicemember, answers False to statement 4. A spouse whose domicile is Alabama answers False to statement 6. The form says that anyone who cannot answer True to all seven does not qualify and completes Form A4, the regular Alabama employee’s withholding certificate.
The seven statements in Part I
Each statement has a True box and a False box. The form adds that if all are True, the employee’s wages are exempt from Alabama withholding tax.
| No. | Statement on the form | What it means in practice |
|---|---|---|
| 1 | My Spouse is an active duty military servicemember | The servicemember spouse is on active duty. |
| 2 | I am not a military servicemember | The employee claiming the exemption is the civilian spouse. |
| 3 | My Spouse’s current military orders assign him/her to a location in/near Alabama | The orders in force today place the servicemember in or near Alabama. |
| 4 | I am present in/near Alabama solely to be with my servicemember Spouse | The reason for being in Alabama is the spouse’s assignment. |
| 5 | I and my military servicemember Spouse live at the same address | The address in Part I is the home both share. |
| 6 | My domicile is a state other than Alabama | The employee’s legal home is outside Alabama. |
| 7 | My military servicemember Spouse’s domicile is the same as mine, or I will be selecting my Spouse’s domicile for tax purposes | Both domiciles match, or the employee is taking the servicemember’s domicile for tax purposes. |
Statement 7 is worded differently in two ALDOR documents. The standalone PDF on the form’s page (A4MS_0425.pdf, marked REV. 4/25) contains the “or I will be selecting my Spouse’s domicile for tax purposes” option. The copy printed on PDF page 83 of the withholding booklet revised January 2026 (marked REV. 4/2025) stops at “the same as mine” and has no selection option. Neither document explains the difference. An employee whose own domicile differs from the servicemember’s, and who relies on the selection wording, can ask the Withholding Tax Section at (334) 242-1300 which version applies before signing.
How to fill out Form A4-MS
The form is a one-page fillable PDF in two parts: Part I for the employee and Part II for the employer. The markers on the image follow the order below.
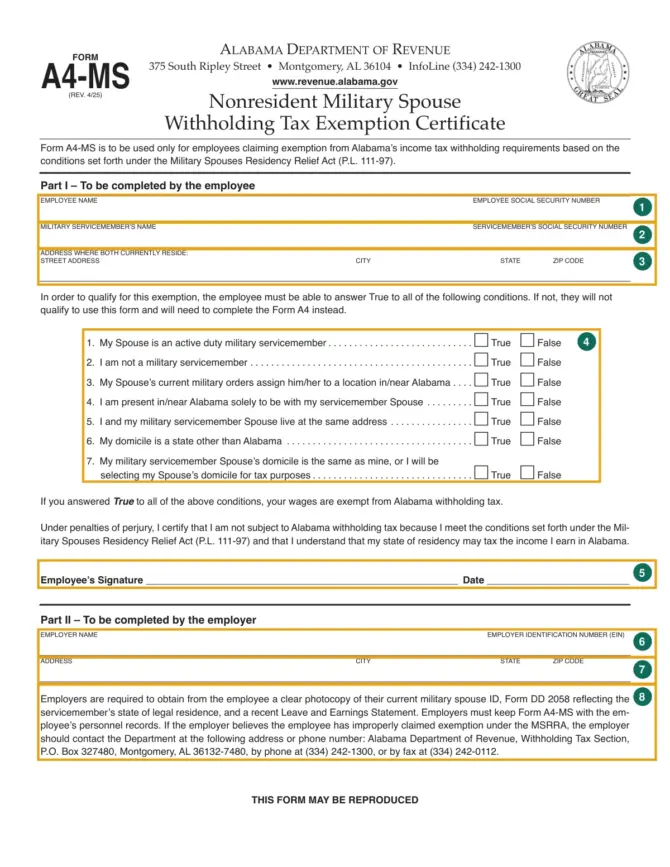
| Marker | Field | What goes there |
|---|---|---|
| 1 | Employee name, employee Social Security number | The civilian spouse’s name and SSN. |
| 2 | Military servicemember’s name, servicemember’s Social Security number | The active duty spouse’s name and SSN. |
| 3 | Address where both currently reside: street address, city, state, ZIP code | The one address the couple shares, which is what statement 5 certifies. |
| 4 | Statements 1 to 7, True or False | One box per line. A single False means the employee completes Form A4 instead. |
| 5 | Employee’s signature, date | Signed under penalties of perjury. |
| 6 | Employer name, employer identification number (EIN) | Completed by the employer. |
| 7 | Employer address, city, state, ZIP code | Completed by the employer. |
| 8 | Employer instructions | The documents the employer collects and the ALDOR contact for doubtful claims. |
By signing at marker 5 the employee certifies two things: that he or she is not subject to Alabama withholding tax because the MSRRA conditions are met, and that he or she understands the state of residency may tax the income earned in Alabama.
What the employer collects and keeps
The instructions in Part II require the employer to get three things from the employee:
- a clear photocopy of the employee’s current military spouse ID;
- Form DD 2058 showing the servicemember’s state of legal residence;
- a recent Leave and Earnings Statement.
The employer keeps Form A4-MS with the employee’s personnel records. Rule 810-3-73-.01(4) adds a payroll step that the form itself does not mention: the employer reports the employee’s wages on Form W-2 showing the state of legal residency from the spouse’s DD-2058 or current Leave and Earnings Statement, and keeps a copy of those forms on file.
If the employer believes the employee has claimed the exemption improperly, the form directs it to the Alabama Department of Revenue, Withholding Tax Section, P.O. Box 327480, Montgomery, AL 36132-7480, phone (334) 242-1300, fax (334) 242-0112.
When an A4-MS claim does not hold
- One statement answered False. The form says such an employee does not qualify and completes Form A4.
- No signed certificate. Rule 810-3-73-.01(3) says that when an employee does not give the employer a signed Alabama withholding exemption certificate, the employer withholds using zero exemptions.
- A false claim. Under rule 810-3-73-.01(6)(a), an employee who falsely claims exemption on Form A4-MS is subject to a $500 penalty under section 40-29-75 of the Code of Alabama. That section ties the penalty to a statement that lowers withholding and had no reasonable basis when it was made. Rule 810-3-73-.01(6)(b) adds the penalties of section 40-2A-11 and possible criminal prosecution for anyone who does not comply.
Where to get Form A4-MS and who answers questions
The Form A4-MS PDF (REV. 4/25) is linked from ALDOR’s Nonresident Military Spouse Withholding Exemption Certificate page, where the form number is A4-MS and the year is shown as ALL. The form states that it may be reproduced. ALDOR’s Withholding Tax page lists the same certificate as “Revised September 2019”, but the link opens the 4/25 file. A second copy sits near the end of the withholding booklet, with the statement 7 difference described above.
The completed form goes to the employer. Neither the form nor rule 810-3-73-.01 gives a filing date or an address for sending it to ALDOR, and neither says when a new A4-MS is needed after orders change; for those questions the Withholding Tax Section at (334) 242-1300 is the contact. The same Withholding Tax page also lists Alabama Form 2848A, Power of Attorney and Declaration of Representative. This page explains the form; it is not tax advice for a particular household.
Questions about Alabama Form A4-MS
Do I mail Form A4-MS to the Alabama Department of Revenue?
The form goes to your employer, who keeps it with your personnel records along with copies of your military spouse ID, the DD 2058 and a recent Leave and Earnings Statement. ALDOR’s address on the form is for employers who doubt a claim.
Can I use Form A4-MS if I am also in the military?
Statement 2 reads “I am not a military servicemember.” A servicemember cannot answer it True, and the form sends anyone with a False answer to Form A4.
Does Form A4-MS mean I owe no tax anywhere on my Alabama wages?
The certificate stops Alabama withholding. In signing it you state that you understand your state of residency may tax the income you earn in Alabama.
Which state does my employer put on my W-2?
Rule 810-3-73-.01(4) says the employer reports your wages on Form W-2 under the state of legal residency shown on your spouse’s DD-2058 or current Leave and Earnings Statement.
Official sources
- Alabama Department of Revenue, Form A4-MS, Nonresident Military Spouse Withholding Tax Exemption Certificate (REV. 4/25)
- Alabama Department of Revenue, Nonresident Military Spouse Withholding Exemption Certificate, form page
- Alabama Department of Revenue, Withholding Tax Tables and Instructions for Employers and Withholding Agents (revised January 2026)
- Alabama Department of Revenue, Withholding Tax
- Alabama Administrative Code, Rule 810-3-73-.01, Withholding Exemption Certificates
- Code of Alabama 1975, Section 40-29-75, False Information with Respect to Withholding