Alabama Form 4952A limits the investment interest expense deductible for 2025 and records the disallowed amount carried into 2026. It uses six lines: current interest and the prior carryforward are compared with net investment income, then the allowed deduction is transferred to the applicable Alabama return schedule.
The Alabama Department of Revenue publishes the 2025 form with its instructions on the same page. The PDF is headed 2025 and carries the barcode 25002849.
Who must attach Form 4952A?
An individual, estate or trust claiming an investment interest expense deduction must attach the form unless all four printed exceptions apply: the only investment income is interest or dividends, there are no other deductible expenses of producing that income, investment interest does not exceed investment income, and there is no investment-interest carryforward from 2024.
The instructions treat investment property as property producing investment income, including an interest in an activity in which the taxpayer did not materially participate. Where loan proceeds were used for several purposes, interest may need allocation among investment, personal, business and home mortgage uses. The Alabama instructions refer to federal Publication 550 for those allocation details.
How to complete the identification and six lines
Enter the names shown on the return, the identifying number, and the return type: individual, estate or trust. There is no separate signature on this attachment.
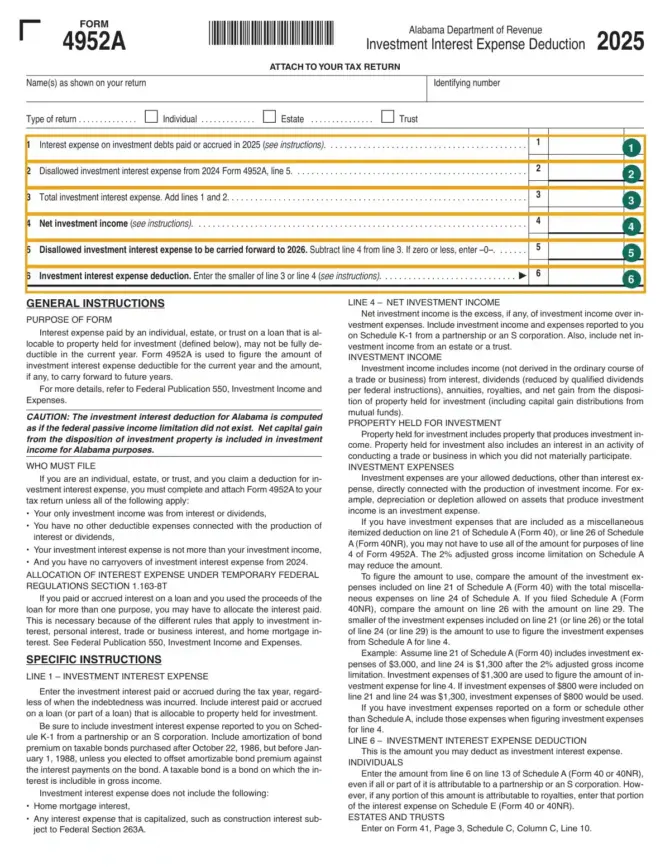
| Line | Entry or calculation | Source |
|---|---|---|
| 1 | Investment-debt interest paid or accrued in 2025. | Interest records and any applicable partnership or S corporation Schedule K-1. |
| 2 | The disallowed investment interest from 2024 Form 4952A, line 5. | The prior year’s Alabama form. |
| 3 | Add lines 1 and 2. | The total current expense plus carryforward. |
| 4 | Net investment income under the Alabama instructions. | Investment income less the investment expenses allowed for this calculation. |
| 5 | Subtract line 4 from line 3, entering zero if the result is zero or less. Carry this amount into 2026. | The disallowed balance. |
| 6 | The smaller of line 3 or line 4. | The investment interest expense deduction. |
Line 1 can include qualifying investment interest reported by a partnership or S corporation. The instructions also address amortization of premiums on taxable bonds bought after October 22, 1986 and before January 1, 1988, unless an election was made to offset that premium against bond interest. Home mortgage interest and capitalized interest, such as construction interest subject to federal section 263A, are excluded from investment interest expense here.
Figuring net investment income on line 4
Investment income includes qualifying interest, dividends reduced by qualified dividends under the federal instructions, annuities, royalties and net gains from investment property, including mutual fund capital-gain distributions. Include applicable Schedule K-1 investment income and expenses and net investment income from an estate or trust.
The Alabama form specifically says to calculate its deduction as if the federal passive income limitation did not exist, and to include net capital gains from disposing of investment property in investment income for Alabama purposes. Follow these Alabama instructions when completing line 4.
Investment expenses are allowed non-interest deductions directly connected with producing investment income, such as applicable depreciation or depletion. For investment expenses within miscellaneous itemized deductions, the form accounts for the 2% adjusted gross income limit by comparing:
| Return schedule | Investment expense included on | Compare with |
|---|---|---|
| Schedule A, Form 40 | Line 21 | Total miscellaneous expenses on line 24 |
| Schedule A, Form 40NR | Line 26 | Total miscellaneous expenses on line 29 |
Use the smaller amount from the applicable comparison for those Schedule A investment expenses in the line 4 calculation. Include investment expenses reported elsewhere as instructed. For example, $900 of investment expenses included in a miscellaneous-deduction line and $600 remaining after the schedule’s limitation contribute $600 to this calculation.
Deduction and carryforward example
If 2025 investment interest is $2,400 and the 2024 carryforward is $600, line 3 is $3,000. With net investment income of $2,200, line 5 carries $800 to 2026 and line 6 allows $2,200. These example figures illustrate the form’s arithmetic; the underlying expenses and income must qualify under its instructions.
Individuals put line 6 on line 13 of Schedule A for Form 40 or 40NR, even when the expense comes from a partnership or S corporation. The portion attributable to royalties goes to Schedule E instead. Estates and trusts transfer the deduction to Form 41, page 3, Schedule C, column C, line 10.
Official PDF and filing with the tax return
Download the 2025 Alabama Form 4952A and attach it to the applicable return. The form has no independent payment or separate mailing step.
For paper individual returns, the department’s mailing-address page distinguishes these current Form 40 and 40NR destinations:
| Return situation | Alabama Department of Revenue address |
|---|---|
| Making a payment | P.O. Box 2401, Montgomery, AL 36140-0001 |
| Receiving a refund | P.O. Box 154, Montgomery, AL 36135-0001 |
| No refund and no payment | P.O. Box 327469, Montgomery, AL 36132-7469 |
For Form 41 with a payment, the page gives Alabama Department of Revenue, Income Tax Administration Division, P.O. Box 327444, Montgomery, AL 36132-7444. Without a payment, it gives the same division at P.O. Box 327440, Montgomery, AL 36132-7440. Follow the fiduciary return’s filing instructions. The filing deadline is the deadline of the return to which 4952A is attached; the deduction attachment does not provide an extension.