Form AR-OI collects the income and loss items that have no line of their own on an Arkansas individual return: gambling and lottery winnings, cancelled debt, taxable HSA distributions, name, image and likeness (NIL) payments, a net operating loss carried forward, and the gap between federal and Arkansas depreciation. Lines 1 to 10 add income, lines 12 to 18 subtract it, and the net figure on line 20 becomes line 22, “Other income/depreciation differences”, on Form AR1000F or AR1000NR. This guide follows the 2025 form, AR-OI (R 5/14/2025), and its instruction sheet, AR-OI Inst. (R 6/24/2025), both from the Arkansas Department of Finance and Administration (DFA).
Who files AR-OI with a 2025 Arkansas return
You attach AR-OI whenever line 22 of AR1000F (full-year residents) or AR1000NR (part-year residents and nonresidents) has an amount on it; the line itself says “Attach Form AR-OI”. The DFA booklet for those returns gives examples of what belongs there: cancelled debt, income from a pass-through entity that paid Arkansas pass-through entity tax (PET), gambling winnings, a medical expense reimbursement for an earlier year in which you itemized and the deduction reduced your tax, a recovered bad debt you deducted before, and a net operating loss brought forward to 2025. If none of the 20 lines applies to you, line 22 stays empty and AR-OI is not part of your return.
Some items that sound similar go elsewhere. Gambling losses are an itemized deduction on Form AR3, line 27, and cannot exceed gambling winnings; AR-OI has no line for them. Adjustments such as HSA contributions or student loan interest belong on Form AR1000ADJ and line 24 of the return.
AR-OI has no signature block and no payment line. It travels with the return, which for a calendar-year 2025 filer is due by April 15, 2026, or November 15 with a federal extension on Form 4868 or an Arkansas extension on Form AR1055-IT. The booklet says the program for e-filing federal and Arkansas returns together is open to most full-year residents and to certain nonresidents and part-year residents. A paper return asking for a refund goes to P.O. Box 1000, Little Rock, AR 72203-1000; one with tax due, or with neither tax due nor refund, goes to P.O. Box 2144, Little Rock, AR 72203-2144.
How to fill out Form AR-OI line by line
The header asks for the primary taxpayer’s full legal name and Social Security number or ITIN. Below it the form prints which columns you use. A full-year resident uses column A (Primary/Joint) alone, plus column B (Spouse) only under filing status 4, married filing separately on the same return. A nonresident or part-year resident fills column A and column C (Arkansas Only), and column B as well under status 4. On AR1000NR, column C carries income from Arkansas sources or received while an Arkansas resident, while columns A and B show income from all sources for the whole year as if you had lived in Arkansas all year. DFA’s instructions say to round every amount to the nearest dollar, and each box on AR-OI already prints “00” for cents.
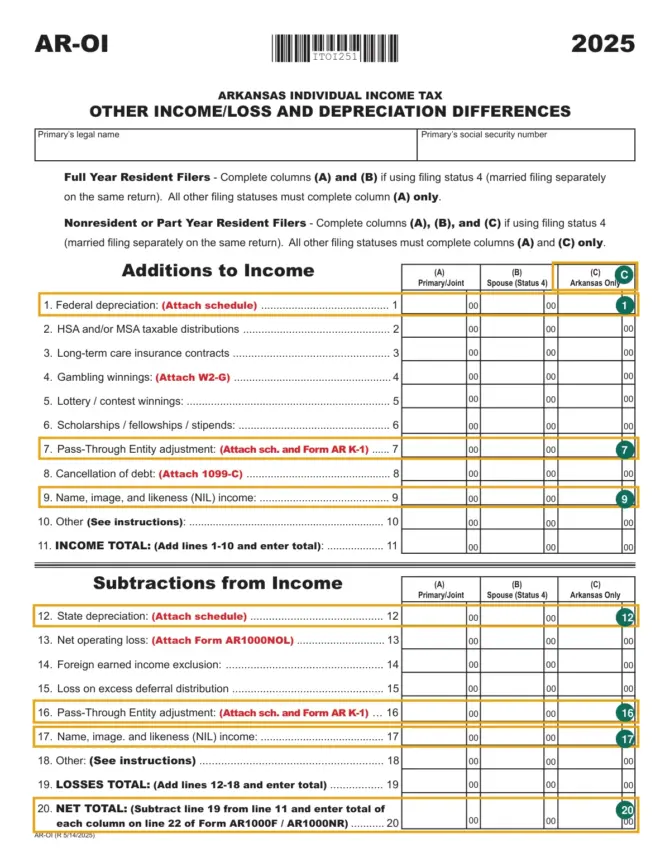
| Line | Item | What you enter | Attach |
|---|---|---|---|
| 1 | Federal depreciation | Depreciation claimed on your federal schedules for the year | Federal Form 4562 and the schedules behind the figure |
| 2 | HSA or MSA taxable distributions | Distributions from a Health Savings Account or Medical Savings Account that are taxable | Form 1099-SA |
| 3 | Long-term care insurance contracts | Taxable portion of a distribution received | Form 1099-LTC |
| 4 | Gambling winnings | Total won by gambling, lottery excluded | Form W-2G |
| 5 | Lottery or contest winnings | Amount won from a lottery or contest | Form W-2G |
| 6 | Scholarships, fellowships, stipends | Taxable part only | W-2, 1042-S, 1099-MISC, 1099-NEC or 1098-T, as applicable |
| 7 | Pass-through entity adjustment (addition) | Exempt losses from an entity taxed at the entity level, capital gains excluded, not claimed on Schedule E | AR K-1 and/or AR1099PT |
| 8 | Cancellation of debt | Amount from Form 1099-C, unless an exclusion applies | Form 1099-C |
| 9 | NIL income | All income earned under a name, image and likeness agreement | None named |
| 10 | Other income | Income not reported anywhere else | Explanation and any schedules |
| 11 | Income total | Lines 1 to 10, column by column | |
| 12 | State depreciation | Depreciation allowed in Arkansas and not claimed elsewhere | Schedule |
| 13 | Net operating loss | NOL deduction claimed for 2025 | Form AR1000NOL |
| 14 | Foreign earned income exclusion | Amount from line 42 of federal Form 2555 | Form 2555 |
| 15 | Loss on excess deferral distribution | Distribution withdrawn before April 15, 2026 | None named |
| 16 | Pass-through entity adjustment (subtraction) | Exempt income from an entity taxed at the entity level, capital gains excluded | AR K-1 and/or AR1099PT |
| 17 | NIL income (subtraction) | Nontaxable portion of NIL income | None named |
| 18 | Other loss | Loss not reported anywhere else | Explanation and any schedules |
| 19 | Losses total | Lines 12 to 18, column by column | |
| 20 | Net total | Line 11 minus line 19, each column | Goes to line 22 of AR1000F or AR1000NR |
Lines 1 and 12: two depreciation figures
Arkansas has not adopted the federal bonus depreciation rule of Internal Revenue Code section 168(k), so the depreciation in your federal return and the depreciation Arkansas allows can differ. AR-OI handles this in two steps. Line 1 adds back the whole federal depreciation figure, with Form 4562 attached, and line 12 subtracts the Arkansas amount, with your own schedule. Only the difference survives into line 20. For section 179 expensing, the booklet’s page 20 says Arkansas follows IRC section 179 as in effect on January 1, 2022, for purchases made after 2022, with a $1,250,000 deduction limit and a $3,130,000 limit on the cost of qualifying property; the deduction phases out dollar for dollar above that and reaches zero at $4,270,000.
Take a hypothetical sole proprietor whose 2025 federal return shows $40,000 of depreciation, much of it bonus depreciation, while the Arkansas schedule allows $8,000 on the same assets. Line 1 is $40,000, line 12 is $8,000, and the net $32,000 raises line 22 of the return. The same booklet tells you to adjust for the depreciation difference on sold assets too: on Form AR1000D (lines 2, 5 and 10) for capital gains and on line 15 of the return for Form 4797 gains.
Lines 7 and 16: income already taxed at the entity level
Members of an entity that elected the Arkansas pass-through entity tax report all income from the PET return on their individual return, then use AR-OI to back it out. Exempt income, capital gains excluded, comes off on line 16; the instructions point to the amount of that income on your Schedule E. Exempt losses, capital gains again excluded, are added back on line 7 when they were not claimed on Schedule E. Gains and losses of such an entity are left off line 14 of the return altogether. The tax the entity paid for you is not entered as withholding on your return; the entity pays it itself, by check with Form AR1100PTV or online. AR-OI asks for Form AR K-1 with either line, and the instructions add AR1099PT.
Lines 9 and 17: NIL payments
Line 9 takes everything earned under name, image and likeness agreements. Line 17 then subtracts the nontaxable part, and the instructions limit that part to money a student-athlete receives from an institution of higher education as compensation for the use of his or her name, image or likeness. A student-athlete paid by a college and by an outside business would enter both amounts on line 9 and only the college payment on line 17.
Line 8: cancelled debt
Line 8 starts from the amount on Form 1099-C, which must be attached. DFA’s instructions say cancelled debt is generally taxable but list exceptions, “including but not limited to” student loans forgiven under the Public Service Loan Forgiveness program (PSLF) and student loans forgiven because of total and permanent disability (TPD). DFA tells you to check with your loan servicer which type of forgiveness you received.
Lines 2 to 6: distributions, winnings and scholarships
For line 2, DFA’s Subject 304 note on medical and health savings accounts (revised 2/27/2023) says money paid out of an HSA for qualified medical expenses is not included in gross income, while distributions not used for those expenses are. That matches the wording “taxable distributions” printed on the line. Line 3 also takes only the taxable portion of a long-term care distribution.
Gambling winnings go on line 4 and lottery or contest winnings on line 5, each with its W-2G. On line 6, the booklet treats a scholarship, fellowship or grant as exempt only for a degree candidate and only to the extent it paid tuition and enrollment fees, or the fees, books, supplies and equipment required of every student in the course. Stipends are taxable. A foreign student exempt from federal tax under a treaty still owes Arkansas tax on a nonqualified scholarship or fellowship.
Lines 10, 13 and 18: other items and NOL
Line 10 is for income that no other line covers, and it needs an attached explanation; line 18 is its counterpart for losses. The booklet also sends the taxable amount of a Coverdell Education Savings Account distribution to AR-OI and line 22 without naming an AR-OI line, so it falls under line 10. A net operating loss from an earlier year is a subtraction on line 13 with Form AR1000NOL showing the loss and the year it arose. Arkansas allows NOLs to be carried forward but not back.
Where the line 20 total goes on AR1000F and AR1000NR
Line 20 is line 11 minus line 19, figured separately for each column. The booklet describes the line 22 entry as net other income or loss, so a column where line 19 is larger than line 11 carries a loss. Each column goes to the matching column of line 22 on the return. Line 23, total income, adds lines 8 through 22, so the AR-OI result flows into adjusted gross income on line 25 after AR1000ADJ adjustments are taken off on line 24. On AR1000NR the tax is computed on columns A and B and then prorated using the Arkansas income in column C, so an amount in AR-OI column C changes the Arkansas share as well as total income.
What goes in the envelope with AR-OI
- Form 4562 and the schedules behind line 1, and your Arkansas depreciation schedule for line 12.
- Form 1099-SA for line 2, Form 1099-LTC for line 3, Form 1099-C for line 8.
- W-2G forms for lines 4 and 5, stapled with the state W-2s, 1099-Rs, 1099PTs and 1099-Gs to the left margin of page 1 of the return; the booklet warns that leaving them off may delay processing.
- Form AR K-1 (and AR1099PT where you have one) for lines 7 and 16.
- Form AR1000NOL for line 13 and federal Form 2555 for line 14.
- A written explanation for any amount on line 10 or 18.
- For AR1000NR filers, a copy of pages 1 and 2 of the federal Form 1040; DFA says the Arkansas return will not be processed without it.
- Line 20 of each column matches line 22 of the same column on the return.
Getting the official 2025 AR-OI PDF
DFA lists two files for this schedule on its 2025 Tax Forms page: “AR-OI Other Income Loss and Depreciation Differences”, a fillable one-page PDF, and a separate one-page instruction sheet. AR-OI is also one of the form inserts in the 2025 AR1000F and AR1000NR booklet. For questions, the booklet gives the Individual Income Tax hotline, (501) 682-1100 or (800) 882-9275, staffed Monday through Friday from 8:00 a.m. to 5:00 p.m.
Official PDF: Form AR-OI — Official PDF (dfa.arkansas.gov)
Questions about AR-OI
Do I report my W-2G gambling winnings on AR-OI or directly on the return?
On AR-OI line 4, with the W-2G attached; the result reaches the return through line 22. Losses are claimed separately on Form AR3, line 27, up to the amount of your winnings.
My federal student loan was discharged under PSLF. Does it go on line 8?
DFA’s instructions name PSLF forgiveness as one of the exceptions to taxable cancelled debt. DFA asks you to confirm with your loan servicer which kind of forgiveness you received.
Official sources
- Arkansas Department of Finance and Administration, AR-OI, Other Income/Loss and Depreciation Differences, 2025 (R 5/14/2025)
- Arkansas Department of Finance and Administration, Instructions for AR-OI (R 6/24/2025)
- Arkansas Department of Finance and Administration, Arkansas 2025 Individual Income Tax Forms and Instructions (AR1000F and AR1000NR booklet)
- Arkansas Department of Finance and Administration, Form AR1000F, 2025
- Arkansas Department of Finance and Administration, Form AR1000NR, 2025
- Arkansas Department of Finance and Administration, Subject 304, Medical and Health Savings Accounts (revised 2/27/2023)
- Arkansas Department of Finance and Administration, Form AR1100PTV, Pass-Through Entity Tax Payment Voucher
- Arkansas Department of Finance and Administration, 2025 Tax Forms