Form CIT-HIC is the annual information return a corporation files with the Delaware Division of Revenue when it claims exemption from Delaware corporate income tax as a holding or investment company under 30 Del. C. § 1902(b)(8). It carries no tax computation. It lists the corporation’s Delaware employees and large shareholders and asks yes-or-no questions about its income and activities, and the answers indicate to the Division whether the exemption fits. The current version is the 2025 CIT-HIC, Revision 20250529, with instructions revised 10/03/25.
Which corporations file CIT-HIC
Section 1902(b)(8) exempts corporations whose activities within Delaware are confined to the maintenance and management of their intangible investments, or of the intangible investments of corporations or trusts registered as investment companies under the Investment Company Act of 1940, and the collection and distribution of the income from those investments or from tangible property physically located outside Delaware. The statute counts stocks, bonds, notes and other debt obligations (including debt of affiliated corporations), patents, patent applications, trademarks, trade names and similar intangible assets as intangible investments.
Section 1904(f) lets the Division require an information return from any corporation exempt under § 1902(b), and the CIT-HIC instructions say the form must be filed annually by every corporation claiming the § 1902(b)(8) exemption. A Delaware subsidiary that holds a group’s trademarks and collects royalties from affiliates in other states, with no other activity in Delaware, is the kind of company the form was written for.
Two other groups are handled elsewhere:
- A corporation incorporated in Delaware that only keeps a statutory corporate office there and does no business in the state is exempt from filing the corporate income tax return under § 1902(b)(6), according to the 2025 CIT-TAX instructions. It still owes the annual franchise tax collected by the Secretary of State.
- Every other domestic or foreign corporation doing business in Delaware and not exempt under § 1902(b) files Form CIT-TAX, whatever its income. A corporation that e-files CIT-TAX and pays by check sends the payment with Delaware Form CIT-VCH.
CIT-EXM: asking the Division for a ruling first
The CIT-TAX instructions say a corporation may obtain a specific ruling on the § 1902(b)(8) exemption by filing an application that describes its operations and the grounds for the exemption. The instructions still call it Form 1902AP. The Division’s Business Tax Forms page lists the application as CIT-EXM, Application for Exemption from Corporate Income Tax, Holding Company (Revision 20240903).
CIT-EXM asks for the corporation’s name, address, taxpayer ID, nature of business and date and state of incorporation, then a detailed description of its Delaware operations with each type of intangible investment and all sources of income. The form warns in capitals that reciting the statute does not constitute an answer. Four yes-or-no questions follow: whether the corporation will act as a general partner, join a joint venture, receive income from patents, royalties, copyrights or know-how, or do business outside Delaware. It also lists Delaware employees and owners of more than 10% of the stock. The signed application goes to the Delaware Division of Revenue, 820 N. French Street, Wilmington, DE 19801, Attn: Conferee.
How to fill out Form CIT-HIC, part by part
CIT-HIC has two pages: identification and Parts I and II on page 1, Parts III and IV and the signature on page 2. The image shows page 1 with the fields numbered as in the table.
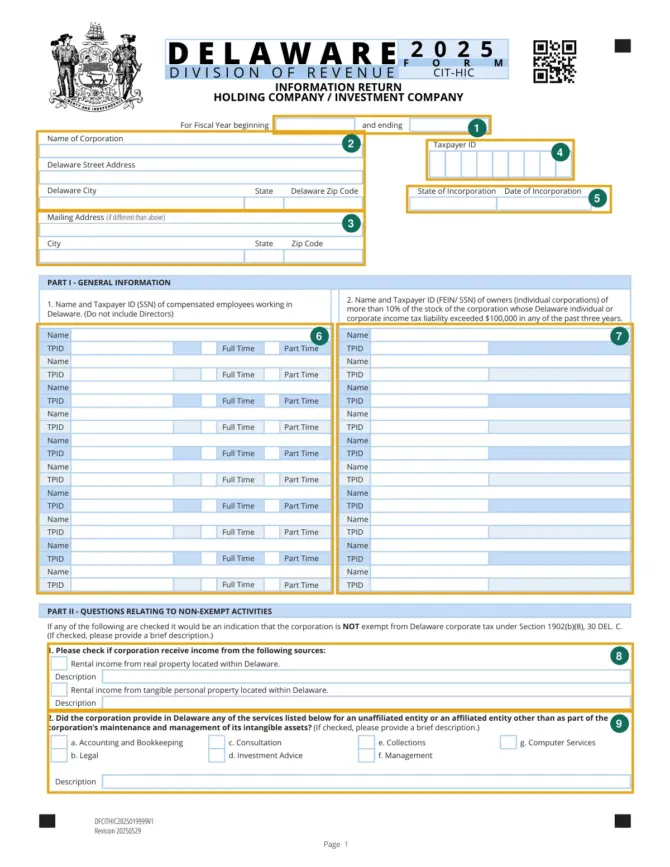
| Marker | Field | What to enter |
|---|---|---|
| 1 | For fiscal year beginning / and ending | The corporation’s taxable year, which the instructions tie to the year used for federal income tax. |
| 2 | Name of corporation, Delaware street address, city, state, zip code | The corporation’s name and its address in Delaware. |
| 3 | Mailing address | Only if mail goes somewhere other than the Delaware address. |
| 4 | Taxpayer ID | The corporation’s taxpayer ID. |
| 5 | State of incorporation, date of incorporation | Where and when the corporation was incorporated. |
| 6 | Part I, line 1 | Name and taxpayer ID of each individual the corporation employs in Delaware, marked full time or part time. Directors are left out. Ten rows are printed; attach a schedule for more. |
| 7 | Part I, line 2 | Name and FEIN or SSN of each owner of more than 10% of the outstanding stock whose Delaware individual or corporate income tax liability exceeded $100,000 in any of the past three years. The instructions include individuals, partnerships and corporations as owners. |
| 8 | Part II, question 1 | Check if the corporation received rental income from real property or from tangible personal property located in Delaware, and describe the activity for each box checked. |
| 9 | Part II, question 2 | Check each service the corporation provided in Delaware, for an unaffiliated entity or for an affiliate other than as part of managing its own intangible assets: accounting and bookkeeping, legal, consultation, investment advice, collections, management, computer services. Describe them. |
A checked box in Part II is, in the words of the form, an indication that the corporation is not exempt under § 1902(b)(8).
Part III, Part IV and the signature on page 2
Part III lists the income the exemption is meant for. Question 1 asks whether the corporation directly or indirectly received any of these:
- a. interest on notes secured by real estate mortgages
- b. interest on all other debt obligations
- c. dividends
- d. income from patents, patent applications, trademarks, trade names and know-how
- e. gain on the sale of intangible investments
- f. rental income from real property located outside Delaware
- g. rental income from tangible personal property located outside Delaware
For each box checked where the income exceeds $1 million, the corporation describes the activity it performed in Delaware with regard to that income. Question 2 asks, yes or no, whether the corporation does business outside Delaware beyond what question 1 covers, with a description if yes. Checked boxes in Part III are an indication that the corporation is exempt.
Part IV asks whether the corporation had any other source of income not described in Parts II and III; if yes, it describes that income and the related Delaware activity. The return is then signed under penalties of perjury by an officer or designee, with title, date, email address and phone number.
Due date, extension and mailing address
CIT-HIC is due on or before the 15th day of the fourth month after the end of the taxable year, which for a calendar year 2025 corporation is April 15, 2026. Two kinds of extension are accepted:
- A six-month automatic extension requested from the IRS automatically extends the Delaware CIT-HIC by six months.
- Without a federal extension, the corporation can request more time by letter on or before the due date.
A copy of the extension granted, federal Form 7004 or the Division of Revenue’s approval letter, must be attached to CIT-HIC when it is filed. The form is mailed, not uploaded; the instructions give the address as Division of Revenue, 820 N. French Street, P.O. Box 2044, Wilmington, Delaware 19899-2044, and the form itself prints Delaware Division of Revenue, PO Box 2044, Wilmington, DE 19899-2044. The form has no tax or payment lines.
Before you mail CIT-HIC
- Fiscal year dates match the federal tax year.
- Every Delaware employee except directors is listed, with full or part time marked.
- Owners above 10% are listed if their Delaware income tax liability exceeded $100,000 in any of the last three years.
- Each checked box in Parts II and III has its description, and Part III descriptions are given where the income exceeds $1 million.
- The return is signed and dated by an officer or designee, and the federal Form 7004 or Delaware approval letter is attached if the return is filed on extension.
Where to get Form CIT-HIC and who to ask
Download the 2025 Form CIT-HIC PDF and its instructions from the Division of Revenue’s Business Tax Forms page, where CIT-HIC appears as “Delaware Information Return Holding Company / Investment Company” next to CIT-EXM. The 2025 CIT-TAX instructions list the Division of Revenue offices: Carvel State Office Building, 820 N. French Street, Wilmington, (302) 577-8205; Thomas Collins Building, Dover, (302) 744-1085; Georgetown, (302) 856-5358; and the toll-free number 1-(800) 292-7826 for calls within Delaware. This page explains the form; it does not decide whether a particular corporation qualifies for the exemption.
Questions about Delaware Form CIT-HIC
Is Form 1902(b) the same as CIT-HIC?
“1902(b)” is the section of Title 30 of the Delaware Code that lists the exemptions; CIT-HIC is the information return for corporations claiming the exemption in paragraph (b)(8). The 2025 forms page lists no separate form numbered 1902(b).
Does a Delaware holding company pay tax with CIT-HIC?
The form has no tax or payment lines. It reports employees, owners and income sources so the Division can see whether the § 1902(b)(8) exemption applies.
What if the holding company earns rent from a building in Delaware?
Rental income from real property located in Delaware is a Part II item, and the form says a checked Part II box indicates the corporation is not exempt under § 1902(b)(8). Corporations that are not exempt file Form CIT-TAX.
Can CIT-HIC be filed late with an extension?
A six-month federal extension extends it automatically; otherwise a letter to the Division by the due date can request more time. Attach the federal Form 7004 or the Division’s approval letter to the return.
Official sources
- Delaware Division of Revenue, Form CIT-HIC, Information Return, Holding Company / Investment Company, 2025 (Revision 20250529)
- Delaware Division of Revenue, Form CIT-HIC Instructions, 2025 (revised 10/03/25)
- Delaware Division of Revenue, Form CIT-EXM, Application for Exemption from Corporation Income Tax (Revision 20240903)
- Delaware Division of Revenue, Form CIT-TAX Instructions, 2025 (revised 01/21/26)
- Delaware Code, Title 30, Chapter 19, Corporation Income Tax (§ 1902, § 1904)
- Delaware Division of Revenue, Business Tax Forms 2025-2026