Form 1065-X is the paper form a partnership uses to change a Form 1065 it has already filed, and a REMIC uses it for a filed Form 1066. It does two different jobs that share one page set: a plain amended return for a partnership that elected out of the centralized partnership audit regime (non-BBA), and an administrative adjustment request (AAR) for a partnership still under that regime (BBA). A third use belongs to a partnership that is itself a partner in an audited BBA partnership. The current form is the October 2025 revision, with separate instructions of the same date, and it is meant for tax years beginning after 2024.
Who files Form 1065-X and who files electronically
The instructions start with a condition: use Form 1065-X if you aren’t filing electronically. Whether the correction must be e-filed is generally decided by the same test that applies to the original Form 1065. For 2025, the Form 1065 instructions require electronic filing from a partnership that files 10 or more returns of any type during the tax year, counting information, income tax, employment tax and excise tax returns, and from every partnership with more than 100 partners.
| Situation | Paper route | Electronic route |
|---|---|---|
| Non-BBA partnership correcting its return | Form 1065-X as an amended return, with amended Schedules K-1 | Form 1065 with box G(5) checked and a statement listing each changed line |
| BBA partnership correcting partnership-related items | Form 1065-X as a BBA AAR, with Forms 8985 and 8986 when needed | Form 8082 together with Form 1065, box G(5) checked |
| Partnership-partner amending as part of an imputed underpayment (IU) modification during a BBA exam | Form 1065-X, Section 2 | Amended Form 1065, payment on page 1, line 26 |
| REMIC with two or more residual interest holders that didn’t elect out | Form 1065-X as a BBA AAR | Not described in the 1065-X instructions |
A BBA partnership is any partnership with a tax year beginning after 2017 that has not made a valid election out under section 6221(b). Under BBA, certain partnerships with 100 or fewer eligible partners can elect out. A BBA partnership must use an AAR to change partnership-related items, unless specific guidance allows an amended return.
AAR or amended return: what changes between BBA and non-BBA
The same columns are filled in either way, but the people, the partner statements and the money are handled differently.
| Point | Non-BBA amended return | BBA AAR |
|---|---|---|
| Box in Part I | Non-BBA, then Part II | BBA AAR, then Section 1 |
| Who signs | Any partner or LLC member; a receiver, trustee or assignee signs for the partnership when one is acting | The partnership representative (PR) for the reviewed year, or the designated individual (DI) if the PR is an entity |
| What partners receive | Amended Schedules K-1, also filed with Form 1065-X | Form 8986, filed with Form 8985; no amended Schedules K-1 |
| Schedules K-2 and K-3 (years beginning in 2021 or later) | Amended K-2 with the “Amended K-2” box on line D checked (for years before 2025, “As Amended” written at the top); amended K-3s furnished to partners | No amended K-2 or K-3; the changes go on Forms 8985 and 8986 |
| Tax owed by the partnership | Part IV, which covers the BBA IU, is not used | Part IV: the IU, unless the adjustments are pushed out to the partners |
How to fill out page 1 of Form 1065-X
Page 1 holds the identifying lines, the single choice in Part I and the two sections that only some filers complete. The numbers below match the marked image.
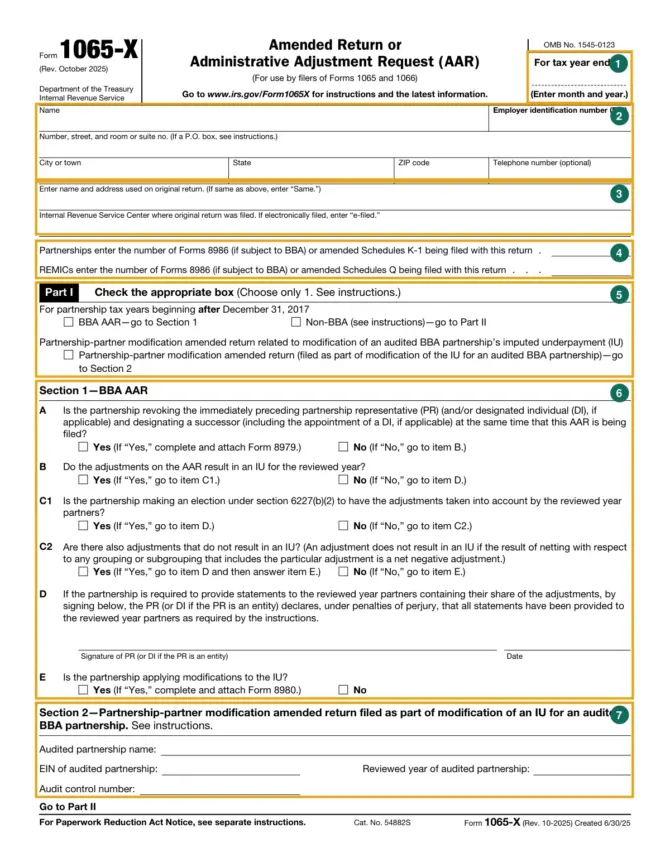
| Mark | Line or block | What to enter |
|---|---|---|
| 1 | For tax year ending | Month and year that the corrected return covers. |
| 2 | Name, EIN, address, telephone (optional) | Legal name and EIN. Put the suite or room number after the street; use a P.O. box only if mail isn’t delivered to the street address. For mail sent to an accountant or attorney, write “C/O” with that person’s name and address. A foreign address goes in the order city, province or state, country, without abbreviating the country. |
| 3 | Name and address used on the original return; IRS service center | “Same” if nothing changed. Then the service center where the original was filed, or “e-filed”. |
| 4 | Number of Forms 8986 or amended Schedules K-1 (REMICs: Forms 8986 or amended Schedules Q) | Count of the partner statements filed with this Form 1065-X. |
| 5 | Part I | Check one box only: BBA AAR, Non-BBA, or partnership-partner modification amended return. |
| 6 | Section 1, items A to E | BBA AAR only (see the next section). |
| 7 | Section 2 | Partnership-partner modification only: name, EIN and reviewed year of the audited partnership, and its audit control number. |
If the old address on line 3 is no longer the partnership’s mailing address, the IRS form for reporting a new business mailing address, business location or responsible party is Form 8822-B; Form 1065-X itself only records both addresses. When an item in Part I or Part II can’t be completed, the instructions say to enter “See Part V” in that space and give the information in Part V.
Section 1 for a BBA AAR, items A to E
Section 1 is a short decision path. Each answer tells you which item comes next.
Item A gets a “Yes” only if the partnership is replacing its PR (or DI) at the same time it files the AAR; Form 8979 is then attached. Changing the PR is never a reason on its own to file an AAR.
Item B asks whether the adjustments produce an IU for the reviewed year, which is the partnership year being corrected. A 2023 correction has 2023 as the reviewed year. If the answer is “Yes”, item C1 asks whether the partnership elects under section 6227(b)(2) to have the reviewed year partners take the adjustments into account. That is the push-out election. With a valid election the partnership is no longer liable for the IU; if the election later turns out to be invalid, the partnership still owes it. Item C2 asks whether some adjustments produce no IU, meaning a grouping or subgrouping nets to a negative amount.
Item D is a signature line. Whenever the partnership must send Forms 8986 to reviewed year partners, the PR (or the DI when the PR is an entity) signs here, under penalties of perjury, that every statement has been provided. Item E asks whether the partnership is modifying the IU; “Yes” means Form 8980 is attached. Modifications are disregarded if a valid push-out election is made.
The IRS page on BBA AARs adds a timing rule: the Forms 8986 must reach the partners on the date the AAR is filed with the IRS.
Part II line by line: columns (a), (b) and (c)
Part II is for partnerships that file Form 1065; REMICs skip it. Its lines follow Schedule K, and the form notes that “see instructions” in Part II points to the Form 1065 and Schedule K-1 instructions for the year being changed.
| Column | What goes in it |
|---|---|
| (a) As originally reported | The Schedule K amount as filed or as previously adjusted. For a non-BBA partnership whose return the IRS changed or audited, the adjusted amount. |
| (b) Net change | Increase as a positive number, decrease in parentheses. Every change is explained in Part V. |
| (c) Correct amount | Column (a) plus column (b). |
| Lines | Items |
|---|---|
| 1 to 11 | Income (loss): ordinary business income, rental real estate, other rental, guaranteed payments, interest, dividends (6a to 6c), royalties, short-term and long-term capital gain (8, 9a to 9c), section 1231 gain, other income |
| 12, 13a to 13e | Deductions: section 179, cash and noncash contributions, investment interest, section 59(e) expenditures, other deductions |
| 14a to 14c | Self-employment: net earnings, gross farming or fishing income, gross nonfarm income |
| 15a to 15f | Credits, including the two low-income housing credit lines |
| 16a, 16b | Box for attaching Schedule K-2 with items of international tax relevance, or box for the Schedule K-2 filing exception |
| 17a to 17f | Alternative minimum tax items |
| 18a to 21 | Tax-exempt income and nondeductible expenses, distributions, investment income and expenses, other items, total foreign taxes paid or accrued |
For a BBA AAR with a push-out election, the instructions tie column (b) of Part II to column (g) of Form 8985, Part IV: the two sets of figures should match.
Part III for REMICs
A REMIC describes each changed item in column (a) of Part III, then gives the original amount, the change and the correct amount in columns (b) to (d). Lines 6 to 8 are the three REMIC taxes (prohibited transactions, foreclosure property, contributions after the startup day) and line 9 totals them. Line 10 is tax paid with Form 7004 and line 11 tax paid with or after the original return. Line 13 takes the overpayment shown on the original return even if it was credited to next year’s estimated tax, because that refund is paid separately. Line 15 is tax due; line 16 shows only the additional overpayment, and the IRS figures any interest on it.
A REMIC that is not subject to BBA files amended Schedules Q with Form 1065-X, furnishes them to the residual interest holders and checks “Amended Schedule Q” on line E. A REMIC filing an AAR uses Forms 8986 and 8985. A REMIC asking for a direct deposit refund of $1 million or more attaches Form 8302.
Part IV: the imputed underpayment and how to pay it
Every BBA AAR includes an IU computation with supporting documentation, even when the result is zero or less or no adjustment produces an IU. Part IV has four lines:
| Line | Entry |
|---|---|
| 1 IU | The IU, or the modified IU if Form 8980 is attached. Zero when the result is zero or less, when no adjustment results in an IU, or when the push-out election is made. |
| 2 Total amount due | IU plus any prepaid estimated interest and prepaid estimated penalties. |
| 3 Total payment | The amount paid, including the parts for the IU, interest and penalties. |
| 4 Balance due | Line 2 minus line 3. |
The IU formula is the total netted partnership adjustment (TNPA) multiplied by the highest rate in effect for the reviewed year under section 1 or 11, plus the net positive adjustments in the credit and creditable expenditure groupings. Each adjustment first goes into one of four groupings (reallocation, credit, creditable expenditure, residual), then into subgroupings that generally follow the Schedule K and K-1 line items, and is netted only within its own subgrouping. A reallocation is never netted. If $5,000 of interest income was allocated to the wrong partner, the $5,000 increase for the correct partner enters the TNPA, and the $5,000 decrease for the other partner is an adjustment that doesn’t result in an IU and goes out to that partner on Form 8986.
When the AAR shows an IU and the partnership does not push out, section 6232(a)(2) requires payment when the AAR is filed. For an electronic payment, choose “BBA AAR Imputed Underpayment” as the payment type; a partnership-partner paying under Section 2 chooses “Partner Pymnt for BBA Modification”. The IRS BBA AAR page lists EFTPS and debit or credit card for the IU and says Direct Pay is not available for this payment.
On paper payments the official documents differ. The Form 1065-X instructions (Rev. October 2025, Making a Payment) allow a check, money order or cash only for filers who qualify for an exception to electronic payment, such as having no access to U.S. banking. The IRS page “File an administrative adjustment request for a BBA partnership” (last updated March 27, 2026) lists “Pay by check or money order” for the IU without mentioning those exceptions. Both say the check is payable to “United States Treasury” and carries the partnership name, TIN, tax year and “BBA AAR Imputed Underpayment”. The IRS phone line for businesses is 800-829-4933, 7 a.m. to 7 p.m. local time, Monday through Friday.
Part V, signatures and the paid preparer block
Part V, on page 4, takes the explanations: the Part II or Part III line number before each item, the reason for the change, and for partnerships the Schedule K-1 box number and code the item was reported under. Computations go here in detail, including how the IU was figured and how modifications were applied. A changed allocation of income, gain, loss, deduction or credit to a partner needs the nature and the reason for the change. Extra pages may be added.
The signature block on page 3 is for the current PR (or DI), an LLC member or a partner. For a non-BBA partnership the instructions say Form 1065-X isn’t considered a return unless it is signed, and a receiver or trustee in bankruptcy attaches a copy of the court order or instructions authorizing the signature. REMICs with a startup day after November 9, 1988, may have Form 1065-X signed by whoever could sign the entity’s return without the REMIC election, such as a corporate officer or a trustee; a REMIC filing a BBA AAR is signed by its PR or DI.
A paid preparer signs, completes the Paid Preparer Use Only block with a PTIN (a Social Security number can’t be used there) and gives the partnership a copy. The block stays blank when a partner or employee prepares the form, or when the preparer doesn’t charge.
When Form 1065-X can be filed
An amended return or AAR is generally filed within 3 years after the later of the date the partnership return was filed or the last day for filing it, without extensions. A Form 1065 filed on or before its due date is therefore measured from that due date, and one filed after it, including on extension, from the date it was filed. A BBA partnership must also file before a notice of administrative proceeding for that year is mailed under section 6231; the IRS BBA page mentions limited exceptions, such as a foreign tax redetermination. A partnership-partner filing as part of a modification follows the period set in section 6225(c).
Interest is generally charged on tax not paid by the due date of the reviewed year return, even when an extension to file was granted, at the section 6621 rate. The late payment penalty is usually ½ of 1% of the unpaid tax for each month or part of a month, up to 25%. For an IU that the partnership pays, interest covers the period from the day after the reviewed year return due date to the adjustment year return due date, or to the payment date if earlier.
What to attach to Form 1065-X
- Any schedule, statement or form that supports a corrected amount, each with the partnership’s name and EIN.
- Copies of previously filed forms or schedules, each with the words “Copy Only” and “Do Not Process” written at the top.
- Non-BBA: amended Schedules K-1, and for years beginning in 2021 or later, the amended Schedule K-2 and Schedules K-3.
- BBA AAR: Form 8985 and every Form 8986 furnished to partners, when there is a push-out election or an adjustment that doesn’t result in an IU.
- Form 8979 if item A is “Yes”; Form 8980 if item E is “Yes”.
- Documentation of the IU computation, and of any prepaid interest and penalties.
- REMICs: amended Schedules Q (non-BBA), and Form 8302 for a refund of $1 million or more by direct deposit.
To fill in column (a), the partnership needs the figures from the return as filed. If its own copy is missing, a copy of the filed return can be requested on Form 4506, which can generally be signed by any person who was a member of the partnership during the period requested; its instructions allow up to 75 calendar days for processing.
Filings the instructions say won’t work
- A BBA AAR sent with amended Schedules K-1, K-2 or K-3. Partners of a BBA partnership get their shares on Form 8986.
- An AAR filed after the IRS mailed a notice of administrative proceeding, or by a partner who is not the PR.
- Form 1065-X used to elect out of BBA. The election is made only on a timely filed original return.
- Form 1065-X used for a partner’s notice of inconsistent treatment under section 6222. That is Form 8082.
- A push-out election treated as final. If it is invalid, the IU can still be assessed against the partnership, and Form 8980 modifications are then considered.
- Taxes, penalties and changes to an IU reported earlier, pushed out to partners. These are entity-level liabilities the partnership pays itself when it furnishes the statements.
What changed in the October 2025 revision
- A revision is assigned by tax year: October 2025 for years beginning after 2024, August 2023 for years beginning in 2023 and 2024, December 2021 for 2021 and 2022, and September 2018 for years beginning before 2020. The prior revisions are on IRS.gov/pub/irs-prior. The list does not name a revision for tax years beginning in 2020.
- All references to TEFRA and to electing large partnerships were removed. The former Section 1, TEFRA/NonTEFRA Determination, was dropped and the later sections renumbered, so the BBA AAR items are now Section 1.
- Section 174A, added by P.L. 119-21, allows a current deduction for domestic research or experimental expenditures, or an election to amortize them over at least 60 months. Rev. Proc. 2025-28 covers elections for domestic R&E expenditures paid or incurred after 2021 and before 2025.
For a correction to a tax year beginning in 2020, the revision list gives no answer. The About Form 1065-X page links to a list of all Form 1065-X revisions, and the IRS phone line for businesses is 800-829-4933.
Where to get Form 1065-X and where to mail it
The Form 1065-X PDF (Rev. October 2025) and its instructions are linked from the IRS “About Form 1065-X” page. The form is four pages: page 1 for Part I and Sections 1 and 2, page 2 for Part II, page 3 for Parts III and IV and the signatures, page 4 for Part V.
The instructions give one rule for mailing: file Form 1065-X with the service center where the original return was filed. For a 2025 Form 1065 filed on paper, the Form 1065 instructions assign these centers:
| Principal business, office or agency | Total assets at year end | Service center |
|---|---|---|
| CT, DE, DC, GA, IL, IN, KY, ME, MD, MA, MI, NH, NJ, NY, NC, OH, PA, RI, SC, TN, VT, VA, WV, WI | Less than $10 million, no Schedule M-3 | Department of the Treasury, Internal Revenue Service Center, Kansas City, MO 64999-0011 |
| Same states | $10 million or more, or Schedule M-3 filed | Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201-0011 |
| AL, AK, AZ, AR, CA, CO, FL, HI, ID, IA, KS, LA, MN, MS, MO, MT, NE, NV, NM, ND, OK, OR, SD, TX, UT, WA, WY | Any amount | Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201-0011 |
| A foreign country or U.S. territory | Any amount | Internal Revenue Service, P.O. Box 409101, Ogden, UT 84409 |
For an earlier year, the center is the one the original return actually went to, which line 3 of Form 1065-X also asks for. When the original was e-filed and the correction is allowed on paper, the form only asks you to write “e-filed”, and neither the Form 1065-X instructions nor the 2025 Form 1065 instructions name a mailing center for that case. For that case, the IRS phone line for businesses is 800-829-4933.
A change to the federal return may also affect the partnership’s state return; the instructions point to the state tax agency where it was filed.
Official sources
- Internal Revenue Service, Form 1065-X, Amended Return or Administrative Adjustment Request (AAR), Rev. October 2025
- Internal Revenue Service, Instructions for Form 1065-X (Rev. October 2025)
- Internal Revenue Service, About Form 1065-X
- Internal Revenue Service, 2025 Instructions for Form 1065 (Electronic Filing, Where To File, Administrative Adjustment Request, Amended Return)
- Internal Revenue Service, File an administrative adjustment request for a BBA partnership
- Internal Revenue Service, How to figure an imputed underpayment
- Internal Revenue Service, Let us help you (telephone numbers)
- Internal Revenue Service, Form 4506, Request for Copy of Tax Return (April 2025)
- Internal Revenue Service, Form 8822-B, Change of Address or Responsible Party, Business (Rev. December 2019)