Schedule UTC is how a Kentucky employer claims $100 for each person it hired after that person had been certified as unemployed. The credit comes from KRS 141.065, and the same two-page schedule goes with seven different returns: Forms 720, 720U, PTE, 725, 740, 740-NP and 741. The 2025 version is coded 42A740-UTC (10-25). Page 1 lists the employees; page 2 turns the count into dollars and tells each type of filer where the credit lands on its own return.
Which hires qualify for the $100 credit
The instructions printed on page 2 of the schedule set three conditions for each person. Before you hired them, the person had to be classified as unemployed for at least 60 days by the state workforce office (the Education and Workforce Development Cabinet, Department of Workforce Investment). After hiring, the person must stay on your payroll for at least 180 consecutive days during the taxable year in which you claim the credit. The 2025 Form 720 instructions add that the person is a Kentucky resident and call the credit a one-time, nonrefundable $100 per qualified person.
The period of unemployment has to be certified by the Office of Employment and Training in Frankfort, and you keep a copy of that certification in your own files. The Form 720 instructions give 502-564-7456 for certification questions. Schedule ITC’s 2025 instructions, written for individuals, give the office’s mailing address as 275 East Main Street, 2-WA, Frankfort, KY 40621-0001, and say an individual employer can be eligible for people hired during the last six months of 2024 or during 2025.
KRS 141.065(3), quoted on the schedule, rules out four kinds of hires even if the unemployment certification is in order:
- a person for whom you receive federally funded payments for on-the-job training;
- a relative of yours of the kinds listed in paragraphs (1) through (8) of IRC section 152(a), or, when the employer is a corporation, a relative of that kind of an individual who owns, directly or indirectly, more than 50% in value of the corporation’s stock;
- for an estate or trust, a grantor, beneficiary or fiduciary, or a relative of one of them;
- a dependent described in IRC section 152(a)(9), of the taxpayer or, for an estate or trust, of its grantor, beneficiary or fiduciary.
Two more limits apply to employers rather than employees. Related corporations, and related unincorporated trades or businesses, count as one employer, and no qualified employee can be claimed more than once for any tax year. An organization exempt from income tax under KRS Chapter 141 gets no credit at all.
Filling in page 1 of Schedule UTC
The markers on the image match the rows of the table below. Page 1 has room for 23 employees on lines 1 to 23.
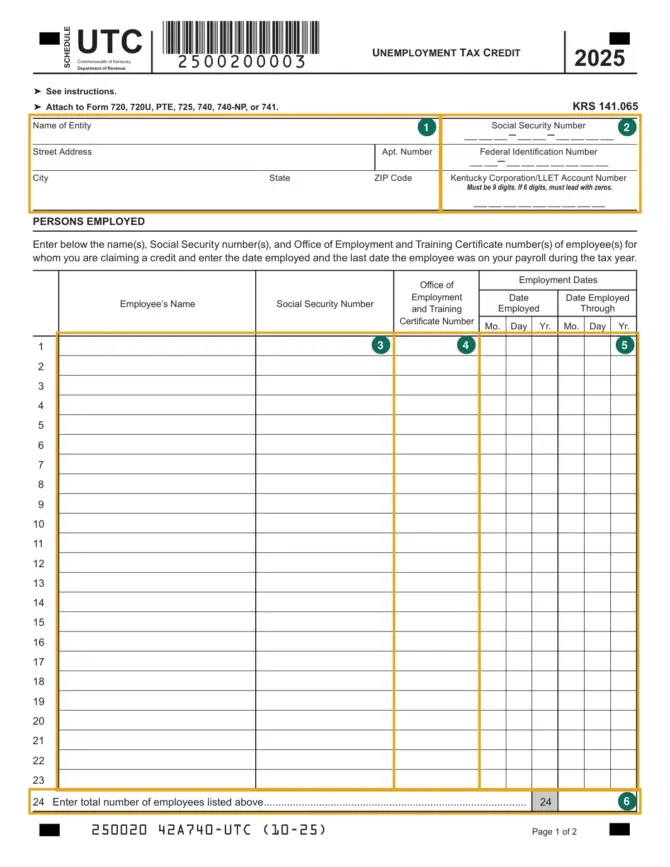
| Marker | Part of the form | What to enter |
|---|---|---|
| 1 | Name of Entity, street address, apartment number, city, state, ZIP | The taxpayer filing the return the schedule is attached to. |
| 2 | Social Security Number, Federal Identification Number, Kentucky Corporation/LLET Account Number | The identifying numbers your return uses. The account number must be 9 digits; a 6-digit number is entered with leading zeros. |
| 3 | Employee’s Name, Social Security Number (lines 1 to 23) | One line for each qualified person you are claiming. |
| 4 | Office of Employment and Training Certificate Number | The number on that person’s unemployment certification. |
| 5 | Employment Dates: Date Employed, Date Employed Through | Month, day and year the person started, and the last date the person was on your payroll during the tax year. |
| 6 | Line 24 | The total number of employees listed on lines 1 to 23. |
The Form 720 instructions tell corporations to put the Kentucky Corporation/LLET account number at the top of each form and schedule, and warn that a withholding or sales tax account number, or a Secretary of State organization number, can send the return to another taxpayer’s account. The two dates in marker 5 are what show the 180 consecutive days: someone hired on March 3, 2025 who is still employed at year end has a “through” date of December 31, 2025, while someone who left after four months does not meet the condition and stays off the list.
Lines 25 to 32: the dollar amount and where it goes
Line 25 repeats the count from line 24. Line 26 multiplies it by $100. Lines 27 to 32 are one line per return; use the line for the return you are filing.
| Line | Return | Where the credit goes |
|---|---|---|
| 27 | Form 720 or 720U | Schedule TCS, Part II, Columns E and F |
| 28 | Form PTE | Schedule TCS, Part II, Column E, and Form PTE, Schedule K. General partnerships enter it only on Schedule K |
| 29 | Form 725 | Schedule TCS, Part II, Column E |
| 30 | Form 740 | Schedule ITC, Section A, line 7 |
| 31 | Form 740-NP | Schedule ITC, Section A, line 7 |
| 32 | Form 741 | Form 741, line 18 |
On Schedule TCS (41A720TCS, 10-25) the unemployment credit is Part II, line 3. Column B on that line reads “No,” which under the TCS instructions means the attachment named in Column D, here Schedule UTC, still has to be submitted but needs no preapproval. Column E is the credit taken against the limited liability entity tax (LLET) and Column F the credit taken against corporation income tax. The TCS instructions also cap both: Column E credits cannot bring the LLET below the $175 minimum and Column F credits cannot bring corporation income tax below zero. If the credits are too large, they are reduced starting with the last one listed on the schedule. KRS 141.0205 sets that order of credits, and the UTC instructions say this credit follows it.
Form 741 line 18 is the nonrefundable credits line, and the 741 instructions list the employer’s unemployment credit among the credits figured on Schedule ITC.
Pass-through entities, estates and trusts
For a partnership, LLC or S corporation filing Form PTE, KRS 141.065(7) applies the credit at the entity level against the LLET and then passes it to each partner, member or shareholder according to their pro rata share. The Form PTE instructions list the credit under the code UTC, KRS 141.065, with the note to attach Schedule UTC. Take a restaurant LLC that files Form PTE and hired three people with Office of Employment and Training certificates in 2025: two were still working at year end, one left after about four months. Only the two are listed, line 26 is $200, and line 28 sends that amount to Schedule TCS and Schedule K. KRS 141.065(7) then divides it among the members by their pro rata shares.
For an estate or trust filing Form 741, KRS 141.065(8) splits the credit between the estate or trust and its beneficiaries on the basis of the income allocable to each.
Before you attach Schedule UTC
- Each person listed was certified as unemployed for at least 60 days before being hired, and you have a copy of the certification on file.
- Each person worked at least 180 consecutive days for you during the tax year being claimed.
- Nobody on the list falls under the on-the-job training, relative, dependent or more-than-50%-owner exclusions.
- No one is claimed twice within a group of related corporations or businesses.
- Line 26 is entered on the one line among 27 to 32 that matches your return, and the schedule is attached to that return. The Form 720 instructions say Schedule UTC must be attached to the return claiming the credit.
When the schedule is due and where it is filed
Schedule UTC has no due date or mailing address of its own. It is filed with the return, so it follows that return’s deadline. For Form 720 that is the 15th day of the fourth month after the taxable year closes; Form 720 returns with payment go to the Kentucky Department of Revenue, Frankfort, Kentucky 40620-0021, and returns with no tax due or a refund to Frankfort, Kentucky 40618-0010. Corporations and pass-through entities with federal gross receipts of $1,000,000 or more must e-file Forms 720, 720U, PTE and 725 for tax years beginning on or after October 1, 2021. A corporation that needs more time files Form 720-EXT, which extends the filing date but not the payment date. Individuals, estates and trusts follow the instructions for Form 740, 740-NP or 741.
Two different office names in the 2025 documents
The certificate column on page 1 of Schedule UTC (10-25) and the 2025 Form 720 instructions both name the Office of Employment and Training. The instructions on page 2 of the same Schedule UTC call the certifying office the Office of Development and Training. Both refer to the certificate number you enter in marker 4. If the certificate you hold names a different office, the certification line in the Form 720 instructions is 502-564-7456, and the Department of Revenue’s corporation income and LLET section answers at (502) 564-8139.
Where to get Schedule UTC
The 2025 Schedule UTC PDF is on the Kentucky Department of Revenue forms list. The same list also holds a file named “Schedule UTC 2024”, which is the 2024 schedule (10-24); use the form whose year matches the return. The page 2 instructions are on the PDF itself. This page explains the form and is not tax advice for a particular business.
Questions about Schedule UTC
Do I send the unemployment certification with my return?
The Form 720 instructions say a copy of the certification must be maintained by the taxpayer, and the Schedule ITC instructions say to keep it in your files. What is attached to the return is Schedule UTC.
Can a sole proprietor claim the Kentucky unemployment tax credit?
Schedule UTC lists Forms 740 and 740-NP among the returns it attaches to, and lines 30 and 31 send the credit to Schedule ITC, Section A, line 7. An individual employer uses the same page 1 to list the qualified hires.
Is the $100 credit refundable?
The Form 720, 720U, PTE and 725 instructions call it nonrefundable, and it sits in Part II, Nonrefundable Tax Credits, on Schedule TCS.
Official sources
- Kentucky Department of Revenue, Schedule UTC, Unemployment Tax Credit, 2025, 42A740-UTC (10-25)
- Kentucky Department of Revenue, Instructions for Form 720 (2025)
- Kentucky Department of Revenue, Schedule TCS, Tax Credit Summary Schedule, 41A720TCS (10-25)
- Kentucky Department of Revenue, Schedule ITC, Kentucky Individual Tax Credit Schedule (2025)
- Kentucky Department of Revenue, Instructions for Form PTE (2025)
- Kentucky Department of Revenue, Instructions for Form 741 (2025)
- Kentucky Department of Revenue, Corporation Income and Limited Liability Entity Tax
- Kentucky Department of Revenue, Forms