SA104S, “Partnership (short)”, is the two-page supplement to the SA100 tax return on which a partner reports their own share of a partnership’s trading or professional profit or loss. The 2026 edition, printed HMRC 12/25, covers the tax year 6 April 2025 to 5 April 2026. Most of its figures are copied from the Partnership Statement, the summary in the Partnership Tax Return (SA800) that the nominated partner completes, and the box numbers on SA104S refer back to the boxes on that statement.
Who fills in SA104S, and when the full pages are needed
Question 3 on page TR 2 of the SA100 asks whether you were in a partnership. Answering Yes means filling in a separate Partnership page for each partnership you were a partner in, and giving the number of partnerships in the box next to the question. The SA104S notes add that you need a page for each partnership business as well, so one partnership carrying on two businesses means two pages. Each partner fills in their own pages; the nominated partner also files the SA800 for the partnership as a whole.
HMRC publishes two versions, short (SA104S) and full (SA104F). Two cases in the 2025-26 documents send you to the full pages:
- You have untaxed transition profit from 2023-24. The SA104S form itself says to complete the Partnership (full) page in that case; SA104F has box 16.3 for the spread of transition profit.
- You have foreign partnership income and have claimed to use the foreign income and gains (FIG) regime for 2025-26. The SA150 notes say to use the full pages to report that income and claim the relief.
The full pages also have boxes the short version lacks, among them your share of the partnership’s foreign savings income (boxes 31 to 34 on SA104F), its UK property income (from box 36) and residential property finance costs (box 41.1). The short page has nothing beyond untaxed interest in box 28 for income of that kind.
If you switched between self-employment and partnership between 6 April 2025 and 5 April 2026, the notes tell you to leave boxes 3 and 4 blank and work out the profit or loss from the Partnership Statement together with boxes 9 to 32 of the Self-employment (short) pages or 15 to 76 of the Self-employment (full) pages.
How to fill in SA104S box by box
Page SP 1 holds your name and Unique Taxpayer Reference at the top (needed only on a printed copy; your UTR is on the Partnership Statement), the partnership details and the profit boxes. The markers on the image match the first column below. Boxes 5, 6, 7, 13, 14 and 15 are printed as not in use.
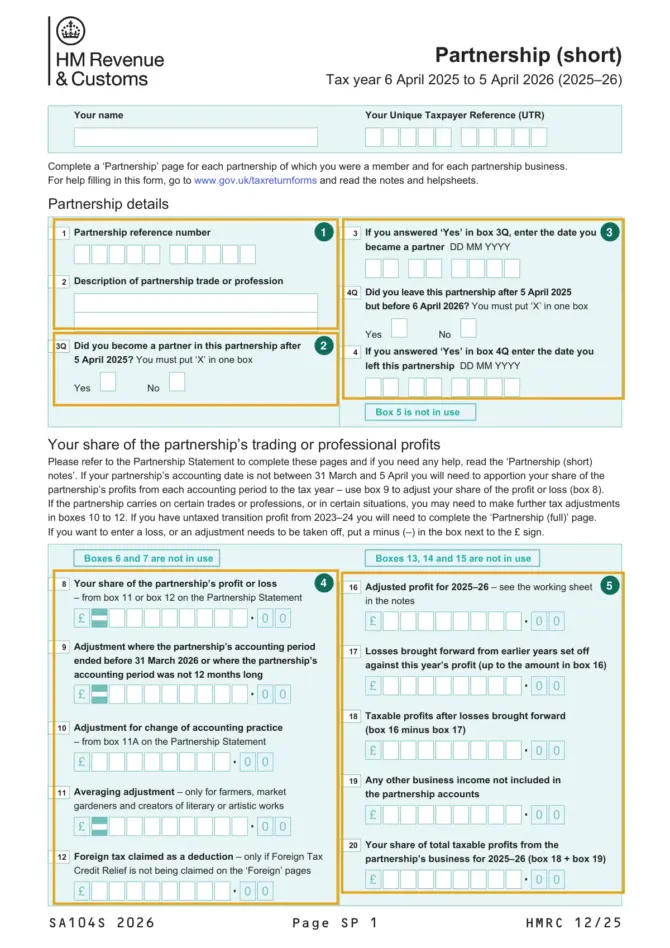
| Marker | Box | What to enter | Where it comes from |
|---|---|---|---|
| 1 | 1, 2 | The partnership’s tax reference number and a description of its trade or profession. A partner in a foreign partnership puts their own UTR in box 1. | Partnership Statement, partnership records |
| 2 | 3Q | X in Yes if you became a partner after 5 April 2025, X in No if before 6 April 2025. | Your joining date |
| 3 | 3, 4Q, 4 | The date you joined (only after a Yes in 3Q), then whether you left between 6 April 2025 and 5 April 2026 and, if so, the date you left. | Your own dates |
| 4 | 8 to 12 | Your share of profit or loss, then four adjustments: accounting period (9), change of accounting practice (10), averaging (11), foreign tax claimed as a deduction (12). | Partnership Statement boxes 11 or 12, and 11A |
| 5 | 16 to 20 | Adjusted profit, losses brought forward, taxable profit, other business income paid to you personally, and your share of total taxable profits. | The working sheet on page SPN 4 of the notes |
Page SP 2 carries the rest:
| Box | What to enter | Where it comes from |
|---|---|---|
| 21 to 24 | Adjusted loss and how you use it: against other 2025-26 income (22), carried back (23), carried forward (24). | Working sheet, your loss claims |
| 25, 26 | X boxes for paying Class 2 NICs voluntarily and for exemption from Class 4 NICs. | Your profits, age and residence |
| 27 | Adjustments that reduce profits chargeable to Class 4 NICs. | Notes and helpsheet HS220 |
| 28 | Your share of the partnership’s untaxed interest. | Partnership Statement box 13 |
| 30 | Your share of Construction Industry Scheme deductions made by contractors. | Partnership Statement box 24 |
| 31 | Your share of other tax taken off trading income. | Partnership Statement box 24A |
| 32 | Any other information. | Free text |
A loss, or an adjustment that has to be taken off, takes a minus sign in the shaded box next to the £ sign.
Joining or leaving has a second step outside the form. The notes say a new partner who is not already registered for Self Assessment and Class 2 NICs as a partner must register now, and a partner who left should tell HMRC as soon as possible so they do not pay too much tax.
Boxes 8 to 12: from the statement to your share for the tax year
Box 8 takes the figure in box 11 or 12 of your Partnership Statement. If you received more than one statement for the same partnership trade for this tax year, the notes say to use the figure from the latest one in box 8 and make the necessary adjustments in box 9.
Box 9 matters when the partnership’s accounting date is not between 31 March and 5 April. Suppose the partnership draws up accounts to 31 December: the 2025-26 tax year then overlaps two of its accounting periods, and your share has to be added together or apportioned to fit 6 April 2025 to 5 April 2026. The notes add that you may need your share for an accounting period for which no Partnership Statement has been prepared yet. HMRC’s helpsheet HS222 covers working out taxable profits, basis periods and overlap relief.
The other three adjustments are narrower:
- Box 10 copies box 11A of the Partnership Statement. An adjustment on leaving the cash basis is spread over 6 tax years, one sixth charged each year, unless you elect to accelerate it.
- Box 11 is only for farmers, market gardeners and creators of literary or artistic works who make an averaging claim; it takes the change the claim makes to your profit (HS224 and HS234).
- Box 12 is foreign tax claimed as a deduction, and only if you are not claiming Foreign Tax Credit Relief on the Foreign pages. You cannot have both (HS263).
The working sheet for boxes 16 to 21
Page SPN 4 of the notes has a lettered working sheet. The order of the steps decides which box a result goes in:
- Start with box 8 (A), add any positive box 9 adjustment (B) and take off any negative box 9 adjustment plus box 12 (D). The result is E.
- If E is a loss or zero, copy it to box 21 as a positive figure, without the minus sign, and put 0 in box 16.
- If E is positive, add box 10 (F) and add or take off the box 11 adjustment (G or H). The result, I, is the adjusted profit for box 16.
- Take off losses brought forward in box 17 (J), which cannot be more than box 16. The result, K, goes in box 18.
- Add box 19 (L), income paid to you rather than to the partnership, such as professional income received in a personal capacity. The total, M, goes in box 20.
Losses: boxes 21 to 24
If you have already made a claim for your 2025-26 loss, the notes ask you to include it in boxes 22 to 24 and give the details in “Any other information” on page TR 7 of the SA100.
- Box 22 sets the loss against your other income for 2025-26. It cannot be more than that other income, and the relief against total income is limited to the greater of £50,000 or 25% of your adjusted total income (HS204). Any balance can go against 2025-26 capital gains, or into boxes 23 and 24. The time limit is 31 January 2028.
- Box 23 carries the loss back: against 2024-25 income (and then 2024-25 gains); against the income of the 3 previous tax years, earliest first, only if the business began after 5 April 2022; or, as terminal loss relief for the final 12 months, against the profits of this business in 2025-26 and the 3 previous years, latest first, only if the business ceased in 2025-26. The amount for each year also goes in “Any other information” on page TR 7. The time limit is 31 January 2028.
- Box 24 is the total to carry forward against future profits of the same business, including unused losses brought forward. The time limit is 5 April 2030.
National Insurance: boxes 25 to 27
The profit threshold on the 2025-26 form is £6,845, measured across all your self-employments and partnerships. Below it you do not have to pay Class 2 NICs but may choose to pay voluntarily to protect your State Pension and certain benefits: put an X in box 25. At £6,845 or more, contributions are treated as paid. Either way you must be registered as a partner. Voluntary Class 2 cannot be paid through Self Assessment after 31 January 2027.
Box 26 takes an X only if you are exempt from Class 4 NICs: you reached State Pension age on or before 6 April 2025, you were under 16 on 6 April 2025, or you were not resident in the UK for tax purposes in 2025-26. Box 27 takes the amount of adjustments that reduce Class 4 profits: changes in accounting practice, losses from earlier years, employment earnings included in your profits, and income disregarded for Class 4 (HS220).
When the 2025-26 pages are due
SA104S has no deadline of its own; it goes in with your SA100. For the 2025-26 tax year:
| What | Deadline |
|---|---|
| Paper return received by HMRC | 11:59pm on 31 October 2026, now passed; a return not yet sent goes online |
| Online return | 11:59pm on 31 January 2027 |
| Online return, if you want the bill collected through your tax code | 11:59pm on 30 December 2026 |
| Paying the tax you owe | 11:59pm on 31 January 2027 |
The SA150 notes move the paper and online filing dates to 3 months after the date on your notice to complete a tax return, if that is later. If you registered for Self Assessment after 5 October 2026, HMRC sends a letter or email with a filing deadline 3 months from its date, but payment is still due by 31 January 2027. The SA150 notes put the penalty for a late return at £100, even if no tax is owed, with further penalties at 3, 6 and 12 months late.
The partnership’s own return has different dates. GOV.UK says that if the partnership’s accounting date is between 1 February and 5 April and one of the partners is a limited company, the partnership return is due 12 months from the accounting date online, or 9 months on paper.
Checks before you send SA104S
- One Partnership page for each partnership and each partnership business, and the number given next to Question 3 on page TR 2.
- Box 8 matches box 11 or 12 of the latest Partnership Statement for that trade.
- If you have untaxed 2023-24 transition profit or a FIG claim, you are on SA104F, not the short pages.
- For a loss, box 16 shows 0 and the loss is in box 21 without a minus sign.
- Box 17 is not more than box 16.
- Boxes 28, 30 and 31 match boxes 13, 24 and 24A on the statement.
- Loss claims made in advance are written up in “Any other information” on page TR 7.
Getting SA104S and where to send it
The 2026 form and its four-page notes are on the GOV.UK SA104S page, which also keeps the 2023, 2024 and 2025 editions and Welsh versions (Partneriaeth (byr)). A paper return, with SA104S enclosed, goes to the address on HMRC’s most recent letter to you; without recent correspondence, the SA100 guidance gives:
| Where you live | Postal address |
|---|---|
| In the UK | Self Assessment, HM Revenue & Customs, BX9 1AS, United Kingdom |
| Outside the UK | HM Revenue & Customs, Benton Park View, Newcastle Upon Tyne, NE98 1ZZ, United Kingdom |
SA104S has no signature box of its own; the SA100 asks you to sign and date the declaration on page TR 8 before sending the return. The SA104S notes give the Self Assessment Helpline, 0300 200 3310, for help with the return.
Official PDF: SA104S — Official PDF (assets.publishing.service.gov.uk)
Questions about SA104S
Where do I find the figures for SA104S?
On the Partnership Statement from the partnership’s SA800 return. Box 8 comes from its box 11 or 12, box 10 from 11A, box 28 from 13, box 30 from 24 and box 31 from 24A.
Do I need SA104S if I was in two partnerships?
You fill in one Partnership page for each partnership, and one for each partnership business, and enter the number of partnerships next to Question 3 on page TR 2.
Can I leave boxes 3 and 4 empty?
Boxes 3Q and 4Q need an X in one box each. Boxes 3 and 4 take a date only after a Yes, and the notes say to leave them blank if you changed between self-employment and partnership during 2025-26.
Sources
- HMRC SA104S 2026, Partnership (short), HMRC 12/25
- HMRC SA104S Notes 2026, Partnership (short) notes, HMRC 12/25
- Self Assessment: Partnership (short) (SA104S), GOV.UK
- HMRC SA104F Notes 2026, Partnership (full) notes
- HMRC SA100 2026, Tax Return
- HMRC SA150 Notes 2026, How to fill in your tax return
- Complete your Self Assessment tax return for the last tax year, GOV.UK
- Self Assessment tax returns: deadlines, GOV.UK