Form 51A105 is the Kentucky Resale Certificate. A business that holds a Kentucky sales and use tax permit fills it out and gives it to a supplier so that goods, digital property or taxable services it will resell, lease, rent or use in manufacturing a product for sale are not charged the 6% sales tax. The Kentucky Department of Revenue’s forms list marks revision 51A105 (1-23) as current. The certificate stays with the seller named on it; the form gives no instructions for sending it to the Department.
Who can issue Form 51A105
The person signing certifies that the business holds a valid Sales and Use Tax Permit and is engaged in selling, leasing or renting, industrial processing or manufacturing. The purchase has to fit one of three uses printed on the form:
- resale in the regular course of business;
- leasing or renting, as provided by Regulation 103 KAR 28:051;
- use in the manufacture or industrial processing of tangible personal property or digital property that will be resold, as provided in KRS 139.470(9).
Besides goods and digital property, the form covers the taxable services listed in KRS 139.200(2)(d) through (ay) when they are bought for resale. Three taxable items are excluded by the asterisk on the form: accommodations, sewer services and admissions, the items in KRS 139.200(2)(a) to (c). A hotel room or event tickets cannot be bought on a 51A105.
Contractors and anyone else registered under a consumer number in the 900,000 series may not issue a resale certificate for any purchase. The Department’s May 30, 2019 notice on sales of taxable services to builders and contractors applies the same rule to services: under 103 KAR 26:070 the contractor is the consumer, so a builder cannot claim the resale exemption on taxable landscaping or janitorial services performed on its construction projects, even when the finished building is later sold.
How to fill out Form 51A105
The certificate is a single page, 6 by 4 inches. The note in its top left corner says it is not valid unless completed, so every blank below needs an entry. The form prints no line numbers; the numbers in the table match the markers on the image.
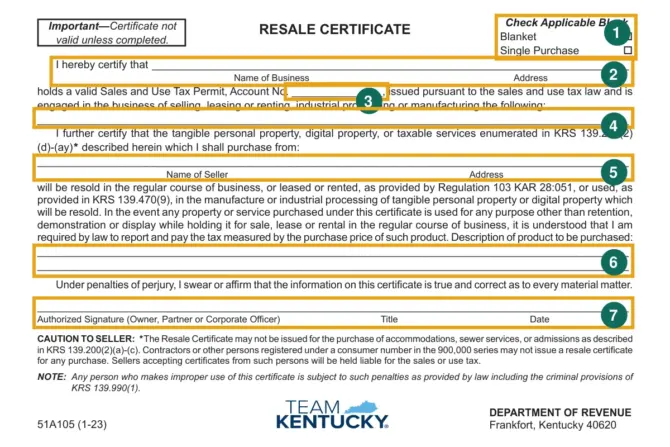
| Marker | Printed label | What to enter |
|---|---|---|
| 1 | Check Applicable Block: Blanket, Single Purchase | Check Blanket or Single Purchase. Form 51A105 does not say how long a blanket certificate stays in effect. |
| 2 | I hereby certify that … Name of Business, Address | The name and address of the buying business that holds the permit. |
| 3 | Sales and Use Tax Permit, Account No. | The buyer’s Kentucky sales and use tax account number. A 900,000 series consumer number cannot be used here. |
| 4 | engaged in the business of … the following | What the business sells, leases, rents, processes or manufactures. |
| 5 | which I shall purchase from: Name of Seller, Address | The supplier receiving the certificate. |
| 6 | Description of product to be purchased | The goods, digital property or services bought for resale, lease, rental or manufacturing. |
| 7 | Authorized Signature (Owner, Partner or Corporate Officer), Title, Date | Signed under penalties of perjury by an owner, partner or corporate officer. |
Markers 4 and 6 work together. A clothing store describes its business as selling apparel at marker 4 and lists the shirts and jackets it buys for its racks at marker 6. Office furniture the store will use itself is not bought for resale, lease, rental or manufacturing, so it does not belong on the certificate.
When the buyer owes the tax instead
By signing, the buyer accepts that if any property or service bought on the certificate is used for anything other than retention, demonstration or display while it is held for sale, lease or rental in the regular course of business, the buyer must report and pay the tax measured by the purchase price. Kentucky’s sales and use tax rate is 6 percent of gross receipts or purchase price, and there are no local sales and use taxes. A store that takes a laptop out of resale stock and uses it at the checkout counter owes the tax on what it paid for that laptop.
The note at the bottom of the form warns that improper use of the certificate is subject to penalties provided by law, including the criminal provisions of KRS 139.990(1).
What makes a resale certificate fail
The form itself lists the situations in which the seller is left with the tax:
- The certificate is incomplete. The form states it is not valid unless completed.
- The buyer is a contractor or holds a 900,000 series consumer number. The caution to seller says sellers accepting certificates from such persons will be held liable for the sales or use tax.
- The purchase is accommodations, sewer services or admissions, which the asterisk excludes from the certificate.
Form 51A105 and the Streamlined certificate, Form 51A260
Kentucky is one of the states listed on the Streamlined Sales Tax certificate, and the Department’s summer 2026 Sales Tax Facts newsletter says the Streamlined Sales Tax Certificate of Exemption, Form 51A260, may be used in place of the Kentucky resale certificate. The 51A260 (12-21) is a multistate form: the buyer checks reason G, Resale, and enters an ID number for each state where the exemption is claimed. Its instructions say a certificate without the single purchase box checked is a blanket certificate that remains in effect until the purchaser cancels it, as long as purchases are no more than 12 months apart, unless a state allows a longer period. Form 51A105 has no such statement.
Other states use their own certificates. Formspedia also covers Nebraska Form 13, the Nebraska resale or exempt sale certificate.
Where to get Form 51A105 and who to ask
Download the Form 51A105 (1-23) PDF from the Kentucky Department of Revenue. A search of the Department’s forms list also returns two older files, 51A105 (7-19) and 51A105 (11-21); the list labels only the 1-23 revision as current. Give the signed certificate to the seller. Questions go to the Division of Sales and Use Tax at (502) 564-5170, fax (502) 564-2041, Station 67, PO Box 181, Frankfort, KY 40602-0181. This page explains the form; it is not tax advice for a particular business.
Questions about the Kentucky resale certificate
Can an out-of-state retailer give a Kentucky supplier Form 51A105?
For a drop shipment where the retailer is out of state and not liable for Kentucky sales and use tax, the summer 2026 Sales Tax Facts newsletter says the retailer should issue Form 51A105 and note on it that it is a nonresident retailer not required to register in Kentucky. The Kentucky customer who receives the goods then owes the 6% use tax directly to the Department if the retailer does not collect it.
Can a contractor use a resale certificate for building materials?
A contractor registered under a 900,000 series consumer number may not issue Form 51A105 for any purchase, and the Department’s 2019 notice treats contractors as the consumer of materials and taxable services used in a construction project.
Do I send Form 51A105 to the Department of Revenue?
The certificate is completed for a named seller and the form gives no address or method for filing it with the Department. Give it to the seller.
Official sources
- Kentucky Department of Revenue, Form 51A105 (1-23), Resale Certificate
- Kentucky Department of Revenue, Sales & Use Tax
- Kentucky Department of Revenue, Sales Tax Facts, Summer 2026
- Kentucky Department of Revenue, Sales of Taxable Services to Builders and Contractors (May 30, 2019)
- Kentucky Department of Revenue, Form 51A260 (12-21), Streamlined Sales Tax Certificate of Exemption
- Kentucky Department of Revenue, Forms