Form 51A126 is the Kentucky Purchase Exemption Certificate. A Kentucky nonprofit educational, charitable or religious institution, or a Kentucky historical site, signs it and hands it to a vendor so that goods, digital property or services it buys are not charged the 6% sales tax, provided they will be used solely within the institution’s exempt function. The Kentucky Department of Revenue’s forms list shows revision 51A126 (12-09) as the current one. The certificate stays with the vendor named on it; the form prints no address for sending it to the Department.
Who can give a vendor Form 51A126
The person signing certifies that the institution named on the form is a Kentucky resident, nonprofit educational, charitable or religious institution, or a Kentucky historical site, located at a Kentucky address. What is bought has to be used solely within the exempt function of that charitable, educational or religious institution or historical site. Kentucky’s sales and use tax is 6 percent of gross receipts or purchase price, and there are no local sales and use taxes in Kentucky.
Three groups are outside the printed statement:
- Agencies, organizations and institutions based in another state. Kentucky has a separate form for them, the Out-of-State Purchase Exemption Certificate, Form 51A127 (12-09), for entities that are exempt from sales and use tax in their state of residence.
- Construction contractors. The caution to seller on Form 51A126 says the certificate cannot be issued or used in any way by a contractor buying property to fulfill a contract with an exempt institution.
- Government units and cemeteries. They may apply for a Purchase Exemption ID on Form 51A125, but the wording of Form 51A126 names only educational, charitable and religious institutions and historical sites. Neither form says which certificate a city, county, special district or cemetery should give a vendor. The letter of authorization the Department mails with an approved ID contains instructions for claiming the exemption; for anything it leaves open, the Division of Sales and Use Tax answers at (502) 564-5170.
Religious institutions got a separate change on August 1, 2026. The Department’s Summer 2026 Sales Tax Facts newsletter explains that KRS 139.495(6) now exempts both their purchases used solely in Kentucky within the religious function and their sales made within that function. Purchases were already exempt before; the new part is the exemption for sales, and after filing their returns for the July reporting period religious institutions no longer have to be registered to report tax on those sales. Buying from a vendor still works the same way, with Form 51A126.
Getting the Purchase Exemption ID on Form 51A125
Before an institution can fill in the first blank of Form 51A126 it needs a number from the Department. The application is Form 51A125 (03-25), Application, Update or Cancellation for Purchase Exemption. The same form is used to apply for the first time, to update information, to cancel an ID or remove a location, and to add a subordinate location to an existing ID. It asks for the legal name, DBA name, FEIN (or, if there is none, the SSN and name of the responsible party), whether the organization holds a sales and use tax account and makes retail sales, a street location address that is not a PO box, the organization type and a contact person, and it is signed in Section E.
Supporting documents depend on the organization type checked on the application:
| Organization type | Documents to attach |
|---|---|
| Charitable, organization or association, educational (public, private school, college or vo-tech) | Articles of incorporation or bylaws, the IRS 501(c)(3) determination letter, and a financial summary with a detailed schedule of receipts and disbursements |
| Religious | Articles of incorporation or bylaws, a financial summary, and either a statement from a local county official (mayor, judge, PVA, sheriff or county clerk) that services are held at the address given, or the IRS 501(c)(3) determination letter |
| Historical site | A letter from the Kentucky Heritage Commission confirming the listing in the National Register |
| Cemetery | A PVA document showing the cemetery is exempt from property tax, articles of incorporation, and a detailed schedule of receipts and disbursements |
| Special district | Articles of incorporation and the registration filed with the county clerk |
| Other state or local funded | An explanation of how the organization is funded, covering all funding |
| Government (city, county, state or federal), Federal Job Corps | Written documentation of the official status of the organization or agency |
The application goes to the Division of Sales and Use Tax, PO Box 181, Station 67, Frankfort, KY 40602-0181, by fax to (502) 564-2041, or by email to DOR.WebResponseSalesTax@ky.gov. If it is approved, the Department mails a letter of authorization containing the Purchase Exemption ID and instructions for claiming the exemption on purchases. The same page adds that an approved organization that makes taxable sales and is not an educational or charitable institution needs a sales and use tax permit for those sales.
How to fill out Form 51A126
The certificate is a single horizontal page with no line numbers; the numbers in the table match the markers on the image. The box in its top left corner says the certificate is not valid unless completed, so every blank needs an entry.
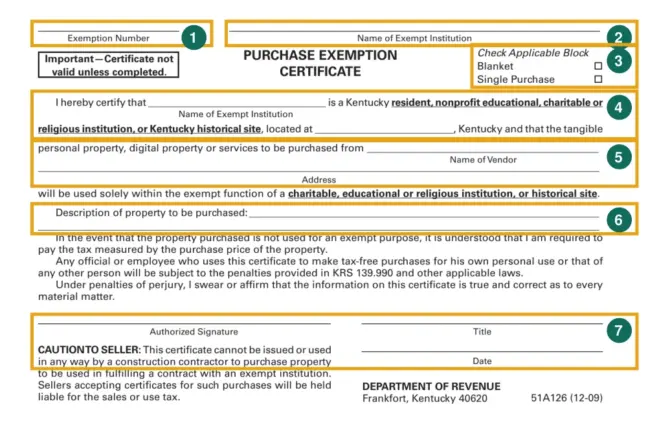
| Marker | Printed label | What to enter |
|---|---|---|
| 1 | Exemption Number | The Purchase Exemption ID from the Department’s letter of authorization. |
| 2 | Name of Exempt Institution | The institution’s name, as approved by the Department. |
| 3 | Check Applicable Block: Blanket, Single Purchase | Check one. The form does not say how long a blanket certificate stays in effect. |
| 4 | I hereby certify that … located at …, Kentucky | The institution’s name again and the Kentucky city or address where it is located. |
| 5 | to be purchased from: Name of Vendor, Address | The vendor receiving the certificate and its address. |
| 6 | Description of property to be purchased | The goods, digital property or services being bought. |
| 7 | Authorized Signature, Title, Date | Signed under penalties of perjury by a person authorized for the institution, with title and date. |
Marker 6 has to describe property used within the exempt function. A private school buying classroom projectors from an electronics supplier can list them there. A television a staff member takes home is not within the school’s educational function and does not belong on the certificate.
When the institution pays the tax after all
By signing, the institution accepts that if property bought on the certificate is not used for an exempt purpose, it must pay the tax measured by the purchase price. Form 51A125 says the same thing from the other side: an approved organization buys without paying tax to the supplier, but purchases of anything not used within its exempt function are taxable.
A second warning on the certificate is aimed at individuals. Any official or employee who uses Form 51A126 to make tax-free purchases for personal use, or for another person, is subject to the penalties in KRS 139.990 and other applicable laws.
Problems the form itself warns about
The certificate names three situations in which it does not work:
- A blank left empty. The certificate is not valid unless completed.
- A contractor’s purchase. Sellers that accept Form 51A126 for property a construction contractor will use on a contract with an exempt institution are held liable for the sales or use tax.
- An institution from another state. Form 51A126 certifies Kentucky residence; out-of-state exempt entities use Form 51A127.
Form 51A126, Form 51A127 and Form 51A383
Form 51A127 (12-09), the Out-of-State Purchase Exemption Certificate, has the same blanket or single purchase choice, a vendor block and a property description, plus a blank for an exemption or ID number. Its caution to seller says it covers only entities exempt as a whole in their state of residence, not specific types of property that state exempts, and that sellers may not accept it in place of a resale certificate, a multijurisdictional certificate or a direct pay authorization.
Contractors have one narrow route of their own. Form 51A383 (4-23), issued under KRS 139.480(34), covers building materials, fixtures and supplies bought on or after January 1, 2023 for a construction contract with a governmental agency to furnish water or sewer services to the public. The agency and the contractor execute it jointly, and it is valid only for the project period entered on it.
Other states run their own certificates. Formspedia also covers Nebraska Form 13, which Nebraska uses for both resale and exempt purchases.
Where to get Form 51A126 and who to ask
Download the Form 51A126 (12-09) PDF from the Kentucky Department of Revenue. A search of the Department’s forms list for 51A126 returns this single file, labeled Current. Give the completed and signed certificate to the vendor. The application, Form 51A125 (03-25), is on the same list. Questions go to the Division of Sales and Use Tax at (502) 564-5170, fax (502) 564-2041. This page explains the form; it is not tax advice for a particular organization.
Questions about the Kentucky purchase exemption certificate
Do I send Form 51A126 to the Department of Revenue?
The certificate is made out to a named vendor, and the form gives no address or method for filing it with the Department. Give it to the vendor.
Can a church use Form 51A126 without a Purchase Exemption ID?
The first blank on the certificate is the exemption number, and the form is not valid unless completed. Form 51A125 is the application for that ID; religious institutions apply with bylaws, a financial summary and a county official’s statement or a 501(c)(3) letter.
Can a city or county government use Form 51A126?
Governments are listed as applicants on Form 51A125, but Form 51A126 certifies only educational, charitable or religious institutions and historical sites. Follow the instructions in the Department’s letter of authorization, or ask the Division of Sales and Use Tax at (502) 564-5170.
Which certificate does an out-of-state charity give a Kentucky vendor?
Form 51A127, the Out-of-State Purchase Exemption Certificate, is for agencies, organizations and institutions exempt from sales and use tax in their own state. Form 51A125 also asks out-of-state organizations for proof of that home-state exemption.
Official sources
- Kentucky Department of Revenue, Form 51A126 (12-09), Purchase Exemption Certificate
- Kentucky Department of Revenue, Form 51A125 (03-25), Application, Update or Cancellation for Purchase Exemption
- Kentucky Department of Revenue, Form 51A127 (12-09), Out-of-State Purchase Exemption Certificate
- Kentucky Department of Revenue, Form 51A383 (4-23), Certificate of Exemption for Building Materials, Fixtures and Supplies Purchased by a Construction Contractor for a Sewer or Water Project With a Governmental Agency
- Kentucky Department of Revenue, Sales Tax Facts, Summer 2026
- Kentucky Department of Revenue, Sales & Use Tax
- Kentucky Department of Revenue, Forms