Alabama Schedule OZ, “Gains Invested in Qualified Opportunity Zone Funds”, is a two-page list of capital gains that a business deferred on its federal return by putting them into an Opportunity Zone fund. The schedule sorts each gain into one Alabama column or the other: still deferred, or taxable for Alabama. Only the taxable total moves to the return. The Alabama Department of Revenue publishes the same PDF for 2025 tax periods on two form pages, one marked Form Year 2025 for Forms 20C, 20S and 65, and one marked Form Year 2026 for Form ET-1.
Who attaches Schedule OZ, and to which return
The header of the schedule names four returns: Form 20C (C corporations), Form ET-1 (financial institution excise tax), Form 20S (S corporations) and Form 65 (partnerships). The Form 20S and Form 65 instructions state the rule plainly: Schedule OZ must be completed if a taxpayer has gains invested in Qualified Opportunity Funds. Schedule FTI, which 20C and ET-1 filers use to reconcile federal taxable income, repeats it in capitals next to its list of adjustments: the Schedule OZ MUST be completed.
The Alabama rule behind the schedule comes from Act 2019-392, which created Section 40-18-6.1 of the Code of Alabama. According to the 20S and 65 instructions, it applies the federal deferral in 26 U.S.C. Section 1400Z-2 to an investment in an opportunity fund approved by ADECA, the Alabama Department of Economic and Community Affairs. If the project does not meet the qualifications of an approved fund, the deferred gain is added back to arrive at Alabama taxable income.
Two neighboring lines on the 20S and 65 both trace back to Act 2019-392. Line 7b on Form 20S (8b on Form 65) is the Opportunity Zone line fed by Schedule OZ. Line 7c (8c) is a separate exclusion under Section 40-18-8.1 for gain of a qualified investment fund that sells its interest in a qualified entity, the line labeled “Tech Company”. Schedule OZ has nothing to do with line 7c or 8c.
Form 40, the individual income tax return, is not among the returns printed in the Schedule OZ header.
How to fill out Schedule OZ, column by column
The top band (N in the image) asks for the name or names shown on the return, the FEIN, and the tax period beginning and ending dates, each with a “20__” year blank. Below it, page 1 has 30 rows for gains and page 2 has 30 more, numbered 31 to 60 in the fillable PDF. One row is one gain. Letters a to h in the image match the column letters printed on the form.
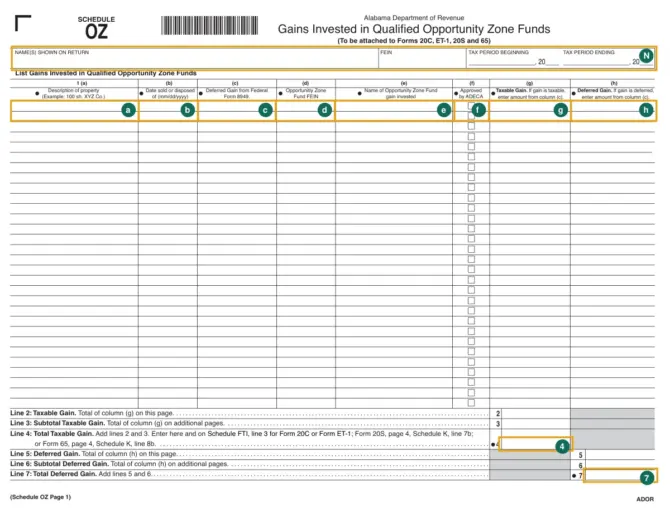
| Column | Printed label | What goes in it |
|---|---|---|
| (a) | Description of property | What was sold, in the form’s own example style: “100 sh. XYZ Co.” |
| (b) | Date sold or disposed of | The sale date, written mm/dd/yyyy. |
| (c) | Deferred gain from federal Form 8949 | The gain deferred on the federal return. This is the amount that later goes into column (g) or (h). |
| (d) | Opportunity Zone fund FEIN | The federal employer identification number of the fund that received the gain. |
| (e) | Name of Opportunity Zone fund gain invested | The fund’s name. |
| (f) | Approved by ADECA | A checkbox, one per row. |
| (g) | Taxable gain | “If gain is taxable, enter amount from column (c).” |
| (h) | Deferred gain | “If gain is deferred, enter amount from column (c).” |
Each row’s column (c) amount goes into one of (g) or (h). The form does not spell out the test, but read together with the 20S and 65 instructions, the checkbox in (f) decides which one: a gain invested in an ADECA-approved fund keeps its deferral and goes in (h), and a gain in a fund that does not meet those qualifications is added back for Alabama and goes in (g).
The schedule and its instructions stop short of one thing a preparer needs before ticking (f): how to confirm that a particular fund is approved by ADECA. The Revenue Department’s two form pages carry no guidance, and ADECA’s Opportunity Zones page describes the zones and the 2026 Opportunity Zones 2.0 nominations but says it does not certify or verify that a property lies within an Opportunity Zone. The 20C instructions send questions about preparing Form 20C to the Corporate Income Tax Section at 334-242-1170, option 6.
Totals on lines 2 to 7 and where line 4 goes
The totals sit at the bottom of page 1. Page 2 has a “Page __ of __” box and a single line for the totals of columns (g) and (h) on that page; those page totals are what lines 3 and 6 bring back to page 1.
| Line | Label | Amount |
|---|---|---|
| 2 | Taxable gain | Total of column (g) on page 1 |
| 3 | Subtotal taxable gain | Total of column (g) on additional pages |
| 4 | Total taxable gain | Line 2 plus line 3; this is the amount carried to the return |
| 5 | Deferred gain | Total of column (h) on page 1 |
| 6 | Subtotal deferred gain | Total of column (h) on additional pages |
| 7 | Total deferred gain | Line 5 plus line 6 |
Line 4 tells you where its amount goes, and the target depends on the return:
| Return | Where the line 4 amount goes |
|---|---|
| Form 20C or Form ET-1 | Schedule FTI, line 3, as one of the adjustment items listed there (3a to 3j) |
| Form 20S | Page 4, Schedule K, line 7b, “Opportunity Zone Investment (from Schedule OZ, line 4)” |
| Form 65 | Page 4, Schedule K, line 8b, with the same label |
On Schedule FTI, line 3 is where differences between federal taxable income on the federal Form 1120 (or the proforma 1120) and line 1 of Form 20C or ET-1 are listed, and the schedule names “taxable gains from the Schedule OZ” as one example. The earlier Schedule OZ, posted for Form Year 2024, sent line 4 to Schedule FTI line 4; the 2025 PDF says line 3. On Form 20S, line 7d adds lines 7a, 7b and 7c; on Form 65, line 8d adds lines 8a, 8b and 8c.
Line 7, the total still deferred, has no carry instruction. It stays on the schedule as the record of what Alabama continues to defer.
When Schedule OZ is due
The schedule has no due date and no signature line of its own. It is filed with the return it supports, so that return’s date applies:
- Form 20C and Form ET-1 for 2025 periods: one month after the due date of the corresponding federal return, including extensions. The tax itself is due by the original due date, without the extra month granted by Act 2022-53.
- Form 20S: the 15th day of the 3rd month after the end of the tax year.
- Form 65: March 15 for a calendar year, or the 15th day of the third month after a fiscal year closes, moved to Monday when the 15th is a weekend day.
Where to get the Schedule OZ PDF and where it is mailed
The Schedule OZ PDF (file 25schoz.pdf) is fillable and is linked from both Revenue Department form pages: “Gains Invested in Qualified Opportunity Zone Funds for 20C, 20S and 65” (Form Year 2025) and the ET-1 version (Form Year 2026, which the ET-1 instructions use for 2025 periods). There is no separate instruction booklet for Schedule OZ; the column labels, the line 4 routing and the return instructions quoted above are all the guidance published.
Mailed returns go with the schedule attached, to the address for the return:
| Return | Address in the 2025 instructions |
|---|---|
| Form 20C with payment | Corporate Tax Section, P.O. Box 327435, Montgomery, AL 36132-7435 |
| Form 20C without payment or with a refund | Corporate Tax Section, P.O. Box 327430, Montgomery, AL 36132-7430 |
| Form ET-1 with payment | Financial Institution Excise Tax, P.O. Box 327439, Montgomery, AL 36132-7439 |
| Form 20S with payment | Pass Through Entity, P.O. Box 327444, Montgomery, AL 36132-7444 |
| Form 20S without payment, and Form 65 | Pass Through Entity, P.O. Box 327441, Montgomery, AL 36132-7441 |
Corporate payments of $750 or more must be made electronically. A smaller 20C payment by check travels with Form BIT-V, placed loose in the envelope and not stapled to the return.
Questions about Alabama Schedule OZ
Does a deferred gain in an ADECA-approved fund still need a row on Schedule OZ?
The 20S and 65 instructions require the schedule whenever gains are invested in Qualified Opportunity Funds, and the form has column (h) and lines 5 to 7 for gains that stay deferred. Only line 4, the taxable total, moves to the return.
Is the Schedule OZ for Form ET-1 a different form?
The ET-1 form page and the 20C, 20S and 65 form page link to the same file, 25schoz.pdf, and its header lists all four returns.
Which Schedule FTI line takes the Schedule OZ amount on Form 20C?
Line 3, the list of adjustment items, according to the 2025 Schedule OZ. The Form Year 2024 version pointed to line 4.
Official sources
- Alabama Department of Revenue, Schedule OZ, Gains Invested in Qualified Opportunity Zone Funds (25schoz.pdf)
- Alabama Department of Revenue, Gains Invested in Qualified Opportunity Zone Funds for 20C, 20S and 65, Form Year 2025
- Alabama Department of Revenue, Gains Invested in Qualified Opportunity Zone Funds for ET-1, Form Year 2026
- Alabama Department of Revenue, Schedule OZ, Form Year 2024 (24schoz.pdf)
- Alabama Department of Revenue, Schedule FTI, Schedule of Adjustments to Federal Taxable Income
- Alabama Department of Revenue, Form 20C instructions, 2025
- Alabama Department of Revenue, Form 20S instructions, 2025
- Alabama Department of Revenue, Form 65 instructions, 2025
- Alabama Department of Revenue, Form ET-1 instructions, 2026 form for 2025 periods
- Alabama Department of Revenue, Form 20S, 2025 and Form 65, 2025
- Alabama Department of Economic and Community Affairs, Opportunity Zones Program