The buyer sends Alabama property-sale withholding on WNR-V, but the voucher identifies the seller. The July 2025 revision credits the remittance to the seller’s Alabama income tax account as an estimated payment. Use this revision’s address for the voucher and payment.
Who prepares WNR-V and how much is remitted?
Prepare a separate voucher for each seller or transferor required to file an Alabama income tax return. Form WNR determines the amount of withholding, capped at the seller’s net proceeds. Transfer its line 13 amount to WNR-V’s Amount Paid field.
If taxable gain is used to calculate withholding, attach the seller’s NR-AF2 affidavit to Form WNR. The buyer may rely on the affidavit unless they know or should know at closing that its statements are false; the instructions impose no separate duty to investigate it. Form WNR’s calculation and the applicable exemption rules must be resolved before completing this remittance voucher. The official nonresident withholding page links the calculation form, residence affidavit and exemption certificate.
How to complete every WNR-V voucher field
All taxpayer details on the voucher belong to the seller or transferor. In the illustration, frame 1 marks the seller’s tax-period end, frame 2 the identification numbers and frame 3 the payment amount.
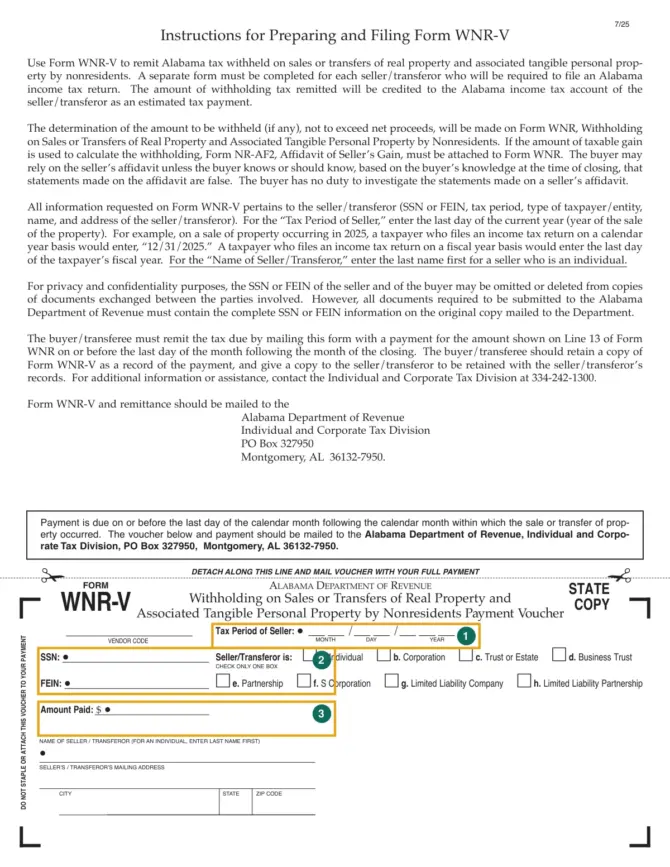
| Field | What to enter | Source |
|---|---|---|
| Tax period of seller | Last day of the seller’s tax year for the sale | Use the calendar-year end for a calendar filer, or the fiscal-year end for a fiscal filer |
| SSN or FEIN | The seller’s complete identification number in the appropriate field | Seller’s tax identification record |
| Seller/transferor type | One entity-type box | Individual, corporation, trust/estate, business trust, partnership, S corporation, LLC or LLP |
| Amount paid | Withholding being remitted | Form WNR, line 13 |
| Name of seller/transferor | The seller’s name; last name first for an individual | Seller’s identification details |
| Mailing address, city, state and ZIP | The seller’s correspondence address | Seller’s mailing record |
For a sale during 2026 by a calendar-year seller, the tax-period field is 12/31/2026, even if closing occurred earlier. A fiscal-year seller uses the final day of the relevant fiscal year. The tax-period field is not the closing date.
Party-to-party copies can omit SSNs or FEINs for confidentiality. Originals submitted to ALDOR must contain complete identification numbers. Keep the state submission distinct from copies supplied to the other party.
Payment deadline and July 2025 mailing address
The buyer must send the voucher and full payment by the last day of the month following the month of sale or transfer. For example, a closing in October leads to a November month-end deadline under that rule.
Mail WNR-V and its remittance to Alabama Department of Revenue, Individual and Corporate Tax Division, P.O. Box 327950, Montgomery, AL 36132-7950. This is the address printed twice on the July 2025 voucher.
Form WNR is a separate transaction report. Its September 2025 instructions direct the original report to the Withholding Tax Section, P.O. Box 327480, Montgomery, AL 36132-7480. Follow each form’s own submission instructions: the WNR-V payment goes to Box 327950, while the original WNR report follows the report’s address.
Official PDF: Form WNR-V — Official PDF (revenue.alabama.gov)
Print the barcode and keep the seller’s credit records
Download the PDF and open it in Adobe Reader or Acrobat as instructed in the form. Enter the information electronically and use its green Print button, which generates the two-dimensional barcode. The PDF warns that ordinary File > Print can produce a blank page. Do not handwrite the data.
Detach the voucher at the marked line and mail it with full payment. Do not staple or attach the voucher to the payment. The buyer keeps a copy and gives the seller a copy of WNR-V.
The separate WNR report has its own copy requirements: the buyer retains one copy and gives two to the seller. The seller attaches one WNR copy to the Alabama return to claim the payment credit and keeps the other. If the tax type, gain calculation or an exemption is uncertain, resolve it with the closing professional or ALDOR before remitting.