Form NR-AF2 lets a nonresident seller document the gain on an Alabama real estate sale so that withholding can be calculated using that gain. The seller supplies the figures and gives the sworn affidavit to the buyer. Its seven-line calculation separates taxable gain from the net proceeds received at closing.
When does a seller use NR-AF2?
Use the affidavit when a nonresident seller wants withholding under Section 40-18-86 calculated on the recognized gain from a property sale. Alabama’s guidance otherwise describes withholding based on the purchase price. The seller is responsible for calculating the gain; the buyer may rely on the affidavit unless the buyer knows or should know, from information available at closing, that it is false.
The official PDF is revision 9/25. It asks for the seller’s name, SSN or FEIN and address, plus the spouse’s name and identification number if the property is jointly owned. The signature area includes separate seller and spouse lines, dates, titles where applicable, and a notary acknowledgment.
Filling out lines 1 through 7
Have the sale figures, basis records, depreciation history and selling-expense records available before completing the schedule. The highlighted lines 4, 6 and 7 show where adjusted basis, taxable gain and net proceeds are entered. The numbers in the illustration match the official line numbers.
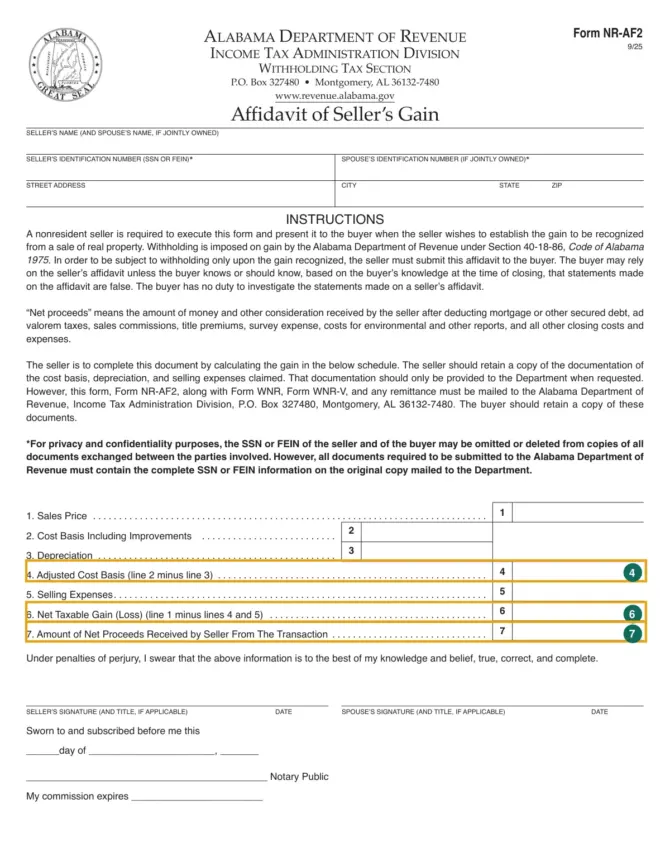
| Line | Entry | Source or calculation |
|---|---|---|
| 1: Sales price | The property’s sale price. | Sale agreement and closing records. |
| 2: Cost basis including improvements | The basis amount before the depreciation adjustment on line 3. | Acquisition and improvement records. |
| 3: Depreciation | The depreciation used in the adjusted-basis calculation. | Depreciation records for the property. |
| 4: Adjusted cost basis | Subtract line 3 from line 2. | The two preceding entries. |
| 5: Selling expenses | The selling expenses claimed in calculating the gain. | Closing statement and expense documentation. |
| 6: Net taxable gain or loss | Subtract lines 4 and 5 from line 1. | The sales price less adjusted basis and selling expenses. |
| 7: Net proceeds received | The proceeds remaining after the deductions described in the instructions. | Closing records, including secured-debt payoff and closing costs. |
For example, a nonresident selling an Alabama rental property will need the property’s depreciation records for line 3. A mortgage payoff belongs in the net-proceeds analysis described by the form; the line 6 formula subtracts adjusted basis and selling expenses from the sale price. Using the cash received at closing as the taxable-gain figure would skip that calculation.
The form defines net proceeds as money and other consideration received after deducting mortgage or other secured debt, ad valorem taxes, sales commissions, title premiums, survey expense, environmental and other report costs, and other closing costs and expenses. ALDOR’s accompanying guidance says that when calculated withholding exceeds the cash received at closing, the buyer withholds and remits only the net proceeds otherwise payable to the seller.
NR-AF2 records the calculation but does not explain every basis or depreciation issue. For an inherited property, a disputed basis or a complex ownership arrangement, obtain tax advice before swearing to the amounts. This article is a form-filling explanation, not a determination of the gain on your sale.
Where to get the PDF and send the affidavit
Download the official NR-AF2 affidavit from ALDOR. Present the completed affidavit to the buyer for the gain-based withholding calculation. The form directs that NR-AF2, Form WNR, Form WNR-V and any remittance be mailed to Alabama Department of Revenue, Income Tax Administration Division, P.O. Box 327480, Montgomery, AL 36132-7480.
The buyer retains copies of those documents. Keep an explanation of cost basis and expenses in the closing file, as the agency’s withholding page directs. The seller also keeps the supporting basis, depreciation and selling-expense documentation; NR-AF2 says to provide that documentation to ALDOR only when requested. This distinguishes the affidavit that is mailed from the underlying records kept for a possible request.
Complete identification numbers must appear on originals submitted to ALDOR. SSNs or FEINs may be omitted or deleted from copies exchanged among the parties. NR-AF2 itself prints no separate payment deadline; consult the applicable WNR-V instructions for the remittance timetable.