An Alabama property buyer may ask the seller for Form NR-AF1 to document why nonresident withholding does not apply. Where the seller actually resides determines both which statements to initial and whether the affidavit stays with the buyer or goes to the Alabama Department of Revenue.
Who needs the seller’s residence affidavit?
Alabama residents are outside the withholding provisions of Section 40-18-86 and are not required to complete NR-AF1. A buyer can nevertheless request it as evidence of residency for the transaction file. The form’s September 2025 revision covers individuals and business entities domiciled in Alabama; an entity qualifies as domiciled there if it is organized under Alabama law or has its principal place of business in Alabama.
A nonresident may qualify as a “deemed resident” for this withholding rule, but the detailed declarations impose several conditions together. Owning an Alabama property alone does not satisfy the declaration. For a seller who lives elsewhere and is selling an Alabama rental property, the remaining-property test, prior returns and current-year filing commitment all need attention before signing.
How to complete the residency declarations
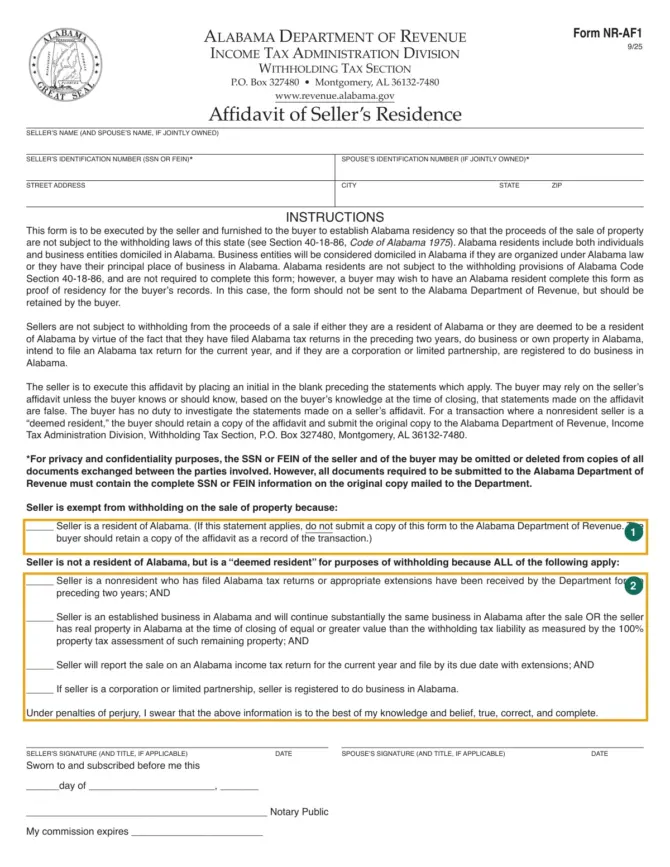
Enter the seller’s name, identification number and address at the top. Joint ownership with a spouse calls for the spouse’s name and identification number too. In the illustration, marker 1 identifies the Alabama-resident statement and marker 2 groups the deemed-resident conditions. These two markers are editorial labels, not numbers printed on the official form.
| Form section | What to enter or confirm | Records to consult |
|---|---|---|
| Seller identification | Name, SSN or FEIN, mailing address and spouse’s details for joint ownership. | Seller’s identification and ownership records. |
| Resident statement, marker 1 | Initial the statement if the seller is an Alabama resident. | Residence information; for an entity, organization or principal-place-of-business records. |
| Prior filings, marker 2 | Confirm Alabama returns were filed, or appropriate extensions were received by the Department, for the preceding two years. | Those returns or extension records. |
| Continuing business or remaining property, marker 2 | Confirm substantially the same established Alabama business will continue after the sale, or that qualifying Alabama real property remains at closing. | Business records or the remaining property’s 100% property tax assessment. |
| Current-year return and entity registration, marker 2 | Commit to reporting the sale on the current-year Alabama return by its due date with extensions. A corporation or limited partnership must also be registered to do business in Alabama. | Filing plans and applicable registration records. |
| Signatures and notary block | Seller and, for joint ownership, spouse sign and date; include a title where applicable. Complete the sworn statement before a notary. | The completed affidavit and notarial acknowledgment. |
The remaining-property alternative has a specific threshold: the Alabama real property held at closing must have a value at least equal to the withholding tax liability, measured by its 100% property tax assessment. The introductory instructions summarize the rule; the statements that the seller initials provide this more precise test.
The seller initials each applicable statement. For deemed-resident status, the form connects the conditions with “AND”; the business-continuation and remaining-property alternatives sit within one of those conditions. If the facts do not support that declaration, ask the closing professional or a tax adviser to determine the applicable withholding treatment. This guide does not determine your residency or tax liability.
Download NR-AF1 and give it to the correct recipient
The official NR-AF1 PDF prints revision 9/25 in its upper corner. Complete it for the buyer’s use in the property transaction. For an actual Alabama resident, the buyer retains the affidavit; the form explicitly says not to send it to ALDOR.
For a nonresident claiming deemed-resident treatment, the buyer keeps a copy and sends the original to Alabama Department of Revenue, Income Tax Administration Division, Withholding Tax Section, P.O. Box 327480, Montgomery, AL 36132-7480. NR-AF1 itself does not state a separate calendar filing deadline.
Identification numbers may be omitted or removed from copies exchanged among the parties. The original sent to ALDOR must contain complete SSN or FEIN information. The buyer may rely on the affidavit unless the buyer knows or should know at closing that its statements are false; the form does not impose a duty to investigate.