Form PIT-EXT, the Application for Automatic Extension of Time to File Delaware Individual Income Tax Return, moves the filing date of a 2025 Delaware personal income tax return from April 30, 2026 to October 15, 2026. It moves nothing else. Any tax you expect to owe is still due on April 30, and the six-line worksheet on the form exists so you can work out that amount and send it with the request. This guide follows the 2025 form, Revision 20250516.
Who files PIT-EXT and what it does not extend
The request belongs to individuals who must file a 2025 Delaware return: full-year residents on Form PIT-RES, nonresidents with Delaware-source income on Form PIT-NON, and part-year residents, who may pick either return. Both sets of 2025 instructions use the same rule. The extension is granted when PIT-EXT is filed before the return’s due date, and both put a warning in capitals above it: there is no extension of time for payment of tax.
Delaware does not accept blanket requests. Each return needs its own PIT-EXT. A married couple filing one joint return completes one page with both names and both signatures; spouses who file separate returns, which the instructions say go in separate envelopes, send one request each.
The 2025 page prints “Taxable Year 2025” and “Must be filed by April 30, 2026” as fixed text, with no box for a fiscal year. The instructions give non-calendar-year filers a return due date of the last day of the fourth month after their year ends, but neither they nor the form explain how such a filer marks the period on PIT-EXT. If your year is not the calendar year, ask the Division of Revenue at (302) 577-8208 before you rely on this page.
How to fill out PIT-EXT, line by line
Do the arithmetic before you touch the form. Lines 1 to 6 are a short version of the payments section of your 2025 return, so a draft of PIT-RES or PIT-NON, even an unfinished one, gives you most of the numbers. The labels on lines 2 and 3 match return lines word for word; lines 1 and 4 have no instruction of their own, so the table shows where the return keeps the comparable figure.
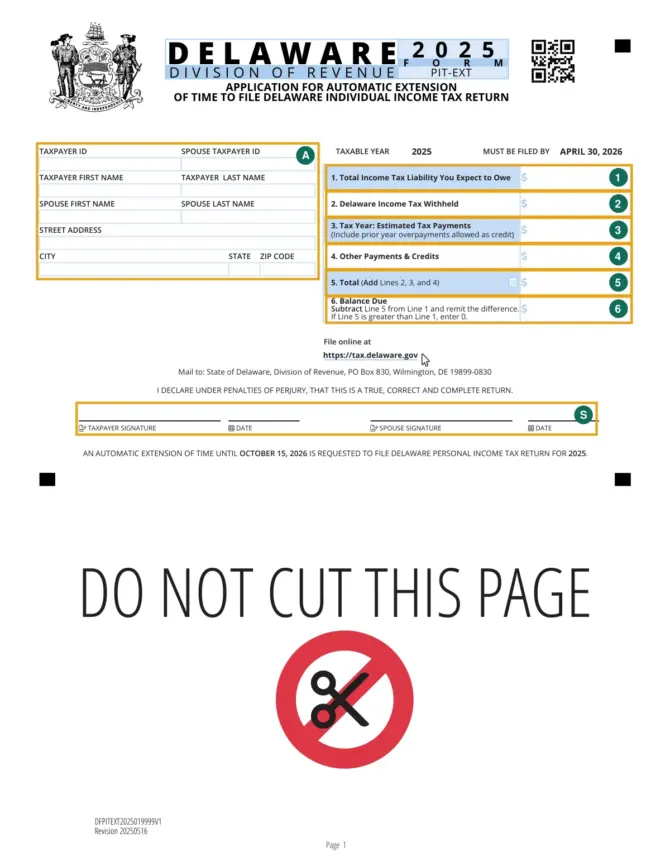
| Field | What goes in it | Comparable 2025 return line |
|---|---|---|
| A: identity block | Taxpayer ID, spouse taxpayer ID, both first and last names, street, city, state, ZIP | Name and address section of PIT-RES or PIT-NON |
| Line 1 | Total income tax liability you expect to owe for 2025 | PIT-RES line 33 or PIT-NON line 48, labeled “Balance” (tax after non-refundable credits) |
| Line 2 | Delaware income tax withheld, from W-2 and 1099-R forms | PIT-RES line 35, PIT-NON line 49 |
| Line 3 | 2025 estimated tax payments, plus any 2024 overpayment you applied as a credit | PIT-RES line 36, PIT-NON line 50 |
| Line 4 | Other payments and credits | PIT-RES lines 34 and 37 to 39, PIT-NON lines 51 to 53 (see below) |
| Line 5 | Lines 2, 3 and 4 added together | None; the form calculates it |
| Line 6 | Line 1 minus line 5, or 0 if line 5 is larger; this is the amount you pay | Plays the role of PIT-RES line 41 or PIT-NON line 55 |
| S: signatures | Taxpayer signature and date; spouse signature and date on a joint request | None |
Line 2 takes the same restrictions as the return’s withholding line. The PIT-RES instructions for line 35 exclude city wage tax withholding, S corporation payments and REW-EST capital gains tax payments; those either do not count at all or belong elsewhere. On line 3, a fourth-quarter 2025 estimated payment counts only if it was made by January 16, 2026, the date the instructions set for credit on the return.
Line 4 is the one line with a real gap. On the resident return, the items that reduce line 33 besides withholding and estimated payments are the refundable earned income tax credit (line 34), S corporation payments (line 37), refundable business credits (line 38) and REW-EST real estate capital gains payments (line 39). PIT-NON lists S corporation payments, refundable business credits and capital gains payments on lines 51 to 53. The PIT-EXT has one undivided line for all of these and no instruction naming them. If you are unsure whether a particular credit belongs there, call the Division before you send the request.
A worked example with invented figures: a resident expects $4,180 of tax on line 1, had $3,050 withheld (line 2) and made $600 of estimated payments (line 3), with nothing on line 4. Line 5 is $3,650 and line 6 is $530, the amount that goes with the request. If line 5 had come to $4,300, line 6 would be 0 and the form would still have to be filed to get the extra time.
The signature line sits under a printed declaration, made under penalties of perjury, that the form is true, correct and complete. The extension sentence at the bottom is also preprinted: it asks for time until October 15, 2026 for the 2025 personal income tax return, so you do not write any dates there.
Deadlines, interest and penalties
For a calendar-year 2025 return, the request and any payment had to reach the Division of Revenue by April 30, 2026, and the extended return was due October 15, 2026. At this review on November 1, 2026 both dates have passed, and the forms page still lists the 2025 version of PIT-EXT. A request mailed now does not make an unfiled 2025 return timely; file the return itself and expect the penalties below.
| Charge | Rate in the 2025 instructions | When it applies |
|---|---|---|
| Interest | ½% per month or fraction of a month | On tax unpaid after the original due date, even with a valid extension |
| Failure to pay | 1% per month of the net tax liability, up to 25% | Tax not paid on a timely or late-filed return; added to interest |
| Late filing | 5% per month of the balance due | A balance-due return filed after its due date |
Taking the example above, if the $530 had gone out with the return on October 15 instead of with the extension, interest would run from April 30. Five and a half months count as six under the fraction-of-a-month rule, so interest alone would be 3%, or $15.90, before any failure-to-pay penalty. You may leave the penalties and interest line on the return blank (PIT-RES line 45, PIT-NON line 59); the Division then calculates the amount and sends a bill.
Paying the line 6 amount online or by check
PIT-EXT can be filed on the Delaware Taxpayer Portal at tax.delaware.gov. When an online request has a balance, the instructions allow a direct debit from a checking or savings account or a credit card. A direct debit can be dated later, up to the due date, must come from a U.S. account and has no dollar limit; a credit card payment is limited to $10,000.
The paper form does not say whom to make a check payable to. The PIT-NON instructions use “Delaware Division of Revenue” for balance-due payments, and the PIT-RES instructions write “DE Division of Revenue”. For help with a payment, the Payment page lists (302) 577-8785, and the return instructions list 1-302-577-8208 for New Castle County and callers outside Delaware and 1-800-292-7826 for Kent and Sussex County, 8:00 a.m. to 4:15 p.m., Monday through Friday.
When you file the return, report the extension payment where the return lines are labeled “Estimated tax paid & payments with extensions”: PIT-RES line 36 or PIT-NON line 50. The PIT-RES line 36 instruction text itself only mentions quarterly payments and Form PIT-EST, so the line label is the only place the return names extension payments. Withholding already entered on PIT-EXT line 2 goes on the withholding line, not here.
Getting the 2025 form and mailing it
The fillable PDF is on the Division of Revenue’s Personal Income Tax Forms page, listed as “Extension Request Voucher (PIT-EXT) – Do Not Cut Form!”. The page advises downloading a PDF before you fill it in. The form has a Prepare For Print button, and most of the page below the signature line carries a large “Do not cut this page” notice, so the whole sheet goes in the envelope.
Mail it, with the payment if line 6 is more than zero, to:
State of Delaware, Division of Revenue
PO Box 830
Wilmington, DE 19899-0830
The same PO Box 830 receives the PIT-VCH payment voucher for e-filed returns, while a paper PIT-RES or PIT-NON goes to PO Box 508 with a payment, PO Box 8710 with a refund due and PO Box 8711 when it is a zero-due return or has no payment enclosed. Do not send the extension to those return addresses.
Official PDF: Form PIT-EXT — Official PDF (revenuefiles.delaware.gov)
Other Delaware forms around PIT-EXT
- PIT-RES and PIT-NON: the 2025 resident and nonresident returns that the extension covers.
- PIT-VCH: the voucher for paying the balance on a return you have already e-filed.
- PIT-EST: quarterly estimated tax for the following year; it is not an extension.
- CIT-EXT, FID-EXT and PRT-EXT: the extension forms for corporations, estates and trusts, and partnerships. A corporation that e-files and pays by check uses Delaware Form CIT-VCH for the payment.
Questions about Delaware PIT-EXT
Does a federal Form 4868 extension also extend my Delaware return?
The 2025 PIT-RES and PIT-NON instructions describe a single way to extend the Delaware filing date: Form PIT-EXT filed before the due date. They do not mention the federal extension at all, so confirm with the Division of Revenue at (302) 577-8208 before relying on a federal extension alone.
Do I have to file PIT-EXT if I owe nothing?
The extension comes from filing the form, not from the payment. When line 5 is larger than line 1, the form tells you to enter 0 on line 6, and the request is still filed by April 30.
Can I file the extension online?
The instructions say PIT-EXT may be filed on the Delaware Taxpayer Portal at tax.delaware.gov, with direct debit or credit card payment of any balance. A blank paper copy remains available on the forms page.
Sources
- Form PIT-EXT, Application for Automatic Extension of Time to File Delaware Individual Income Tax Return, 2025 (Revision 20250516)
- 2025 Delaware Individual Resident Income Tax Return instructions (PIT-RES)
- 2025 Delaware Individual Non-Resident Income Tax Return instructions (PIT-NON)
- Personal Income Tax Forms Current Year (2025-2026), Delaware Division of Revenue
- Payment, Delaware Division of Revenue