When an online or out-of-state seller ships something to your Nebraska address without charging Nebraska sales tax, the tax does not disappear: you owe it yourself as use tax. Form 3, the Nebraska and Local Individual Use Tax Return, is how an individual reports and pays it outside the income tax return. The current version is 6-090-1990 Rev. 6-2025, which supersedes Rev. 7-2024.
Who owes Nebraska use tax and files Form 3
The instructions on page 2 of the form cover every individual who buys taxable items or services over the Internet, by catalog, or inside or outside Nebraska without paying Nebraska and local sales tax. They list these examples:
- Online and mail order purchases.
- Property such as books, clothing, computers or software from a retailer that did not collect Nebraska and local sales tax, including the purchase, lease or rental of an aircraft.
- Taxable services, for example pest control, building cleaning or motor vehicle towing, from a retailer that did not collect the tax.
- Property bought outside Nebraska and brought into the state for use or storage.
The Department of Revenue’s sales and use tax FAQ adds a case for service members: purchases from federal commissaries and stores are exempt, but purchases from private retailers, including Internet retailers, are taxable, and use tax can be reported on Form 3 or Form 1040N.
Form 3 is for individuals. The Nebraska Use Tax Information Guide (6-317-1992 Rev. 3-2021) sends licensed retailers to Form 10 and businesses without a sales tax permit to Form 2. Form 3 has no line for a credit: if you are claiming a credit for sales tax properly paid to another state, the form itself tells you to use Form 2 instead.
Purchases that owe no use tax
Anything exempt from Nebraska sales tax is also exempt from use tax. The information guide lists further exemptions:
- Tax was properly paid in another state at a rate equal to or greater than the Nebraska state and local rate.
- The item was first used for its intended purpose in another state. This does not apply to motor vehicles, motorboats or airplanes.
- The item was bought in another state, stored but not used in Nebraska, and then taken to and used in another state.
An aircraft brought into Nebraska without sales tax paid is taxable unless the purchase was an occasional sale, the aircraft qualifies as a common carrier, or it arrived a year or more after purchase and during the year after purchase was neither regularly based in Nebraska nor used there for more than half its operating hours.
Form 3 or line 58 of Form 1040N
You can report individual use tax either on Form 3 or on your income tax return. On the 2025 Form 1040N it is line 58, with boxes for purchases subject to state tax at 5.5%, purchases subject to local tax, and one local code. The Department’s sales and use tax FAQ still refers to Form 1040N line 38; on the 2025 form the use tax line is 58.
Form 1040N only works for simple cases. The 2025 income tax booklet says that if you owe use tax to more than one Nebraska local jurisdiction, you report it on Form 3 and not on Form 1040N. Purchases made inside a Good Life District within city limits also have to go on Form 3, because only Form 3 has the district codes. The information guide puts the same limit as fewer than two local jurisdictions for Form 1040N.
Form 3 also corrects use tax already reported on Form 1040N, since an amended Form 1040N cannot change that amount:
| Situation on the original Form 1040N | What the booklet says to file |
|---|---|
| No use tax reported, but some is owed | Form 3 |
| Use tax reported needs to go up | Form 3 with “Amended” written across the top |
| Use tax reported needs to go down and is not yet paid | Form 3 with “Amended” written across the top |
| Use tax reported and paid needs to go down | Form 7, Claim for Overpayment of Sales and Use Tax |
When Form 3 is due
The two official documents describe timing differently. The instructions on Form 3 (Rev. 6-2025) say a return may be filed at any time: after each purchase, monthly, quarterly or annually. The Nebraska Use Tax Information Guide (Rev. 3-2021) ties the frequency to your annual use tax liability and sets the due date as the 20th day of the month after the period:
| Annual use tax liability | Filing frequency in the 2021 guide |
|---|---|
| $3,000 or more | Monthly |
| $900 to $2,999 | Quarterly |
| Less than $900 | Annually, which the guide says means January 20 for most individuals |
The form’s newer instructions do not mention these thresholds or the 20th-day rule. If your purchases put you near one of those amounts, ask Taxpayer Assistance at 800-742-7474 (Nebraska and Iowa) or 402-471-5729 which schedule applies to you. The guide says interest runs on unpaid tax from the due date until payment, and a penalty may be assessed for failing to file on time, not paying or paying only part of the tax.
Filling in Form 3 line by line
Start with the header: Social Security number, the beginning and ending dates of the tax period the return covers, your name and mailing address. The box marked for Department of Revenue use, with the Nebraska ID number, stays blank.
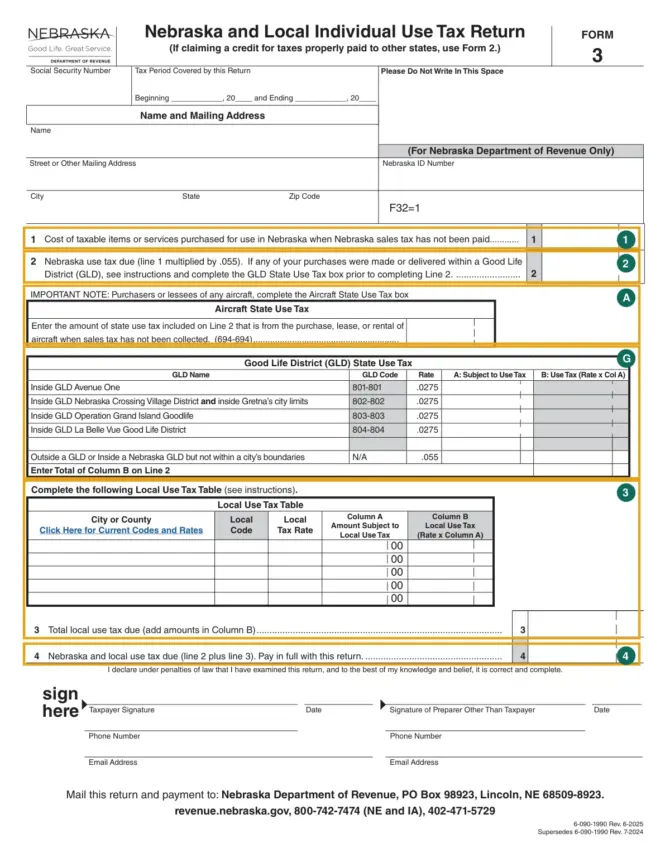
| Line or box | What you enter | Where the figure comes from |
|---|---|---|
| 1 | Cost of taxable items and services on which Nebraska sales tax was not paid | Your receipts, including shipping, handling and delivery charges paid to the retailer |
| 2 | State use tax | Line 1 × .055, or the total of column B of the Good Life District box |
| Aircraft box (694-694) | The part of line 2 that comes from buying, leasing or renting an aircraft | Your aircraft purchase or lease records |
| Local use tax table | One row per city or county: name, local code, rate, cost delivered there (column A), tax (column B) | Current local sales and use tax rate schedule |
| 3 | Total local use tax | Sum of column B |
| 4 | Total due | Line 2 plus line 3; paid in full with the return |
Line 1
Enter the full cost of the taxable items and services, including shipping, handling and delivery charges paid to the retailer, where Nebraska and local sales tax was not paid or was paid at the wrong rate. The information guide adds warranties, labor charges and other taxable services to what individuals report.
Line 2 and the Good Life District box
For purchases outside a Good Life District (GLD), or inside one but outside a city’s boundaries, multiply line 1 by .055 and leave the GLD box empty. Only purchases made or delivered inside a GLD that is also inside city limits go through the GLD box, whose column B total becomes line 2. GLD maps are on the Department’s Sales Tax Rate Finder.
Check the rates in the GLD box before you use it. Form 3 (Rev. 6-2025) prints four districts, codes 801 to 804, each at .0275. The Local Sales and Use Tax Rates effective July 1, 2026 show 2.75% only for code 801, an opted-in Avenue One retailer, and list codes 601 to 605, including a Kearney district that is not on the form, at 5.5%. The two documents do not agree on which code and rate to use, so call Taxpayer Assistance before filing a GLD purchase.
Aircraft State Use Tax box
This box does not add tax. It shows how much of line 2 comes from an aircraft. The instructions define aircraft broadly enough to include airplanes, drones and hot air balloons.
Local use tax table and line 3
Local use tax is owed where the purchase was delivered, if that city or county has a local tax and you did not pay it. Put the cost of items delivered in each jurisdiction in column A, multiply by that jurisdiction’s rate, and enter the result in column B. The July 1, 2026 schedule lists, for example, Omaha at 1.5% with code 1-365 and Scottsbluff at 1.5% with code 22-432. Dakota County’s 0.5% county rate applies only outside a municipality that has its own local rate.
A worked example with made-up figures: a $1,200 drone shipped to an Omaha address from a seller that charged no tax. Line 1 is $1,200 and line 2 is $66. Because a drone counts as aircraft, the same $66 goes in the Aircraft State Use Tax box. The local table gets one Omaha row: 1-365, .015, $1,200 in column A and $18 in column B, so line 3 is $18 and line 4 is $84.
Signing and paying
The taxpayer signs Form 3. Someone else may sign only if a power of attorney for that person is on file with the Department of Revenue; Nebraska uses Form 33 to appoint a representative. A paid preparer must sign as well, in the preparer section next to the taxpayer’s.
Entering an email address lets the Department contact you by email. The instructions say confidential information is sent by secure email or the state’s file share system; write “Opt Out” on the email line if you do not want email contact.
Getting Form 3 and where to mail it
The fillable PDF is on the Department’s sales and use tax forms page, listed as the Nebraska and Local Individual Use Tax Return (6/2025). The form gives one mailing address for the return and the payment:
Nebraska Department of Revenue
PO Box 98923
Lincoln, NE 68509-8923
Pay the line 4 amount with a check or money order made payable to the Nebraska Department of Revenue, enclosed with the return.
Official PDF: Form 3 — Official PDF (revenue.nebraska.gov)
Problems the official instructions point out
- Leaving shipping, handling or delivery charges out of line 1. The instructions include them in the cost.
- Reporting use tax for several local jurisdictions, or a GLD purchase inside city limits, on Form 1040N line 58. The booklet sends both to Form 3.
- Trying to lower or raise use tax on an amended Form 1040N. The booklet says that amount cannot change there.
- Using Form 3 to claim a credit for sales tax paid to another state. The form directs that claim to Form 2.
- Having someone else sign without a power of attorney on file with the Department.
Questions about the individual use tax return
Do I owe use tax on something I bought online if the seller charged no sales tax?
If the item is taxable in Nebraska and neither Nebraska nor local sales tax was collected, the use tax guide says the buyer must pay it directly to the state, on Form 3 or on Form 1040N.
The seller charged Nebraska state tax but no city tax. What do I report?
The 2025 booklet says you can report only the local tax on Form 1040N line 58 when the vendor charged the state tax but not the local tax. On Form 3, column A of the local use tax table is the cost of items delivered in a jurisdiction where local sales tax was not paid.
Can Form 3 be filed online?
The Form 3 instructions give a mailing address and ask for a check or money order with the return; they do not describe an online filing option. Individuals who file Form 1040N electronically can report use tax on line 58 instead, within the limits above.
Sources
- Form 3, Nebraska and Local Individual Use Tax Return, 6-090-1990 Rev. 6-2025
- Nebraska Use Tax Information Guide, 6-317-1992 Rev. 3-2021
- 2025 Nebraska Individual Income Tax and Amended Return Booklet (8-307-2025), line 58
- Local Sales and Use Tax Rates, effective July 1, 2026
- Nebraska Sales and Use Tax FAQs
- Sales and Use Tax Forms, Nebraska Department of Revenue