Alabama Schedule A is the page of the 2025 Form 40 where a resident who itemizes lists medical costs, taxes, interest, gifts to charity, casualty losses and miscellaneous expenses. Line 27 gives the total, which goes on Form 40, page 1, line 11 with box 11a checked. The amounts start from the federal rules but are recalculated with Alabama adjusted gross income (Form 40, line 10), so a medical floor of 4%, a deduction for FICA tax and a new 2025 line for vehicle loan interest make the Alabama figure different from the federal one.
Who files Schedule A with Form 40
Form 40 line 11 has two boxes and one of them must be checked: box a with the amount from Schedule A, line 27, or box b with the standard deduction from the chart on page 9 of the 2025 Form 40 booklet. The booklet tells you to work out your deduction both ways and keep the larger one. If you claimed the standard deduction and later find that itemizing is better, the switch is made on an amended return.
Itemizing decides which return you use. Form 40A is closed to anyone who itemizes, so a full-year resident with only wages who wants Schedule A files Form 40. A nonresident does not use this page: the 2025 Form 40NR has its own Schedule A with 30 lines, where line 21 totals the deductions to be prorated, line 22 applies the percentage from Form 40NR page 1, line 10, and line 30 goes to Form 40NR line 13.
Two household situations have their own rules. Married couples filing separate Alabama returns must both itemize or both take the standard deduction, unless they lived apart for the entire year, and neither spouse may deduct expenses the other one paid. A part-year resident lists only deductions actually paid while living in Alabama; when an expense such as interest or taxes was paid over the whole year and the resident-period share cannot be determined, the Department allows a proration by the number of months of residence.
What changed on the 2025 Schedule A
The “What’s New For 2025” page of the Form 40 booklet lists one change that lands on Schedule A: Section 40-18-15 now allows a deduction for interest on a loan for a new qualified vehicle, for 2025 through 2028. On the 2025 schedule it is line 11, with places for the purchase date and VIN of two vehicles (11a and 11b) and the worksheet result on 11c, which line 14 adds to the other interest lines. The other items on that page (the identity quiz, the military income exemption, the precious metal bullion exclusion and four new credits) concern Form 40 income lines and Schedule OC, not Schedule A.
How to fill out Schedule A, line by line
Complete Form 40, page 1, lines 1 through 10 first, because lines 2, 19b and 23 use line 10. Every expense is entered after reimbursements; the caution at the top of the schedule excludes anything reimbursed or paid by others. The marked page below shows five groups of lines: the 4% medical floor (1), vehicle loan interest (2), the casualty loss reduction (3), the 2% miscellaneous floor (4), and long-term care premiums with the total (5).
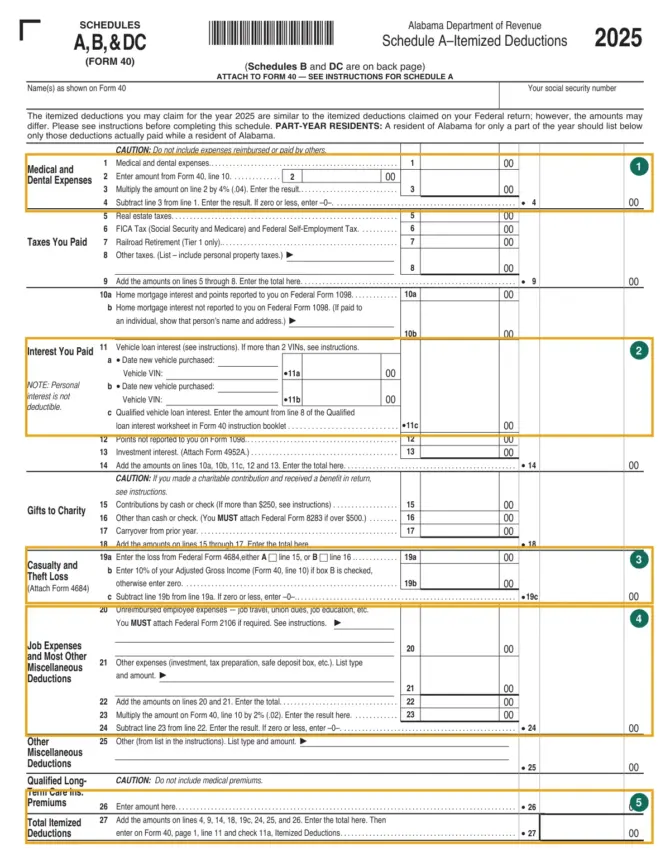
| Line | What goes there | Where the figure comes from |
|---|---|---|
| 1 to 4 | Medical and dental expenses; line 3 is 4% of line 2; line 4 is the excess | Bills, insurance statements; line 2 = Form 40, line 10 |
| 5 | Real estate taxes on nonbusiness property in any state | Tax bill or the year the mortgage company paid it |
| 6 | FICA (Social Security and Medicare) withheld, and federal self-employment tax paid in 2025 | Form W-2; self-employment tax payments for 2024 or earlier years |
| 7 | Railroad retirement tax, tier 1 only | Railroad pay records |
| 8 | Other taxes, listed by type | City, county or occupational tax on the W-2, personal property tax based on value, and the other taxes the booklet lists |
| 10a, 10b, 12 | Home mortgage interest and points | Federal Form 1098; name and address of an individual lender on 10b |
| 11a to 11c | Vehicle loan interest | Purchase date, VIN and interest for each vehicle; 11c from line 8 of the Qualified Vehicle Loan Interest Worksheet |
| 13 | Investment interest | Alabama Form 4952A, attached |
| 15 to 17 | Gifts by cash or check, other property, carryover from a prior year | Receipts and records; Federal Form 8283 when line 16 is over $500 |
| 19a to 19c | Nonbusiness casualty and theft losses | Federal Form 4684, line 15 (box A) or line 16 (box B) |
| 20 to 24 | Unreimbursed job expenses and other expenses, less 2% of Form 40, line 10 | Federal Form 2106 when required, or a list of expense types |
| 25 | Miscellaneous deductions not subject to the 2% limit | Only the four items in the booklet list |
| 26 | Qualified long-term care insurance premiums, in full | Premium statements |
| 27 | Total of lines 4, 9, 14, 18, 19c, 24, 25 and 26 | Goes to Form 40, line 11, box 11a |
Medical and dental expenses, lines 1 to 4
Line 1 is what you paid for yourself, your spouse, the dependents on your return and a child of divorced or separated parents you do not claim under the federal rules. It includes doctors, dentists, hospitals, prescription drugs and insulin, Medicare Part B, medical insurance premiums you paid, hearing aids, glasses, and travel to care at actual gas and oil cost or the federal mileage rate plus parking and tolls. Lodging away from home for hospital care counts up to $50 a night per person, without meals.
Three exclusions are specific to the Alabama line. Premiums paid through an employer cafeteria plan are left out. Qualified long-term care premiums are also left out of line 1 because they are deducted in full on line 26. A 2025 reimbursement of an earlier year’s medical bills does not reduce 2025 expenses; it goes into income on Form 40 if the earlier deduction lowered your tax. With Form 40, line 10 at $50,000 and $3,400 of unreimbursed medical bills, line 3 is $2,000 and line 4 is $1,400.
Taxes you paid, lines 5 to 9
Real estate, personal property and generation-skipping transfer taxes follow 26 U.S.C. 164, but any limit is figured with Alabama adjusted gross income. If the mortgage company pays the property tax from escrow, the deduction belongs to the year it actually paid the taxing authority. On line 6, FICA withheld by your employer is deductible, except the excess withheld when you had more than one employer and claimed that excess as federal withholding. Self-employment tax counts in the year paid, so a 2025 payment of 2024 self-employment tax goes on the 2025 schedule.
Line 8 takes city, county and occupational tax shown on a W-2, unemployment insurance tax paid to another state, federal gift tax paid by the donor, the value-based part of a car registration fee and generation-skipping transfer tax on income distributions. State income tax cannot be deducted here; tax paid to another state is handled as a credit on Schedule CR. Sales tax, foreign income tax, license fees, gasoline tax and business taxes are also on the booklet’s list of taxes you cannot deduct.
Interest, including the vehicle loan line, lines 10a to 14
Only nonbusiness interest belongs here, and personal interest is not deductible. Investment interest on line 13 needs Alabama Form 4952A. If you take the mortgage interest credit on your federal return, Alabama lets you deduct the full interest paid before that credit.
Line 11 applies to interest on a loan that originated after December 31, 2024 to buy a vehicle for personal use whose original use began with you, secured by a lien on the vehicle, with final assembly in the United States. Lease payments do not qualify. Enter the purchase date, VIN and interest for up to two vehicles on 11a and 11b. With more than two, the booklet asks for a separate spreadsheet with the same fields, the same size as Schedule A, and “Statement attached” in the VIN field on 11a; the 2025 fillable Form 40 file includes a Vehicle Loan Interest Spreadsheet page with 20 rows for this.
The worksheet on page 31 of the booklet caps the interest at $10,000 and phases it out above $100,000 of Form 40, line 10 ($200,000 for married filing jointly). Each $1,000 above that threshold, rounded up, removes $200. A single filer with $3,000 of qualifying interest and line 10 of $104,500 is $4,500 over; that rounds to 5, the reduction is $1,000, and line 11c is $2,000.
Gifts to charity, lines 15 to 18
Contributions follow the federal rules, with the limits figured on Alabama adjusted gross income. Line 15 takes gifts by cash or check, including out-of-pocket costs of volunteer work; driving for that work counts at 14 cents a mile or actual gas and oil, plus parking and tolls. If you received something in return, only the part above the value of the benefit is deductible: a $75 ticket to a charity concert valued at $30 gives $45. Line 16 is property at fair market value, and Federal Form 8283 is attached when that deduction is over $500. Line 17 is a carryover of gifts you could not deduct in an earlier year because of the income limit.
Line 15 on the 2025 form says “If more than $250, see instructions”, but the line 15 instructions in the 2025 Form 40 booklet state no rule for gifts above $250. The booklet asks for canceled checks, receipts or other reliable written records with the organization’s name, date and amount, and refers to Federal Pub. 526. For a cash gift above $250, the Montgomery Taxpayer Service Center, (334) 242-2677, can say what record ALDOR expects with Schedule A.
Donations made from a refund through Schedule DC are their own case: the 2025 booklet says an amount donated from the 2025 overpayment may be claimed as an itemized deduction on the 2026 Alabama return.
Casualty and theft losses, lines 19a to 19c
The loss is figured on Federal Form 4684 and attached. Check box A and enter Form 4684 line 15, or check box B and enter line 16 (Section A). Only with box B does line 19b take 10% of Form 40, line 10; otherwise line 19b is zero. Alabama allows the loss only in the year it occurred or the theft was discovered, each loss must exceed $100, and losses from misplaced property, normal breakage or termite and insect damage are not deductible. Appraisal fees and photographs used to prove the loss go on line 21.
Miscellaneous deductions, lines 20 to 26
Line 20 is unreimbursed job expenses such as union dues, required uniforms, safety equipment and job education. If you have any travel, transportation or meal expense for your job, or your employer paid you for some of these expenses, fill out Federal Form 2106 for all of them and enter its net amount. Line 21 covers tax preparation fees, safe deposit box rent, certain legal and accounting fees and custodial fees. Lines 22 to 24 subtract 2% of Form 40, line 10, so with line 10 at $60,000 the first $1,200 of lines 20 and 21 is not deductible. Excess deductions of a decedent’s estate or an irrevocable trust cannot be claimed (Code of Alabama 40-18-25(4)).
Line 25 has no 2% floor but accepts only four items: gambling losses up to gambling winnings reported on Form 40, page 2, Part I, line 7; amortizable premium on bonds acquired before October 23, 1986; unrecovered investment in a pension; and impairment-related work expenses of a disabled person. Line 26 is qualified long-term care insurance premiums you paid, deducted in full. The caution on the form keeps other medical premiums off this line.
Attachments that go with Schedule A
- Alabama Form 4952A for investment interest on line 13.
- A statement or the Vehicle Loan Interest Spreadsheet when more than two vehicles are claimed on line 11.
- Federal Form 8283 when the property gift on line 16 is over $500; appraisals may also be needed above $5,000.
- Federal Form 4684 for line 19a.
- Federal Form 2106 for line 20 when travel, transportation or meal expenses are claimed, or your employer reimbursed part of the job expenses.
- A list of type and amount for lines 8, 21 and 25, with a separate statement if the space runs out.
- If you use the fill-in 2025 Form 40 file, print it with the Print Form button so the 2-D barcode carries the entries, and handwrite nothing except your signature.
Where to get Schedule A and where it is filed
There is no separate Schedule A file. The fillable schedule is page 3 of the 2025 Form 40 PDF on revenue.alabama.gov, with Schedules B and DC on its back, and the line instructions are in Section 5 of the 2025 Form 40 booklet. The Qualified Vehicle Loan Interest Worksheet appears both on page 31 of the booklet and at the end of the Form 40 file. Schedule A has no signature line of its own; it travels with the signed Form 40, which can be filed online through My Alabama Taxes (MAT) at no charge, e-filed by a tax practitioner or with approved software, or mailed.
The 2025 return was due on the federal due date, April 15 for most individuals, with an automatic extension to October 15, 2026 that does not extend the time to pay. Both dates have passed at this check. A late original return still has to be filed within two years of the date the taxes were paid to be eligible for a refund. Paper returns go to one of these addresses:
| Your 2025 Form 40 | Mail to |
|---|---|
| Shows a refund (line 35) | Alabama Department of Revenue, P.O. Box 154, Montgomery, AL 36135-0001 |
| Shows a payment (line 30), with Form 40V | Alabama Department of Revenue, P.O. Box 2401, Montgomery, AL 36140-0001 |
| Shows neither | Alabama Department of Revenue, P.O. Box 327469, Montgomery, AL 36132-7469 |
| Amended or prior-year return | Alabama Department of Revenue, Income Tax Administration Division, P.O. Box 327464, Montgomery, AL 36132-7464 |
Official PDF: Schedule A (Form 40) — Official PDF (revenue.alabama.gov)
Related Alabama forms
- Form 4952A, Investment Interest Expense Deduction, for line 13.
- Schedule A of Form 40NR, the prorated version for nonresidents.
- Schedule CR, for income tax paid to another state, which cannot be deducted on line 8.
- Alabama Form 2848A, if someone will represent you before the Department about the return.
Questions about Alabama Schedule A
Can I itemize on my Alabama return if I took the standard deduction on my federal return?
The 2025 Form 40 booklet does not tie the Alabama choice to the federal one. It tells you to compute the deduction both ways and keep the larger, and a later switch to itemizing is made on an amended return.
Is FICA tax deductible in Alabama?
Social Security and Medicare tax withheld by your employer goes on Schedule A, line 6, together with federal self-employment tax paid during 2025. Excess FICA from more than one employer that you claimed as federal withholding is not deductible.
Does a leased car qualify for the vehicle loan interest deduction?
Lease payments do not qualify. The interest must be on a loan that originated after December 31, 2024, secured by a lien on a new vehicle assembled in the United States and bought for personal use.