Schedule CP-B is where an Alabama business return claims tax that someone else already paid on its behalf. If an S corporation, partnership, estate or trust paid Alabama composite tax for you, or paid the electing pass-through entity tax and passed you a share of the credit, you list that payer on Schedule CP-B and carry the total to the payments section of your own return. The schedule is attached to Form 20C, Form ET-1, Form 41, Form PTE-C or Form EPT. The Alabama Department of Revenue lists the current file under Form Year 2025; the year box on the form itself is left blank for you to fill in.
Who attaches Schedule CP-B and who uses Schedule CP instead
The instructions say the schedule must be completed and attached by taxpayers claiming composite payments or electing pass-through entity credits on one of five returns. Each of those returns says the same thing at its own payments line, so the filer type decides the line:
| Who is claiming | Return | Line that takes Schedule CP-B, line 3 |
|---|---|---|
| A corporation | Form 20C | Page 1, line 20c |
| A financial institution | Form ET-1 | Page 1, line 19c |
| An estate or trust | Form 41 | Page 1, line 8f |
| A partnership or S corporation filing a composite return for its own nonresident owners | Form PTE-C | Page 1, line 5c |
| A partnership or S corporation that elected to pay tax at the entity level | Form EPT | Page 1, line 5d |
Individuals do not use Schedule CP-B. A person filing Form 40 or Form 40NR has a separate Schedule CP (Form 40 or 40NR) for the same kind of payment. It asks for the Social Security number shown on the Schedule K-1, and its total goes to Form 40, page 1, line 26 or Form 40NR, page 1, line 23.
The PTE-C line belongs to tiered ownership. The 2025 Form PTE-C instructions say that every Subchapter K entity and every S corporation credited with a composite payment on another entity’s composite return must also file a composite return, to allocate that payment among its own owners. The same instructions add that the Department now requires Schedule CP-B for listing payments made on the entity’s behalf by another entity.
Where the amounts come from
A composite payment starts with Form PTE-C. A partnership or other Subchapter K entity with one or more nonresident owners during the year files a composite return and pays tax for them, and the instructions set the rate at the 5% maximum rate in Code of Alabama § 40-18-5, applied to each nonresident owner’s distributive share. Take a Tennessee corporation that owns part of an Alabama LLC taxed as a partnership. The LLC pays composite tax on the corporation’s share. The corporation then files its own Form 20C, lists the LLC on Schedule CP-B and claims the amount on line 20c.
An electing pass-through entity credit comes from Form EPT. Under the Department’s Electing Pass-Through Entity FAQ, each owner, member, partner or shareholder is entitled to a refundable credit equal to its pro rata or distributive share of the Alabama income tax the electing entity paid for that tax year. The FAQ adds that an owner who wants the credit has to file a return and report its share of the entity’s income. Once an entity makes the election, it no longer files a composite return for nonresident members.
The figure to copy into column C is printed on the Alabama Schedule K-1 the payer sends you:
- Schedule K-1 (Form 65), line AA: the composite payment or electing pass-through entity credit made on behalf of the owner.
- Schedule K-1 (Form 20S), line AA: the same amount for an S corporation shareholder.
- Schedule K-1 (Form 41), line 15, printed as Composite/Electing Pass-Through Credit, on a K-1 from an estate or trust.
How to fill out Schedule CP-B, column by column
Page 1 has a header, nineteen rows in Section A and three lines in Section B. The numbers in the table below match the markers on the image.
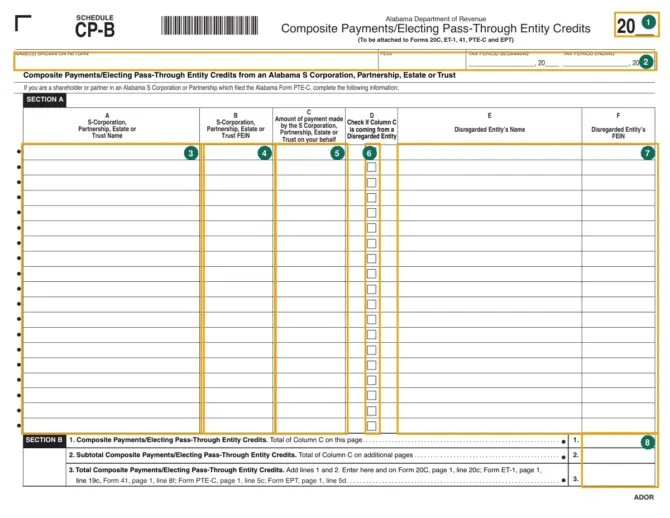
| Marker | Printed label | What to enter |
|---|---|---|
| 1 | 20__ | The tax year of the return the schedule is attached to. |
| 2 | Name(s) shown on return, FEIN, tax period beginning and ending | Your entity’s name and FEIN as on the return, and the dates of a fiscal or short year. |
| 3 | Column A, S-Corporation, Partnership, Estate or Trust Name | The entity that made the payment or generated the credit for you. |
| 4 | Column B, its FEIN | That entity’s federal employer identification number. |
| 5 | Column C, Amount of payment made on your behalf | The amount from your Alabama Schedule K-1. |
| 6 | Column D, Check if Column C is coming from a Disregarded Entity | Check only when the column C amount comes from a disregarded entity. |
| 7 | Columns E and F, Disregarded Entity’s Name and FEIN | The disregarded entity’s name and FEIN, for rows where column D is checked. |
| 8 | Section B, lines 1 to 3 | Line 1: column C total on this page. Line 2: column C totals from additional pages. Line 3: lines 1 and 2 added. |
Every payment or credit takes its own row. A corporation that is a partner in two Alabama partnerships, one paying composite tax and the other an electing entity, enters two rows with two FEINs even if the amounts are small. When nineteen rows are not enough, page 2 of the PDF is the continuation page: it repeats the header and Section A, and its Section B has a single line for the column C total of that page. That total feeds line 2 on page 1.
Trusts and estates: line 8f and line 8g of Form 41
A trust or estate uses Schedule CP-B like any other filer and enters line 3 on Form 41, line 8f. Form 41 then has a second line for the same money. The Form 41 instructions for line 8g ask for the composite or electing pass-through entity payments allocated to the beneficiary, entered as a negative number. The beneficiary’s copy, the Alabama Schedule K-1 (Form 41), has its own line 15 for a composite or electing pass-through credit. A trust that owes tax on Form 41 can send its payment with the Alabama FDT-V voucher.
Before you attach it
- One row for each payment or credit, with the payer’s name in column A and its FEIN in column B.
- Column D, E and F filled in only for an amount that comes from a disregarded entity.
- Continuation page totals added on line 2 of page 1.
- Line 3 equals the amount on line 20c (Form 20C), 19c (Form ET-1), 8f (Form 41), 5c (Form PTE-C) or 5d (Form EPT).
- The schedule attached to that return. The Form 20C, ET-1, 41 and PTE-C instructions each say Schedule CP-B must be attached when the credit is claimed.
Where to get Schedule CP-B and where it goes
The 2025 PDF and its one-page instructions are on the Department’s forms list under the title “Composite Payments for Forms 20C, PTE-C, EPT and 41”. Schedule CP-B has no due date or address of its own; it travels with the return it supports. The PTE-C instructions put a calendar year 2025 composite return due on or before March 15, 2026, and the EPT FAQ gives the 15th day of the third month after the year ends. For returns sent on paper, the Department’s Forms Mailing Addresses page lists these boxes, all in Montgomery:
| Return | Making a payment | Not making a payment |
|---|---|---|
| Form 20C | P.O. Box 327435, Montgomery, AL 36132-7435 | P.O. Box 327430, Montgomery, AL 36132-7430 |
| Form ET-1 | P.O. Box 327439, Montgomery, AL 36132-7439 | P.O. Box 327439, Montgomery, AL 36132-7439 |
| Form 41 | P.O. Box 327444, Montgomery, AL 36132-7444 | P.O. Box 327440, Montgomery, AL 36132-7440 |
| Form PTE-C | P.O. Box 327444, Montgomery, AL 36132-7444 | |
| Form EPT | P.O. Box 327444, Montgomery, AL 36132-7444 | P.O. Box 327444, Montgomery, AL 36132-7444 |
A Form 20C amended because of a federal audit change has a third address on the same page, P.O. Box 327451, Montgomery, AL 36132-7451.
One wording point on the form itself: the line above Section A addresses shareholders or partners in an S corporation or partnership that filed Form PTE-C, while the columns and the instructions also cover estates, trusts and electing pass-through entity credits. The instructions do not limit the schedule to PTE-C payments. If your case depends on that difference, the Pass-Through Entity Section answers at (334) 242-1170, Option 6, the number given in the PTE-C instructions. This page explains the schedule and is not tax advice.
Official PDF: Schedule CP-B — Official PDF (revenue.alabama.gov)
Questions about Alabama Schedule CP-B
Can I claim a composite payment on Form 20C without attaching Schedule CP-B?
The Form 20C instructions for line 20c say Schedule CP-B must be completed and attached when composite payments or electing pass-through entity credits are claimed. Forms ET-1, 41 and PTE-C carry the same sentence.
I am an individual partner. Is Schedule CP-B for me?
Individuals use Schedule CP with Form 40 or Form 40NR. It has its own columns for the Social Security number on the K-1 and goes to Form 40, line 26 or Form 40NR, line 23.
Where do I find the amount for column C?
On your Alabama Schedule K-1: line AA of the Form 65 or Form 20S K-1, or line 15 of the Form 41 K-1.
What if more than nineteen entities paid for us?
Use page 2 of the PDF as many times as needed. Add the column C totals of those pages and enter the sum on line 2 of page 1.
Official sources
- Alabama Department of Revenue, Schedule CP-B, Composite Payments/Electing Pass-Through Entity Credits (2025)
- Alabama Department of Revenue, Schedule CP-B instructions (2025)
- Alabama Department of Revenue, Composite Payments for Forms 20C, PTE-C, EPT and 41
- Alabama Department of Revenue, Form PTE-C and Schedule PTE-CK1 instructions (2025)
- Alabama Department of Revenue, Form 20C instructions (2025)
- Alabama Department of Revenue, Form ET-1 instructions
- Alabama Department of Revenue, Form 41 instructions (2025)
- Alabama Department of Revenue, Form EPT (2025)
- Alabama Department of Revenue, Electing Pass-Through Entity FAQ
- Alabama Department of Revenue, Schedule K-1 (Form 65) instructions (2025)
- Alabama Department of Revenue, Schedule K-1 (Form 20S) instructions (2025)
- Alabama Department of Revenue, Schedule K-1 (Form 41) (2025)
- Alabama Department of Revenue, Schedule CP (Form 40 or 40NR) (2025)
- Alabama Department of Revenue, Forms Mailing Addresses