Alabama Schedule OC is the 2025 worksheet on which a Form 40 or Form 40NR filer works out every individual income tax credit and the net tax that goes back to the return. It runs eight pages. Section A brings in the tax from Form 40 line 17 (Form 40NR line 19), Section B holds 30 credit parts lettered A through AD, Sections C and D apply this year’s credits and older carryforwards against that tax, and Sections E and F produce the amounts for Form 40 line 18 and line 25. A filer with no credits skips the schedule and copies line 17 to line 18.
Who uses Schedule OC, and which credits need MAT approval first
The schedule is headed “Attach to Form 40 or 40NR”, and each page repeats the name and Social Security number lines from the return. On Form 40 line 18 (Form 40NR line 20) there is a box to check when Schedule OC computes the net tax. Two parts are limited to Form 40: Part A, the credit for taxes paid to other states, and Part I, the credit for taxes paid to a foreign country.
Fifteen parts carry an asterisk on the 2025 form: E, F, G, H, J, N, S, T, U, V, X, Y, AA, AB and AC. The note under the title says these individual credits must be submitted through My Alabama Taxes (MAT) before the schedule is completed. In MAT, the claim starts from the Individual Income Tax account with “Submit a Credit Claim”; the Schedule OC instructions place that link in the “I Want To” menu, while the Form 40 booklet calls the area “Tax Incentives”. Someone without a MAT account can use “Submit an Individual Credit Claim” in the Individuals section of the MAT home page. Supporting documents for certain credits are uploaded in MAT, and ALDOR lists (334) 353-9770 and (334) 353-0602 for help reserving a credit.
A credit that arrives on a Schedule K-1 works differently. The booklet says the partnership or S corporation submits the claim and the individual takes no MAT action; the owner enters the pro rata share and the entity’s FEIN on the part’s K-1 line and attaches a schedule when the credit comes from more than one entity.
Situations that match a part on the 2025 form: an Alabama resident whose wages were also taxed by another state with an income tax (Part A), a licensed physician practicing in a rural community (Part D), parents who adopted a child (Part M), a homeowner who built a certified storm shelter at the primary residence (Part U), a volunteer firefighter or rescue squad member (Parts V and X), and a business owner whose S corporation or partnership passes through a credit.
How to fill out Section B, Parts A through AD
Enter Section A first, because Parts A, O, R and W calculate from it. Every part ends on a “credit allowable” line that is copied to Section C, Column 3. Parts O, R and W also send their current credit available to Column 2.
| Part | Credit | Lines and limits printed on the 2025 schedule | Record behind the entry |
|---|---|---|---|
| A | Taxes paid to other states (Form 40 only) | A3 = A1 (Schedule CR line 26) divided by A2 (Form 40 line 10); A4 = Section A times A3; A6 = smaller of A4 or A5 (Schedule CR line 27) | Schedule CR and the other state’s return, or W-2Gs where that state allows no return for gambling winnings |
| B | Enterprise Zone credit or exemption | B1 from Schedule EZK1, Part II, line 13 or Schedule EZ, Part IV, line 13 | Schedule EZK1 or EZ |
| C | Basic Skills Education | C1 to C5: certification number, sponsor, provider, 16-week and 24-hour tests; C7 = C6 times 20% | Department of Education certification notice, attached |
| D | Rural Physician | D2: $5,000, or $10,000 when both spouses on a joint return qualify | Hospital and community named on D1 |
| E | Coal* | E1 own credit plus E2 K-1 share = E3 | MAT claim, unless the credit comes through a pass-through entity |
| F | Full Employment Act of 2011* | Yes/No box for 50 or fewer employees on June 9, 2011; F3 = F1 (full-time employees on 12-31-2024) minus F2 (12-31-2023); F5 = F4 times $1,000 | MAT claim; K-1 share on F6 |
| G | Veterans Employment Act, employer credit* | G2 = G1 (unemployed veterans counted in F4) times $2,000 | MAT claim; K-1 share on G3 |
| H | Veterans Employment Act, business start-up expense credit* | Yes/No box for a start-up after April 2, 2012; H4 = lesser of H2 expenses or the $2,000 maximum on H3 | MAT claim; business name and ID on H1 |
| I | Taxes paid to a foreign country (Form 40 only) | I8 = I7 times 50%; I9 = lesser of I6 or I8, all in U.S. dollars | Entity name, FEIN and country on I1 to I3 |
| J | Qualified irrigation or reservoir system* | One box only: irrigation (J1 to J4) or reservoir (J5 to J6), each 20% of cost; J8 limit $10,000; K-1 share on J10 | MAT approval |
| K | Accountability Act, school transfer | K1 from Schedule AATC, line 37 | Schedule AATC |
| L | Accountability Act, scholarship granting organization | L5 = L3 contribution plus L4 K-1 share; L6 maximum $100,000; L7 = lesser of L5 or L6 | Organization’s name and address on L1 and L2 |
| M | Adoption | M1 from Schedule AAC, Part III, line 3 | Schedule AAC |
| N | 2013 Historic Rehabilitation* (project numbers before 2018) | N1a to N1c: project number, date placed in service, certificate amount; N4 adds the K-1 share | Tax Credit, Transfer or Recipient Tax Credit Certificate, attached |
| O | Career-Technical Dual Enrollment | O2 = O1 times 50%; O7 = least of O4, O5 (half of Section A) or O6 ($500,000); O8 and O9 set the carryforward limit | Department of Postsecondary Education certificate, attached |
| P | Investment credit, Alabama Jobs Act | Project number; P1 certificate amount plus P2 K-1 share | Sole proprietors attach the certification |
| Q | Port credit | Company name and FEIN or SSN; Q1 certified amount plus Q2 K-1 share | Certification of Port Credit from the Department of Commerce, attached |
| R | Growing Alabama | R3 = R1 approved contribution plus R2; R5 = lesser of R3 or half of Section A; R6 and R7 set the carryforward limit | Name of the economic development organization |
| S | 2017 Historic Rehabilitation* (project numbers from 2018) | S1a to S1c added on S2 | Tax Credit Certificate or Transfer Tax Credit Certificate, attached |
| T | Railroad Modernization Act of 2019* | T1 from the Transfer Credit Certificate issued by ALDOR | That certificate |
| U | Storm shelter* | U1 from the Alabama Emergency Management Agency certificate | MAT claim |
| V | Volunteer emergency responders* | V1 from the Emergency Responders Credit certificate | Certificate and training certificates submitted in MAT |
| W | Innovate Alabama | W3 = W1 approved amount plus W2; W5 = lesser of W3 or half of Section A; W6 and W7 set the carryforward limit | Contribution reported in MAT |
| X | Volunteer first responder mileage* | X1 certificate amount | Certificate registered in MAT |
| Y | Preceptor tax incentive* | Y1 from the Alabama Statewide Area Health Education Center Program Office certificate | MAT claim |
| Z | Workforce housing | Project name and number; Z1 AHFA certificate plus Z2 K-1 share | Alabama Housing Finance Authority certificate |
| AA | Employer tax credit* | AA1 ADOR certificate plus AA2 K-1 share | MAT reservation, then a claim after year end |
| AB | Childcare facility* | AB1 ADOR certificate plus AB2 K-1 share | MAT reservation, then a claim after year end |
| AC | Employer provider* | AC1 ADOR certificate plus AC2 K-1 share | MAT reservation, then a claim after year end |
| AD | Income tax capital credit | AD1 from Schedule KRCC-I, Part III, line 5 | Form KRCC and Schedule KRCC-I, attached |
The 2025 instructions add conditions the boxes do not show. For Part A, residents whose wages came from a state without an income tax are not eligible, and a part-year resident qualifies only when the Alabama and other-state returns cover the same periods. Part I applies to a resident owner’s share of foreign tax paid by a partnership, S corporation, estate or trust; it does not cover wages earned abroad. The Part D physician must live and practice in an Alabama community of fewer than 25,000 residents, and the credit runs for no more than five consecutive tax years.
Part M is $2,000 per child for a private adoption of an Alabama-resident child or a qualifying child in the custody of the Alabama Department of Human Resources, and $1,000 per child for an out-of-state adoption or a child not otherwise resident in Alabama. Part U is the lesser of $3,000 or 50% of the shelter cost at the primary residence, after pre-certification by the Alabama Emergency Management Agency. Part V needs at least 30 hours of certified training in the year, shown on a certificate signed by the supervisor. Part X reimburses unreimbursed annual mileage at the state-employee rate, and Part Y starts with calendar year 2025.
Sections C and D: applying credits in order and using carryforwards
Section C, on pages 6 and 7, can only be submitted and printed in horizontal (sideways) orientation. It lists the parts in letter order. On the first row with a credit, Column 4 is the Section A tax. Column 5 is the smaller of Column 3 or Column 4, and Column 6 is Column 4 minus Column 5. The next row takes the previous Column 6 as its tax to offset, and you stop once no tax remains. Column 7 holds the carryforward: for Parts O, R and W it is Column 2 minus Column 5, for every other part Column 3 minus Column 5. Section C line 1 totals Column 5.
Section D handles carryforwards from earlier years in up to 20 rows. List the oldest credit year first and do not list tax years whose credit has already been used. When two carryforwards share a year, the instructions set this order: irrigation or reservoir system, scholarship granting organization, 2013 historic rehabilitation, career-technical dual enrollment, Alabama Jobs Act investment, port, Growing Alabama, Innovate Alabama, then the Alabama Small Business and Agribusiness Jobs Act credit. Column E starts with the balance from Section C, Column 6, or the Section A tax when no current credit was used. Column F is the smaller of Column D or Column E, Column G is Column C minus Column F, and line 21 totals Column F.
Column D equals Column C except for the dual enrollment, Growing Alabama and Innovate Alabama credits, which are capped at Column 4 of lines O9, R7 and W7. The printed note on page 8 names “Part X, Line X7”, but Part X has no line X7; the instructions name Part W, line W7. The schedule’s carryforward periods are 3 years for Parts L and O, 10 years for Part N, and 5 years for Parts E (from calendar year 2023), J, P, Q, R, W and Z. Parts S, U, X, Y and AB cannot be carried forward.
Sections E and F: the amounts for Form 40 line 18 and line 25
Section E (marker 2 below) produces the net tax. E1 repeats Section A, E2 is Section C line 1, E3 is Section D line 21 (marker 1), and E4 adds E2 and E3. E5, E1 minus E4, goes on Form 40 page 1, line 18 or Form 40NR page 1, line 20. Section F (marker 3) collects the refundable part of five credits: each of F1 to F5 is Column 3 minus Column 5 of the Section C row for Part K, M, S, AB or AC. F6 totals them and goes on page 1, line 25 of Form 40 or Form 40NR.
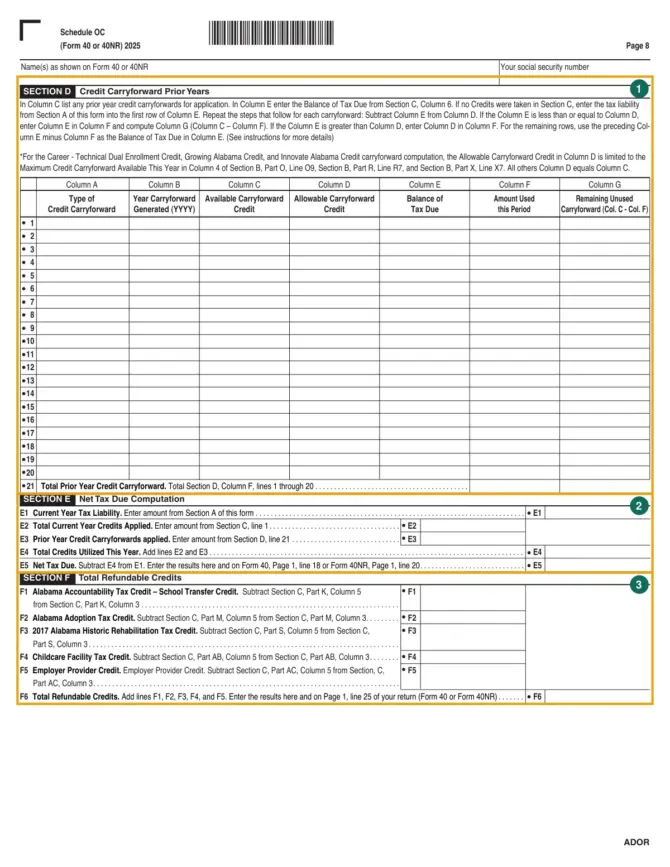
A worked example with the form’s own arithmetic: Section A tax is $1,200 and the family completed a private adoption of an Alabama-resident child, so Schedule AAC gives $2,000 for Part M. On the Part M row of Section C, Column 3 is $2,000, Column 4 is $1,200, Column 5 is $1,200 and Column 6 is $0. E5 is $0 for line 18, and F2 is $2,000 minus $1,200, or $800, which reaches Form 40 line 25 through F6. Estimated tax payments made with Alabama Form 40ES vouchers are a separate entry, Form 40 line 23.
Two printed cross-references disagree. The instructions tell you to compute F3 from Section C, Part T, Column 3, but the form’s F3 line and the Section F heading both refer to the 2017 historic rehabilitation credit in Part S, so this guide follows the form. The Part T instructions call the railroad credit refundable, yet Section F has no line for Part T; a holder of that certificate should ask ALDOR how to report any amount above the tax before filing.
Why a credit on Schedule OC can be disallowed
- A missing certificate. The instructions say no credit is allowed without the attached certificate for Part N (Tax Credit, Transfer or Recipient Tax Credit Certificate), Part O (Department of Postsecondary Education certificate), Part P for sole proprietors, Part Q (Certification of Port Credit) and Part S.
- No MAT approval for an asterisked credit. The claim has to be submitted and approved before the schedule is completed; for Parts AA, AB and AC only a taxpayer who obtained a credit reservation during the year can submit the claim.
- A part stopped by its own test: a “No” answer on the June 9, 2011 question in Part F, an F3 result of zero or less, a business that started on or before April 2, 2012 in Part H, or both the irrigation and the reservoir box ticked in Part J.
- Problems with the fill-in PDF. The form asks you not to handwrite anything except the signature, not to attach the pre-printed label, and to print with the Print Form button so the 2-D barcode carries the entries.
When and where to file Schedule OC with Form 40 or 40NR
Schedule OC has no separate filing route or signature line; it goes with the signed 2025 return. The fillable schedule sits inside the 2025 Form 40 file (PDF pages 10 to 17) and the 2025 Form 40NR file (PDF pages 7 to 14), and its instructions are a separate PDF. Resident and nonresident returns can also be filed online through MAT at no charge, or e-filed by a tax practitioner or with approved software.
The Alabama return is due on the federal due date, which ALDOR gives as April 15 for most individuals. The 2025 booklets grant an automatic extension to October 15, 2026 without a form, but the extension does not extend time to pay. Both dates have passed for 2025 returns at this check; outside the case of taxpayers abroad, the booklets allow no extension beyond six months.
Paper returns are mailed according to the result on the return. A refund (Form 40 line 35, Form 40NR line 33) goes to Alabama Department of Revenue, P.O. Box 154, Montgomery, AL 36135-0001. A payment (Form 40 line 30, Form 40NR line 29) goes with Form 40V to P.O. Box 2401, Montgomery, AL 36140-0001. A return with neither goes to P.O. Box 327469, Montgomery, AL 36132-7469. The Form 40 booklet sends prior-year and amended Form 40 returns to the Income Tax Administration Division, P.O. Box 327464, Montgomery, AL 36132-7464.
Official PDF: Schedule OC (Form 40) — Official PDF (revenue.alabama.gov)
Questions about Alabama Schedule OC
Does a credit from a Schedule K-1 need its own MAT claim?
The 2025 Form 40 and 40NR booklets say the pass-through entity submits the claim and the individual takes no action in MAT. Enter the pro rata share and the entity’s FEIN on that part’s K-1 line.
Which Schedule OC credits are refundable?
Section F refunds the unused part of the school transfer credit (Part K), the adoption credit (Part M), the 2017 historic rehabilitation credit (Part S), the childcare facility credit (Part AB) and the employer provider credit (Part AC). The Part AA employer tax credit is non-refundable except for qualifying childcare providers, who claim through Part AC.
Can a nonresident filing Form 40NR claim the credit for taxes paid to other states?
Part A is printed “Form 40 Only”, and the instructions limit it to legal residents of Alabama with income taxed by Alabama and another state in the same year. Part I, the foreign tax credit, is also Form 40 only.
Official sources and review date
- Form 40 (2025) with Schedule OC, Alabama Department of Revenue
- Form 40NR (2025) with Schedule OC, Alabama Department of Revenue
- Schedule OC instructions, tax year 2025
- Form 40 booklet, tax year 2025
- Form 40NR booklet, tax year 2025
- Individual Income Tax: General Information for Individuals, Alabama Department of Revenue