Nebraska Form 521, the Real Estate Transfer Statement, is the one-page statement a buyer hands to the county register of deeds together with the deed. The register uses it to record the deed and to note the documentary stamp tax, then sends it on to the county assessor. The form says it plainly at the top: the deed will not be recorded unless the statement is signed and items 1 to 27 are accurately completed. The current version is Form No. 96-269-2008, Rev. 6-2026, which replaced the August 2025 revision.
Who files Form 521 and when it goes in
The instructions put the duty on the grantee. Any grantee, or the grantee’s authorized representative, who wants to record a deed to real property must file Form 521, and the grantee signs it. The seller (grantor) appears in item 5 but does not sign.
It is filed with the register of deeds at the moment one of these documents is presented for recording:
- a deed
- a land contract or a memorandum of contract
- a death certificate being recorded under a transfer on death deed
There is no separate state deadline: the statement travels with the document being recorded. The documentary stamp tax works the other way around, because it is imposed on the grantor executing the deed, and it is due when the deed is presented for recording; each county’s register of deeds collects it.
A manufactured home sold on a certificate of title uses a different form. Form 521MH, the Manufactured Housing Transfer Statement, is filed by the purchaser with the county treasurer when applying for the title, and the treasurer cannot deliver the title without it. On Form 521 itself, box C in item 7 is checked when the real estate being deeded is also a mobile home.
How to fill out Form 521, item by item
The Department of Revenue publishes the form as a fillable PDF with its instructions on page 2. The numbers in the image below are the item numbers printed on the form; S marks the signature block. Items 5, 6 and 20 can continue on an attached sheet, and the form asks you to identify the item number on any attachment.
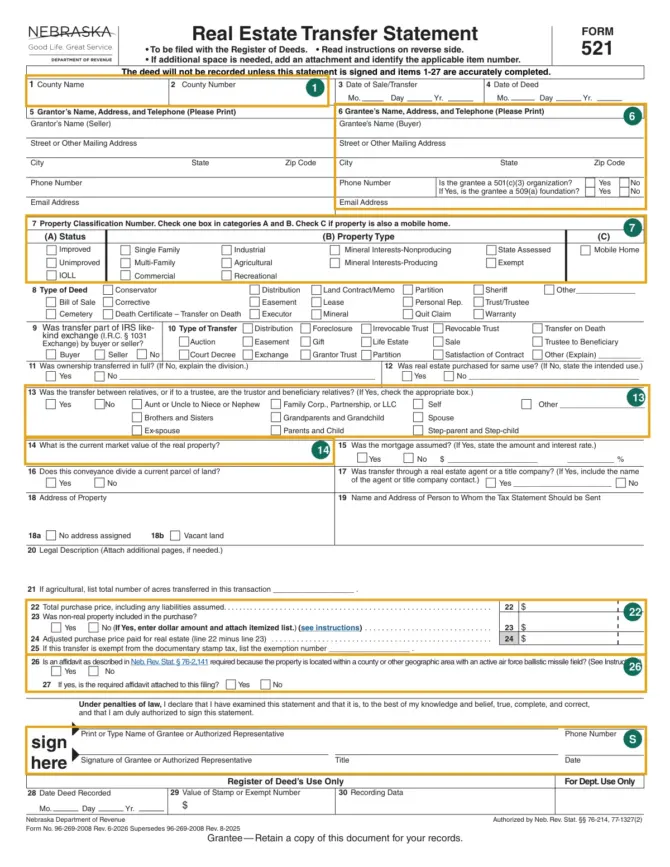
| Item | Printed label | What goes in it |
|---|---|---|
| 1 and 2 | County name, county number | The county where the property lies. If it lies in more than one county, the county where the transfer is being filed. The fillable PDF has a drop-down listing each county with its number, from “Adams – 01” to “York – 93”. |
| 3 | Date of sale/transfer | Month, day and year of the sale or transfer. |
| 4 | Date of deed | The date the grantor signed the deed, unless the deed specifies another date. |
| 5 | Grantor’s name, address and telephone | Every seller, with address, phone and email. Corporations, trusts and partnerships give a business address. |
| 6 | Grantee’s name, address and telephone | Every buyer, in the same way, plus two yes/no boxes: is the grantee a 501(c)(3) organization, and if so, is it a 509(a) foundation. |
| 7 | Property classification number | One box in category A (Improved, Unimproved or IOLL) and one in category B (property type). “Improved” means land with a building or structure; “IOLL” means improvement on leased land. Category C only for a mobile home. |
| 8 | Type of deed | Every box that applies, for example Warranty, Quit Claim, Personal Rep., Trust/Trustee or Death Certificate, Transfer on Death. |
| 9 | IRS like-kind exchange | Buyer, Seller or both if the property was part of an I.R.C. § 1031 exchange; otherwise No. |
| 10 | Type of transfer | Every box that applies: Sale, Gift, Foreclosure, Revocable Trust, Transfer on Death and so on. |
| 11 | Ownership transferred in full | If only part of the ownership passed, check No and explain the division. |
| 12 | Purchased for same use | If No, state the intended use. The instructions give a vacant lot becoming a cemetery and an agricultural lot becoming a subdivision as changes in use. |
| 13 | Transfer between relatives | Yes or No, and the relationship box (spouse, ex-spouse, parents and child, family corporation, partnership or LLC, self and others). For a deed to a trustee, the question is whether the trustor and beneficiary are relatives. |
| 14 | Current market value | The price a willing buyer would pay a willing seller in the ordinary course of trade. An easement created or transferred for no consideration may be listed at $0. |
| 15 | Mortgage assumed | If the grantee took over a mortgage as part of the price, Yes with the dollar amount and interest rate. |
| 16 | Divides a current parcel | Yes if the transfer splits the property into two or more parcels. |
| 17 | Real estate agent or title company | If Yes, the name of the agent or title company contact. |
| 18 | Address of property | The street address, or box 18a (no address assigned) or 18b (vacant land). |
| 19 | Person to receive the tax statement | Name and address for the property tax statement. |
| 20 | Legal description | Taken from the deed of record or from surveys of the property; attach pages if needed. |
| 21 | Agricultural acres | Total agricultural or horticultural acres in the sale, if any. |
Items 8 and 10 are the two “check all that apply” lists, so a sale by a personal representative to a buyer can carry both Personal Rep. in item 8 and Sale in item 10. In item 7 the rule is the opposite: exactly one box in A and one in B.
Price lines 22 to 25 and the documentary stamp tax
Lines 22 to 24 separate the real estate from everything else that changed hands. Line 22 is the total purchase price or consideration paid or to be paid, counting cash, mortgages, property traded, assumed liabilities, leases, easements and personal property purchased. Line 23 is the value of things inside that price that are not real property; the instructions name machinery, irrigation equipment, household goods and boat docks. Line 24 is line 22 minus line 23.
Say a farm sells for $215,000 and the price includes irrigation equipment valued at $15,000. Line 22 is $215,000, line 23 is $15,000 with Yes checked, and line 24 is $200,000. The itemized list with a cost breakdown must be attached whenever line 23 has an amount. With nothing of that kind in the sale, check No and enter zero.
The tax rate is printed on page 2 of this revision: $2.32 for every $1,000 of value until July 17, 2026, and $3.32 from July 18, 2026. The Department’s exemption sheet ties the new rate to deeds recorded on or after July 18, 2026. Its calculation example divides the consideration by 1,000, rounds up to the next whole number and multiplies by the rate, since the statute charges for each $1,000 “or fraction thereof”. On consideration of $180,400 that is 181 × $3.32 = $600.92. Where the consideration is only nominal, the current market value is divided instead.
Line 25 is for the exemption number when the deed is exempt. The Department’s Documentary Stamp Tax Exemptions sheet (96-285-2009, Rev. 7-2026) numbers them 1 to 26. A few that match boxes elsewhere on Form 521:
| Exemption | Covers | Related item on Form 521 |
|---|---|---|
| 4 | Deeds that confirm, correct or supplement an earlier deed without extra consideration, including deeds into the grantor’s revocable trust | Item 8 Corrective; item 10 Revocable Trust |
| 5(a)(i) | Deeds between spouses, ex-spouses (property from the marriage) or parent and child, without actual consideration | Item 13 relationship boxes |
| 5(a)(ii) | Deeds to or from a family corporation, partnership or LLC, under the conditions on the sheet | Item 13 Family Corp., Partnership, or LLC |
| 13 | Land contracts, including memoranda | Item 8 Land Contract/Memo |
| 16 and 17 | Transfer on death deeds and their revocations; certified death certificates | Item 8 Death Certificate, Transfer on Death |
| 20 | Deeds from a trustee to a beneficiary of the trust | Item 10 Trustee to Beneficiary |
| 25 | Deeds without actual consideration to a 501(c)(3) organization that is not a private foundation under § 509(a) | Item 6 nonprofit questions |
The form’s instructions add that all deeds are presumed taxable unless the exemption clearly appears on the face of the deed or sufficient documentary proof is presented. Some exemptions on the sheet carry their own proof requirement, such as the merger plan filed with the Secretary of State for exemption 8 or the signed statement for deeds into a trust under exemption 19. When the exemption number goes on line 25, the register writes it in item 29 in place of a stamp value.
Items 26 and 27: missile field counties and Form 521-AFF
Item 26 asks whether an affidavit under Neb. Rev. Stat. § 76-2,141 is required because the property is in an area with an active air force ballistic missile field. The instructions list the areas:
- all of Banner, Cheyenne, Kimball and Scotts Bluff counties
- Deuel County south of Township 15 North and west of Range 43 West
- Garden County south of Township 19 North and west of Range 43 West
- Morrill County, except lands north of Township 21 North
- Sioux County, except lands north of Township 26 North and east of Range 57 West
The townships and ranges refer to the Bureau of Land Management’s Public Lands Survey System. If item 26 is Yes, item 27 asks whether the affidavit is attached. The Department publishes it as Form 521-AFF, Affidavit Refuting Foreign Government Affiliation (96-346-2024): the purchaser certifies under penalty of perjury that they are not affiliated with any foreign government or nongovernment person determined to be a foreign adversary under 15 C.F.R. 7.4. It is signed before a notary public or a designated county official.
Signing the statement and what the register of deeds does next
Below item 27 the grantee or an authorized representative prints a name, adds a phone number, signs, and enters a title and the date, declaring under penalties of law that the statement is true, complete and correct. Form 521 does not say what proof of authority a representative must show. It also does not refer to Nebraska Form 33, which appoints a representative for tax matters before the Department of Revenue.
Items 28 to 30 belong to the register of deeds: the date the deed was recorded, the value of the stamp or the exempt number, and the recording data. Once items 1 to 30 are complete, the register forwards the original Form 521 to the county assessor and keeps a copy. The footer tells the grantee to keep a copy as well.
What keeps a deed from being recorded
The instructions to the register of deeds are short and strict. A deed is not recorded when any of these is true:
- One of items 1 through 27 has not been completed.
- The statement has not been signed by the grantee or an authorized representative.
Several items have their own attachments, and the instructions spell them out. A Yes on line 23 needs the itemized list with a cost breakdown. A Yes on item 26 needs the affidavit marked in item 27. An exemption claimed in connection with a § 1031 exchange in item 9 needs a copy of the exchange agreement for the recording office. And an exemption on line 25 has to be visible on the deed or backed by documentary proof, since every deed starts out presumed taxable.
Where to get Form 521 and where it is filed
The fillable Form 521 is listed on the Property Assessment Division’s Real Estate Forms page and again on its Documentary Stamp Tax page, alongside Form 521-AFF, Form 521MH and the exemption list. The forms page labels it 07/2026, while the footer of the PDF reads Rev. 6-2026; both point to the same file. The PDF has Reset and Print buttons at the top.
The completed statement does not go to the Department of Revenue. It is filed with the register of deeds of the county named in item 1, together with the deed. Questions about the form itself can go to the Property Assessment Division, 301 Centennial Mall South, PO Box 98919, Lincoln, NE 68509-8919.
Questions about Form 521
Does the buyer or the seller sign Nebraska Form 521?
The grantee, meaning the buyer, or the grantee’s authorized representative signs and dates it. The seller is listed in item 5 and owes the documentary stamp tax, but there is no seller signature line.
Is Form 521 needed when a transfer on death deed takes effect?
The instructions include a death certificate being recorded under a transfer on death deed among the documents that need Form 521. On the exemption sheet, transfer on death deeds are exemption 16 and certified death certificates are exemption 17.
Where do I find the county number for item 2?
The fillable PDF’s county drop-down shows the number next to each county name, for example Adams – 01. The instructions also point to revenue.nebraska.gov/PAD.
Do I use Form 521 for a mobile home?
Form 521MH is for manufactured housing sold with a certificate of title and goes to the county treasurer. Form 521 has a mobile home box in item 7, category C, for real estate being deeded that is also a mobile home.
Official sources
- Nebraska Department of Revenue, Form 521, Real Estate Transfer Statement, Form No. 96-269-2008 Rev. 6-2026
- Nebraska Department of Revenue, Property Assessment Division, Real Estate Forms
- Nebraska Department of Revenue, Property Assessment Division, Documentary Stamp Tax
- Nebraska Department of Revenue, Documentary Stamp Tax Exemptions, 96-285-2009 Rev. 7-2026
- Nebraska Department of Revenue, Documentary Stamp Tax Calculation Example, July 18, 2026
- Nebraska Department of Revenue, Form 521-AFF, Affidavit Refuting Foreign Government Affiliation (96-346-2024)
- Nebraska Department of Revenue, Form 521MH, Manufactured Housing Transfer Statement