Nebraska Form 501N accompanies a monthly income tax withholding deposit paid by check or money order. If you make the deposit electronically, the department says not to mail or e-file this voucher. The payment still has to be made; the paper form is used only for the paper-payment route.
Who needs a monthly withholding deposit?
The form’s instructions require monthly deposits when withholding exceeds $500 in either of the first two months of a calendar quarter. The department’s withholding regulation, REG-21-007.02, places those deposits in the second and third months of the quarter and credits them against the next quarterly Form 941N liability.
The 2026 Circular EN makes the two monthly tests explicit: a deposit is required for the first month if that month’s withholding exceeds $500. For the second month, a deposit is required if withholding exceeded $500 in either the first or second month.
Use the deposit rules for the first and second months, then account for the third month’s payment through Form 941N. Form 501N does not replace that quarterly return. The instructions also require a Nebraska withholding license before filing the deposit. If not licensed, they direct you to complete Nebraska Tax Application, Form 20, and mail it with Form 501N.
The current withholding forms list supplies the one-page Form 501N marked 8-008-1967 Rev. 7-2024. Its revision date identifies the form edition; there is no preprinted tax year restricting the month you enter.
How to fill out the paper Form 501N
Have the Nebraska withholding account details, payroll withholding totals and payment month ready. The five outlines in the illustration follow the address, account, period, amount and signature areas.
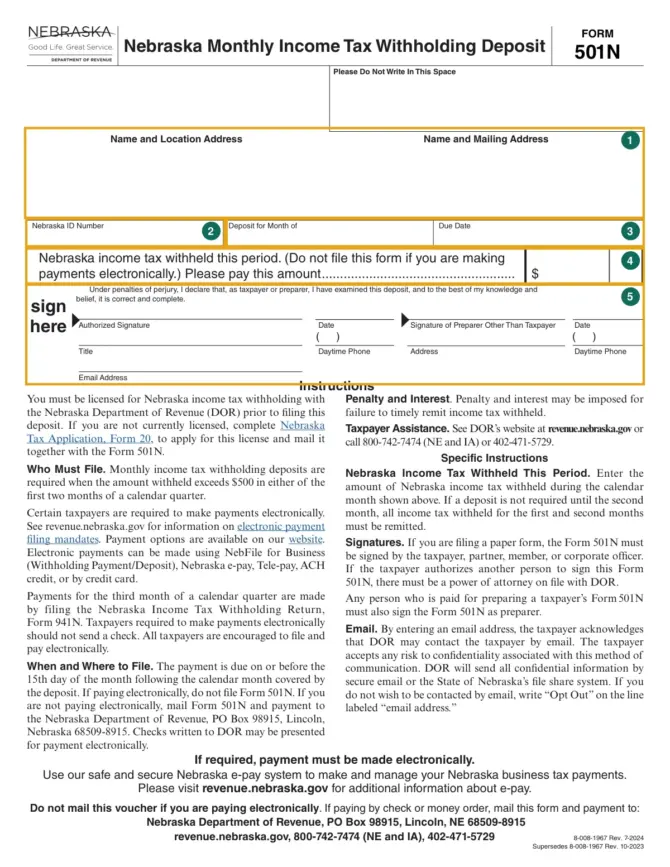
| Area | What to enter | Record to use |
|---|---|---|
| 1: name and addresses | The name and location address, and the name and mailing address in their separate areas. | The business’s withholding registration and current mailing details. |
| 2: Nebraska ID number | The state withholding account ID. | The Nebraska account record, rather than substituting a federal EIN. |
| 3: deposit month and due date | The calendar month covered and the payment due date. | The monthly payroll record and the due-date rule below. |
| 4: Nebraska income tax withheld this period | The amount to remit for the relevant month, including first-month withholding where the first deposit is required in month two. | Payroll withholding totals and the first month’s deposit position. |
| 5: taxpayer and preparer details | Required signatures and dates, title, daytime phone, email choice, and the preparer’s address and phone where applicable. | The person authorized to sign and any paid preparer’s details. |
The instructions say that if a deposit is not required until the second month, the payment must include all withholding for both the first and second months. For example, if the first month has $300 withheld and the second has $650, the second-month deposit is $950. Those are illustrative payroll amounts; the $500 trigger and combined payment rule come from the form.
The taxpayer, partner, member or corporate officer must sign a paper Form 501N. If another person is authorized to sign, a power of attorney must be on file with the department. The Nebraska Form 33 guide covers the appointment of a tax representative. A paid preparer must also sign Form 501N as preparer; that signature is additional to the taxpayer’s authorized signature.
Providing an email address accepts the confidentiality risk described in the form’s instructions. The department says confidential information will be sent through secure email or the state’s file-share system. If you do not want email contact, write “Opt Out” on the email-address line. Leave the space labeled “Please do not write in this space” for the department.
When is the deposit due?
The payment is due by the 15th day of the month after the month covered by the deposit. That gives a February 15 due date for a January deposit and a March 15 due date for a February deposit, before any weekend or legal-holiday adjustment. March’s withholding is handled through the quarterly Form 941N route.
The department’s withholding FAQ says a due date falling on a weekend or legal holiday moves to the next business day, regardless of payment method. Electronic payment services have their own scheduling requirements, so use the instructions for the chosen service when arranging the payment.
Form 501N warns that penalty and interest may be imposed for failure to remit withholding on time. Filling in the voucher without sending the payment does not make the deposit.
When electronic payment replaces the voucher
Some employers must pay electronically. The electronic payment mandate page applies a prior-year payment threshold to particular tax programs, including income tax withholding, and states a $5,000 threshold from July 2017. Check your withholding program’s mandate before choosing a paper payment; the threshold concerns prior-year payments, rather than the size of this single deposit.
The same page states a $100 penalty for noncompliance with a required electronic payment. A paper Form 501N is therefore not an alternative for an employer required to pay electronically. The form offers electronic choices including NebFile for Business, Nebraska e-pay, Tele-pay, ACH credit and credit card.
The withholding online filing page has a separate payment/deposit service for scheduling the withholding payment or monthly deposit. The FAQ explains that Form 501N itself is neither mailed nor e-filed when the deposit is paid electronically.
Official PDF and mailing address for paper payments
Download the official Nebraska Form 501N PDF. Where paper payment is permitted, mail the completed voucher and check or money order to:
Nebraska Department of Revenue
PO Box 98915
Lincoln, NE 68509-8915
The form says checks written to the department may be presented for payment electronically. Do not send a second paper voucher for a deposit already paid through an electronic service.
For help with the deposit or withholding account, the form lists 800-742-7474 for Nebraska and Iowa callers and 402-471-5729. Keep the period, account number and payment details available when asking the department about a deposit.
Sources
- Nebraska Department of Revenue, Form 501N and instructions, Rev. 7-2024.
- Nebraska Department of Revenue, current income tax withholding forms.
- Nebraska Department of Revenue, REG-21-007: employer returns and payment of withheld taxes.
- Nebraska Department of Revenue, Circular EN for wages paid from January 1, 2026: monthly deposits.
- Nebraska Department of Revenue, withholding FAQs.
- Nebraska Department of Revenue, electronic payment mandates.
- Nebraska Department of Revenue, online withholding returns and payments.