CGT Payslip A identifies a payment of Irish Capital Gains Tax for disposals between 1 January and 30 November 2026. The payment deadline printed on this copy is 15 December 2026. A disposal in December belongs to the later payment period and uses Payslip B where a paper payslip is permitted.
The payslip sends payment details to Revenue. It does not calculate the gain and does not replace the separate CGT return. Work out the taxable amount and any relief or loss treatment before entering the payment.
Who may use a paper CGT payslip?
Revenue’s payment guidance, published on 27 October 2026, says that a person not registered for CGT must register and pay online using ROS or myAccount. People exempt from mandatory e-filing can use an appropriate payslip with payment, or contact the Payment Accounting section of the Collector-General’s Division. The downloadable paper form is for cheque payments.
Check that rule before choosing paper merely because you do not use ROS. The PDF describes non-ROS customers using the payslip, while the current payment page expressly sets out the mandatory e-filing exception. Follow that current eligibility rule.
Register with your tax reference number or PPSN. In ROS, use My Services, Other Services, Manage Tax Registrations and select CGT. In myAccount, use Manage My Record, Tax Registrations, then Register on the CGT line. Registration is needed to make a payment, and you do not need to register again for later disposals once registered.
How to complete the name, PPSN and amount fields
Use the 2026 copy whose payment period is printed beside the amount field. The three marked areas identify the payer’s name and address, PPSN and whole-euro payment.
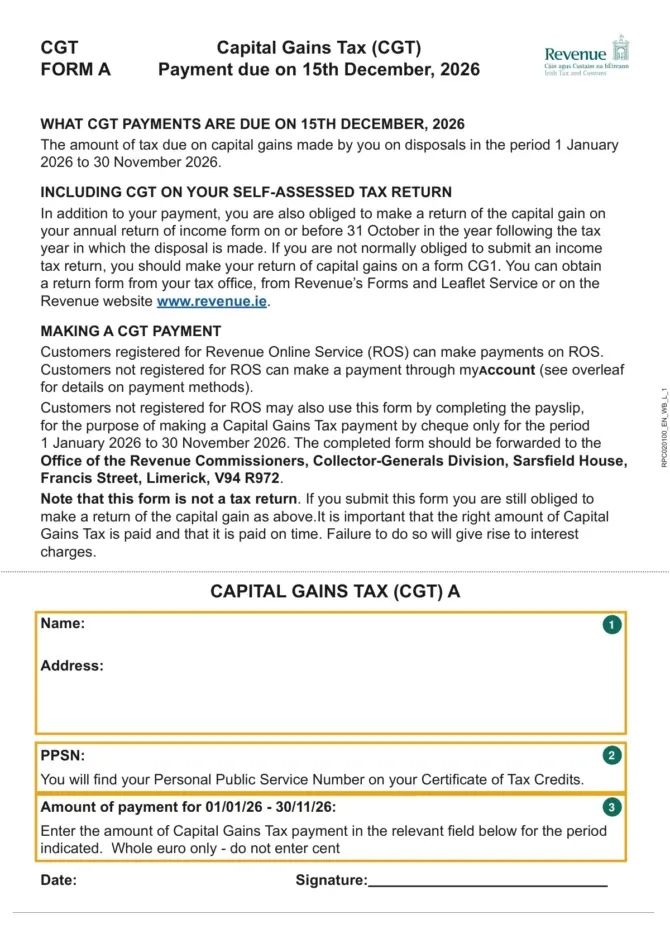
| Field | Entry | Where to check it |
|---|---|---|
| Name | The person making the CGT payment | Revenue taxpayer details |
| Address | Correspondence address | Current contact record |
| PPSN | Personal Public Service Number | The PDF identifies the Certificate of Tax Credits as a source |
| Amount for 01/01/26 to 30/11/26 | CGT payment in whole euro, without cents | The CGT calculation for the initial 2026 period |
| Date and signature | Completion date and signature | The person completing the payslip |
Enter the tax payment, not the sale proceeds. For a hypothetical payment of €640 already established from your CGT calculation, the whole-euro amount field contains 640. The example does not calculate tax or imply a tax rate.
When do the payment and return fall due?
Pay CGT for the initial period by 15 December of the same year. For 2026, this is 15 December 2026. December disposals are payable by 31 January of the following year. Under a written contract, Revenue says the disposal date is usually the contract date; do not choose the payment period solely from the date the money reached the bank.
The return is due by 31 October in the year after disposal. A return is required even when reliefs or allowable losses leave no tax payable. Late payment incurs interest; Revenue also states that a late return incurs a penalty. The payslip notes advise allowing at least three working days for payment to reach the Collector-General by its due date.
The return form depends on your tax affairs. Revenue lists CG1 for people who do not usually file an annual return or use the online Form 12; CG1 is paper-only. A PAYE taxpayer required to file a return uses paper Form 12 for CGT, because eForm 12 cannot report it. Self-employed filers use Form 11, trusts or estates use Form 1, and companies use CT1. The online filing routes for Forms 11, 1 and CT1 are through ROS.
Pay online or send an eligible cheque payment
ROS customers pay through ROS. Eligible myAccount users can pay by debit or credit card, or a Single Debit Instruction from a bank account. The PDF says myAccount payment is available to those currently or previously registered for CGT.
For a permitted paper cheque payment, send the completed Payslip A to Office of the Revenue Commissioners, Collector-General’s Division, Sarsfield House, Francis Street, Limerick, V94 R972. Keep the payment record for the CGT paid entry on the later return. The return itself has a different filing destination or online route, set out on Revenue’s payment-and-filing page.
Queries about liability go to your local Revenue office; queries about the payment go to the Collector-General. For asset transfers requiring a clearance certificate, CG50A concerns a separate purchaser-withholding process. An adviser should settle any uncertainty about the gain, exemptions or losses before payment.
Official PDF: CGT Payslip A — Official PDF (revenue.ie)