Form 1 (Firms) is the return a partnership makes to Revenue for its income and capital gains. The 2025 version covers the year ended 31 December 2025 and also lists the chargeable assets the partnership acquired in that year. It runs to 11 pages, set out in lettered panels from A to K, with the Expression of Doubt on the last page. The partnership itself pays no tax with it: the return reports the firm’s figures and how they are split, and each partner then makes a separate personal return on Form 11.
Who makes the return for the partnership
Section 959I of the Taxes Consolidation Act 1997 puts the duty on the precedent partner, and the front page of the form says who that is:
- the partner named first in the partnership agreement;
- if there is no agreement, the partner named alone or first in the usual name of the firm;
- if that partner is not an acting partner, the precedent acting partner.
Where no partner is resident in the State, the return is made by the firm’s agent, manager or factor resident in the State. Revenue’s Tax and Duty Manual Part 43-00-03 adds that the precedent partner prepares and files the return under section 880 and is treated by section 959M as the chargeable person in respect of it. The same manual says capital allowances of the partnership are a joint allowance claimed by the precedent partner on this form.
The precedent acting partner is also the person Revenue deals with on the partnership’s registration, according to Tax and Duty Manual Part 38-01-03a. A partnership not resident in Ireland that has to register for income tax uses TR1(FT); a resident one uses Form TR1 or eRegistration.
Partnerships are tax transparent for Irish direct tax. The partners, not the firm, are taxed on their share of the income and gains, and Part 43-00-03 says the profits each partner returns on Form 11 must be computed on the same basis as the partnership figures. A partner cannot deduct personal expenses from the partnership share in their own return.
Deadline for the 2025 return and what happens if it is late
The 2025 form states that the return must be delivered on or before 31 October 2026. Revenue eBrief No. 034/26 extended the 2026 date to Wednesday 18 November 2026 for customers who file their 2025 Form 11 and pay through ROS, and for certain Capital Acquisitions Tax returns. The eBrief does not mention Form 1 (Firms), and the form itself gives only 31 October 2026. Ask your Revenue office before relying on the later date for the partnership return.
If the precedent partner does not file Form 1 (Firms), Part 43-00-03 says a fixed penalty under section 1052 may apply. That penalty is separate from the partners’ own position: each partner is responsible for their own return and can be charged tax, interest and penalties individually.
When an inspector makes a determination on the total profits of the partnership or the joint capital allowances, the notice goes in writing to the precedent partner. Any partner may appeal it to the Tax Appeals Commission within 30 days of the date of the notice (section 1012).
Panel A: partnership details and each partner’s share
Panel A runs across pages 2 and 3, and the form asks for entries on both pages where they apply. Page 2 holds the details in the image below; page 3 continues the same partner rows with the changes columns.
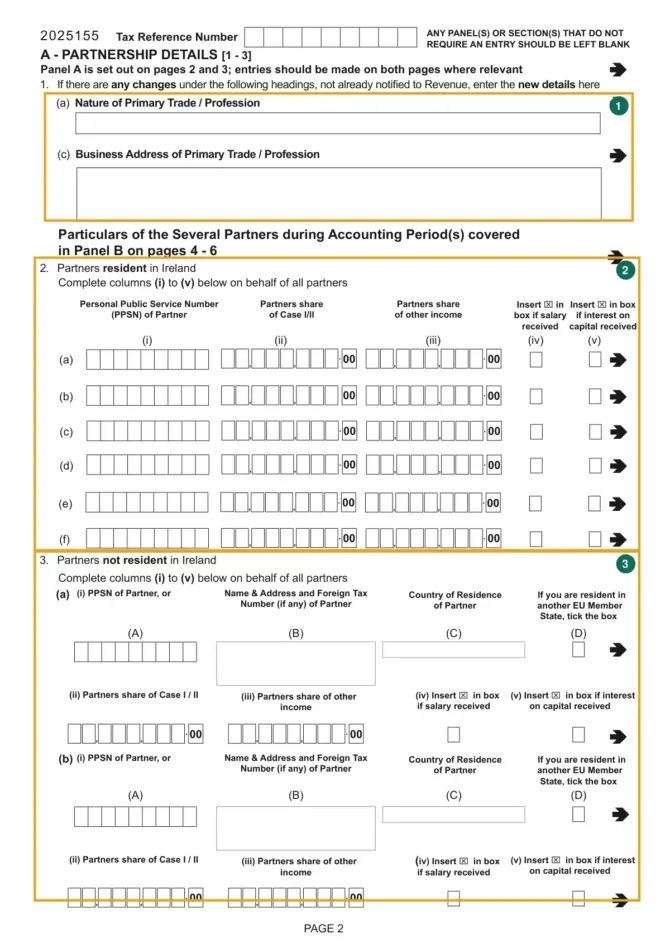
| Line | What the form asks | Notes |
|---|---|---|
| 1(a), 1(c) | Nature and business address of the primary trade or profession | Only changes not already notified to Revenue. |
| 1(b) | Name and address of the precedent acting partner | On page 3, same rule: new details only. |
| 2, columns (i) to (v) | Partners resident in Ireland: PPSN, share of Case I/II, share of other income, x if salary received, x if interest on capital received | Complete for all partners. Six rows, (a) to (f). |
| 3, columns (i) to (v) | Partners not resident in Ireland: PPSN, or name, address and foreign tax number; country of residence; tick if resident in another EU Member State; then the same share and x boxes | Complete for all non-resident partners. |
| 2 and 3, columns (vi) to (xi) | Basis of distribution of profits at start of period (%), x if partner commenced, x if partner ceased, x if the distribution changed, date of event, basis at end of period (%) | Only if the partnership or the profit-sharing basis changed in the accounting period. Percentages are after salary and interest on capital. |
The percentages come from the profit-sharing ratio in the partnership agreement. Part 43-00-03 says that without an agreement, profits and losses are shared equally, and losses are allocated on the same profit-sharing ratio and claimed by the individual partners.
Columns (vii), (viii) and the date of event matter for the partners’ own assessments. A new partner is assessed as commencing from the date of joining and gets a share of profits from that date; a departing partner is assessed under the cessation rules up to the date of leaving. Because the precedent partner claims capital allowances for the firm, a partner leaving does not trigger a balancing event.
Panel B: trade profits and extracts from accounts
Panel B, on pages 4 to 6, has two columns, Primary Trade and Subsidiary Trade. Do not send the accounts with the return: the form asks for an extract of figures from them in lines 111 to 157 instead.
| Lines | What goes in |
|---|---|
| 101 to 103 | Description of the trade (it must be clearly described), whether it includes relevant operations for Relevant Contracts Tax (construction, forestry, meat processing), and the date of cessation if the source ceased in 2025 |
| 104, 105 | Adjusted net profit or adjusted net loss for the accounting period |
| 106, 107 | Reverse premiums under section 98A(4) if not already included, and balancing charges |
| 108 to 110 | Capital allowances for the current year: machinery and plant, industrial or farm buildings, other |
| 111, 112 | Accounts information period, from and to (must be completed) |
| 113 | The earlier Form 1 (Firms) with which accounts information for this period was already submitted, if any |
| 114 | x if the partnership is a Registered Farm Partnership under section 667C |
| 115 to 119 | Sales or turnover, receipts from government agencies such as GMS, other trading income, purchases, gross trading profit (a loss as a minus figure) |
| 120 to 131 | Expenses: wages, other staff costs, RCT and other sub-contractors, professional fees, motor and travel, repairs, rent, depreciation, provisions, other expenses and credit entries |
| 132 to 143 | Capital account and balance sheet: capital introduced, drawings, closing capital, stock, debtors, cash, loans, client account balances, creditors, tax creditors, net assets |
| 144 to 157 | Net profit or loss per accounts, the adjustments (motor, donations and entertainment, light, heat and phone, gains or losses on fixed assets, stock relief under sections 666, 667B and 667C, carbon tax under section 664A, other addbacks and deductions), then the adjusted net profit or loss |
Lines 111 to 157 have to be completed in every case where the partnership carries on a trade or profession, except where line 113 applies. Line 146 is a single x for a year with no adjustments to the profit or loss per accounts.
The adjustments follow the sole trader rules. Section 1008(3)(a)(iii), as Part 43-00-03 explains it, computes the full adjusted profit or loss as if one person had carried on the trade, so the same addbacks and restrictions apply.
Lines 108 to 110 are the joint allowance. Each partner’s share of it follows the profit-sharing ratio (section 1010(7)), and a balancing charge is shared the same way. A partner who cannot use their share does not carry it forward personally: the unused allowances of all partners are added together, carried forward and allocated in later years on the agreed ratios.
Under the expenses lines the form carries a reminder about Form 46G. If the partnership paid any one person more than €6,000 in total during 2025 for services in the course of the trade or profession, a Form 46G has to be completed as well.
Panels C to I: rental, investment and foreign income of the firm
These panels are for income the partnership receives outside its trade. Leave any panel that does not apply blank.
| Panel and lines | What it covers |
|---|---|
| C, 201 | Exempt profits, gains or distributions from woodlands, or the loss |
| D, 301 to 305 | Irish residential lettings: x if Part 7 of the Residential Tenancies Act 2004 registration was complied with for all 2025 tenancies, number of properties, gross rent, repairs, allowable interest, “Section 23” type relief in its first year of claim, pre-letting expenditure under section 97A, net profit or loss |
| D, 306 to 313 | Commercial property and land: number, area in hectares, rent, expenses, net profit or loss; then the total of lines 305 and 310 (0.00 if a loss), capital allowances for 2025 and losses for the year |
| E, 314 to 320 | Other Irish income: untaxed interest, deposit interest gross before retention tax, gross distributions including dividend withholding tax, patent royalties and section 757 patent rights sales, other income, and investment undertaking deemed disposals with the fund’s name and address |
| F, 401 to 417 | Foreign income in euro, plus details of foreign bank accounts opened in 2025, foreign life policies issued in 2025, material interests in offshore funds and other offshore products acquired in 2025 |
| G, 501 | Income from sources not shown elsewhere, including sums received after the trade ended and sums treated as partnership income under section 806 |
| H, 601 to 605 | Rents paid to non-residents with tax deducted, clawback of employer’s tax relief at source on employees’ medical insurance, charges and annuities, loan and overdraft interest, donations to approved sports bodies |
| I, 701 to 703 | Profits apportioned under section 1008(2)(a)(ii), and why the partners’ shares add up to less than the full partnership profit |
Two points on the form itself are easy to get wrong. Line 602 asks for the amount of tax relief at source granted on the premiums, and the form says not to enter the premiums. In Panel F, foreign rental losses can only be offset against foreign rental profits, and income from the foreign accounts, policies and funds listed at lines 402 to 417 is reported at line 401.
Panels J and K: assets acquired and capital gains
Panel J (lines 801 to 808) counts the chargeable assets the partnership acquired in 2025 and the consideration given, by type: shares, residential and commercial premises, agricultural and development land, business assets, antiques and works of art, other.
Panel K (lines 901 to 917) covers disposals in 2025. For each asset type there are columns for the number of disposals, an x for disposals between connected persons, the aggregate area in hectares and the aggregate consideration, using market value where the disposal was not at arm’s length. Line 909 totals the consideration, then lines 910 to 915 take it down to the chargeable gain: incidental costs, net consideration, cost of acquisition (market value for assets acquired before 6/4/1974 or not at arm’s length, indexed where appropriate), enhancement expenditure, and relief under section 604A.
Lines 916 and 917 split the gain between the partners resident and not resident in Ireland, with each partner’s basis of distribution and amount. Section 30, as Part 43-00-03 describes it, apportions gains on partnership assets between the partners, who are then charged separately. For the connected persons column, the same manual notes that partners are connected with each other under section 10(5), except for acquisitions and disposals of partnership assets under bona fide commercial arrangements.
Expression of Doubt and the declaration
Page 11 is only for a genuine doubt about how tax law applies to an item in the return (section 959P), not for general notes. Insert T in the box and fill in (a) the facts, (b) the doubt and the law behind it, (c) the amount of tax in doubt, (d) the supporting documents, which go with the return, and (e) any published Revenue guidelines you consulted. Each partner affected by the treatment should also indicate an Expression of Doubt on their own personal return.
The declaration on page 1 has to be signed and dated, with the capacity of the signatory. The contact block takes an agent’s TAIN, a contact name, the client’s reference and a phone number or email for queries about the return.
Getting the 2025 Form 1 (Firms) and sending it
Revenue publishes the 2025 Form 1 (Firms) as a PDF. Earlier years are at the same address with the year added, such as form1-firms-2024.pdf.
Form 1 (Firms) is one of the specified returns that must be filed through ROS, according to the list in Tax and Duty Manual Part 38-01-03a. Paper is for partnerships Revenue has excluded from mandatory e-filing because they lack the capacity to file electronically; a refused exclusion can be appealed to the Tax Appeals Commission within 30 days.
For a paper return, the form asks for blue ink, dates as day/month/year, a separate schedule in the same layout where a panel runs out of space, and no stamp. Use any envelope, write “Freepost” above the address and send it to:
Office of the Revenue Commissioners
Collector-General’s Division
PO Box 354
Limerick
Questions about Form 1 (Firms)
Does the partnership pay tax when it files Form 1 (Firms)?
The partnership is tax transparent, so the partners are taxed on their shares through their own returns. Tax and Duty Manual Part 38-01-03a lists Form 1 (Firms) as a specified return with no specified tax liability attached.
Do I attach the partnership accounts?
The form says not to. Give the extracts in lines 111 to 157, unless line 113 points to an earlier Form 1 (Firms) that already carried the accounts information for this period.
Does a partner still need to file Form 11?
Each partner makes a separate personal return on Form 11 in addition to the partnership return, using the same profit figures and sharing basis shown on Form 1 (Firms).
Official sources
- Revenue, Form 1 (Firms), Partnership Tax Return 2025
- Revenue, Tax and Duty Manual Part 43-00-03, Taxation of Partnerships (July 2025)
- Revenue, Tax and Duty Manual Part 38-01-03a, Guidelines for Registration (reviewed September 2026)
- Revenue, eBrief No. 034/26, Pay and File Extension Date 2026
- Revenue, Pay and file