Form PRT-PSI is Delaware’s own Schedule K-1 for partnerships. A partnership that files the Delaware partnership return, Form PRT-RTN, prepares one PRT-PSI for each person who was a partner at any time during the year, showing that partner’s share of income and deductions twice: once as the federal Schedule K-1 amount and once as the portion from Delaware sources. The current form is the 2025 PRT-PSI, Revision 20250730, published by the Delaware Division of Revenue.
Which partnerships prepare Form PRT-PSI
The 2025 PRT-RTN instructions (revised 05/27/25) say a partnership return must be completed by any business treated as a partnership for federal purposes that has income or loss, of any amount, derived from or connected with a Delaware source. A partnership with no Delaware-sourced income or loss does not file. Delaware-source income includes income from real or tangible personal property located in Delaware, from intangible property used in a business carried on in Delaware, and from a trade, business, profession or occupation conducted in Delaware.
The partnership itself is not taxed. Its partners owe Delaware personal income tax on their shares, and Form PRT-PSI is how each partner learns its share. The same section of the instructions sends partners to different returns:
- A Delaware resident partner files Form PIT-RES and reports the full share of partnership income or loss.
- A non-resident partner of a partnership with Delaware-source income files Form PIT-NON or a composite return and reports the share of Delaware-sourced partnership income or loss. On PIT-NON that goes on line 10, Column B, which the 2025 PIT-NON instructions describe as income or loss from property located in Delaware or from doing business in Delaware.
A typical case: a New Jersey resident holds 25% of a partnership that rents out a warehouse in Wilmington and also owns property in Pennsylvania. The partnership’s PRT-PSI for that partner shows the federal K-1 figures in Column A and only the Delaware-sourced part in Column B, and the partner carries the Delaware part to PIT-NON.
How to fill out the top of PRT-PSI
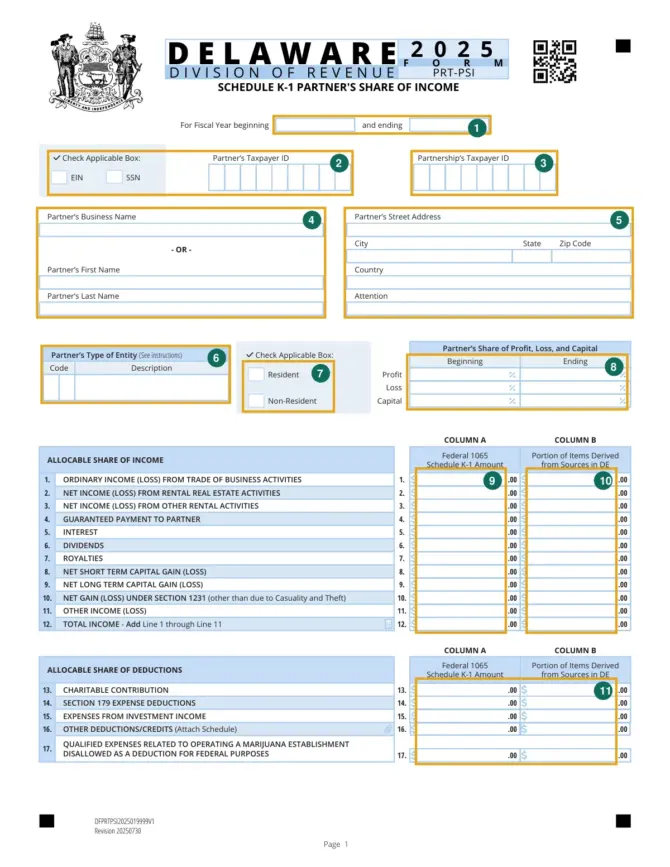
The form is a single fillable page. The numbers below follow the markers on the image, not printed line numbers; the printed lines 1 to 17 are covered in the next section.
| Marker | Field | What goes in it |
|---|---|---|
| 1 | For fiscal year beginning / and ending | The start and end dates of the partnership’s fiscal year, if it does not use the calendar year. |
| 2 | EIN or SSN box, Partner’s Taxpayer ID | An SSN or ITIN for an individual partner, an EIN for every other partner, with the matching box checked. |
| 3 | Partnership’s Taxpayer ID | The partnership’s own taxpayer ID. |
| 4 | Partner’s Business Name, or First Name and Last Name | A business name for an entity partner, or the first and last name of an individual partner. |
| 5 | Street address, City, State, Zip Code, Country, Attention | The partner’s mailing address, with a country and an attention line where needed. |
| 6 | Partner’s Type of Entity, Code and Description | A two-digit code from the list below and its description. |
| 7 | Resident or Non-Resident | The partner’s Delaware residence status. |
| 8 | Partner’s Share of Profit, Loss, and Capital | Percentages at the beginning and the end of the year. |
The ITIN rule comes from the instructions; the printed check boxes read only EIN and SSN, and neither document says which box an ITIN filer checks.
PRT-PSI has no signature line. The partner’s signature and the paid preparer block are on page 2 of Form PRT-RTN.
The entity codes for marker 6 are printed on page 3 of the PRT-RTN instructions:
| Code | Description | Code | Description |
|---|---|---|---|
| 01 | Individual | 08 | Trust |
| 02 | Partnership | 09 | Cooperative |
| 03 | Non-Profit Organization | 10 | Holding/Investment Corporation |
| 04 | Domestic Corporation | 11 | Professional Association |
| 05 | Foreign Corporation | 12 | Bank/Financial Institution |
| 06 | Subchapter Corporation | 13 | Limited Liability Company |
| 07 | Estate | 14 | Other (describe) |
Lines 1 to 17: Column A and Column B
Every line has two amount boxes. Column A is headed “Federal 1065 Schedule K-1 Amount” (marker 9 on the image) and Column B “Portion of Items Derived from Sources in DE” (marker 10 for the income lines, marker 11 for the deductions). The line labels match Schedule 1 of Form PRT-RTN, which names the federal Form 1065 Schedule K line behind each item; the partner’s figure is the matching box of the 2025 federal Schedule K-1 (Form 1065).
| PRT-PSI line | Item | Federal source named on PRT-RTN Schedule 1 |
|---|---|---|
| 1 | Ordinary income (loss) from trade or business activities | Schedule K, line 1 (K-1 box 1) |
| 2 | Net income (loss) from rental real estate activities | Schedule K, line 2 (K-1 box 2) |
| 3 | Net income (loss) from other rental activities | Schedule K, line 3c (K-1 box 3) |
| 4 | Guaranteed payment to partner | Schedule K, line 4c (K-1 box 4c, total guaranteed payments) |
| 5 | Interest | Schedule K, line 5 (K-1 box 5) |
| 6 | Dividends | Schedule K, line 6a (K-1 box 6a, ordinary dividends) |
| 7 | Royalties | Schedule K, line 7 (K-1 box 7) |
| 8 | Net short-term capital gain (loss) | Schedule K, line 8 (K-1 box 8) |
| 9 | Net long-term capital gain (loss) | Schedule K, line 9a (K-1 box 9a) |
| 10 | Net section 1231 gain (loss), other than casualty and theft | Schedule K, line 10 (K-1 box 10) |
| 11 | Other income (loss) | Schedule K, line 11 (K-1 box 11) |
| 12 | Total income | Add lines 1 through 11 in each column |
| 13 | Charitable contribution | Schedule K, line 13a |
| 14 | Section 179 expense deduction | Schedule K, line 12 (K-1 box 12) |
| 15 | Expenses from investment income | Schedule K, lines 13b and 13c |
| 16 | Other deductions/credits (attach schedule) | Schedule K, line 13e, plus Delaware credits passed through on Form BUS-CRS |
| 17 | Qualified expenses of a marijuana establishment disallowed as a federal deduction | No federal line; Delaware-only deduction |
Line 17 follows PRT-RTN line 20. A partnership operating a marijuana establishment under Chapter 13 of Title 4 or Chapter 49A of Title 16 may deduct ordinary and necessary business expenses only if they were not deductible federally because of section 280E of the Internal Revenue Code.
Line 16 also carries credits. Form BUS-CRS (Revision 20250528) tells a partnership to allocate its Delaware business tax credits from lines 28 and 33 among the partners and report each partner’s amount on line 16 of the PRT-PSI it gives that partner. A partner who receives credits then prepares a separate BUS-CRS of its own and works out the allowable credit against its own Delaware tax.
What Column B should add up to
The Column B rule is a single sentence on page 3 of the PRT-RTN instructions. For a Delaware resident, Column B should equal the total of lines 1 through 11 of the federal K-1. For a non-resident, it should equal the total of Column B (“Within Delaware”) from page 1, Schedule 1, lines 4 through 14 of the partnership return. For a resident partner that sentence and the form’s own Column B heading, which limits Column B to items derived from Delaware sources, point to different amounts: the full federal figures in one, the Delaware portion in the other. The instructions also do not say how a non-resident partner’s portion is carved out of the partnership’s Schedule 1 total; for a partnership doing business in Delaware and other states, Schedule 1 line 3 uses the apportionment percentage from Schedule 2, line 16, unless the partnership keeps separate accounting for its Delaware items. Formspedia does not choose between the two readings; the Division of Revenue can say which it expects before the forms go out (contacts at the end of this page).
When the partnership return is due and where it goes
The instructions say the partnership must prepare and give a PRT-PSI to each partner. They give no separate due date or mailing rule for the PRT-PSI itself; the dates that apply are those of Form PRT-RTN:
- PRT-RTN is due by the 15th day of the third month after the end of the taxable period, which is March 15 for a calendar-year partnership.
- Paper returns are mailed to the Delaware Division of Revenue, P.O. Box 8703, Wilmington, DE 19899-8703.
- A copy of the federal extension application submitted by that due date extends the Delaware return to the federal extended date; a photocopy of the approved federal extension must be attached to the return.
- A complete copy of federal Form 1065, with all schedules except the federal Schedule K-1, is attached to PRT-RTN.
Neither the instructions nor the forms page say whether copies of the PRT-PSI forms go to the Division with PRT-RTN. Ask the Division if you are unsure.
Penalties the PRT-RTN instructions name
- Not filing the partnership return, or not furnishing the information on it, costs $25 times the number of partners during any part of the year, for each month the failure continues, up to 5 months. A partnership with 8 partners that is two months late owes $25 × 8 × 2 = $400.
- Copying figures from the federal return does not protect against the penalties for a false or fraudulent return or a false certification.
- After a federal audit, or to change income, deductions or credits, the partnership files an amended return with a copy of the federal audit or the amended Form 1065 and its schedules.
Where to get Form PRT-PSI and who to ask
Download the 2025 Form PRT-PSI PDF from the Division of Revenue’s Business Tax Forms page, where it is listed under Partnership as “PRT-PSI Schedule K1 Partners Share of Income”, next to PRT-RTN, its instructions, PRT-EXT and PRT-VCH. The PRT-RTN instructions list three Division of Revenue offices: New Castle County, Carvel State Office Building, 820 North French Street, Wilmington, (302) 577-8200; Kent County, Dover, (302) 744-1085; Sussex County, Georgetown, (302) 856-5358; and the toll-free number 1-800-292-7826, which works only within Delaware. This page explains the form; it is not tax advice for a particular partnership.
Questions about Delaware Form PRT-PSI
Is PRT-PSI the same as the federal Schedule K-1?
PRT-PSI is a separate Delaware form. Its Column A repeats the federal Form 1065 Schedule K-1 amounts, and Column B adds the Delaware-source portion that the federal schedule does not show.
Does a partnership with no Delaware income need to issue PRT-PSI?
The PRT-RTN instructions say no return is required if the partnership has no Delaware-sourced income or loss, and PRT-PSI is prepared as part of that return.
Where does a non-resident partner use the PRT-PSI amounts?
On Form PIT-NON or a composite return. The Delaware-sourced partnership income goes in Column B of PIT-NON line 10, which covers rents, royalties, partnerships, S corporations, estates and trusts.
How do Delaware tax credits reach the partners?
Through line 16 of PRT-PSI. The partnership allocates the credits from its Form BUS-CRS among the partners, and each partner then completes its own BUS-CRS.
Official sources
- Delaware Division of Revenue, Form PRT-PSI, Schedule K-1 Partner’s Share of Income, 2025 (Revision 20250730)
- Delaware Division of Revenue, Partnership Return Instructions, Form PRT-RTN 2025 (revised 05/27/25)
- Delaware Division of Revenue, Form PRT-RTN, Partnership Return, 2025 (Revision 20251105)
- Delaware Division of Revenue, Form BUS-CRS, Delaware Income Tax Credit Schedule (Revision 20250528)
- Delaware Division of Revenue, Form PIT-NON Instructions, 2025
- Delaware Division of Revenue, Business Tax Forms 2025-2026
- Internal Revenue Service, Schedule K-1 (Form 1065), 2025