Form 7004 asks the IRS for an automatic extension of time to file one business income tax, information or other return: a partnership’s Form 1065, a corporation’s Form 1120 or 1120-S, an estate’s or trust’s Form 1041, Form 1042 or any other return on the form’s list. The extension is granted if the form is completed properly, the tax is estimated properly, the request reaches the IRS by the return’s due date, and any tax due is paid. It gives more time to file, never more time to pay. The current edition is Form 7004 (Rev. December 2025), with instructions of the same date.
Who files Form 7004, and who uses something else
Any entity filing one of the returns listed in Part I can use Form 7004. A few cases need a different route or no form at all:
- A trust filing Form 1041-A does not use Form 7004. The instructions send it to Form 8868; see our guide to Form 8868.
- Each return needs its own Form 7004. The IRS does not accept blanket requests, and the extension covers only the return named by the code on line 1.
- Members of a controlled or affiliated group that do not join in the consolidated return file their own Form 7004. Only the common parent or its agent can request an extension for the consolidated return.
- Certain foreign and domestic corporations and certain partnerships already have an automatic extension to file and pay under Regulations section 1.6081-5 and do not need Form 7004 for it (line 4 below).
Form codes for line 1
Line 1 holds a two-digit code that tells the IRS which return is being extended. The codes are not in order of form number (Form 708 is 37, Form 1120-C is 34) and the printed list has no codes 10, 13 or 14, so read the code off the printed table rather than guessing it. The notes column comes from the December 2025 instructions and from the due date chart on the IRS e-file page for Form 7004.
| Return being extended | Code | Notes |
|---|---|---|
| Form 706-GS(D) | 01 | Cannot be e-filed |
| Form 706-GS(T) | 02 | Always a calendar year; 6-month extension |
| Form 708 | 37 | Paper Form 7004 for tax year 2025 |
| Form 1041, bankruptcy estate only | 03 | 6 months |
| Form 1041, estate other than a bankruptcy estate | 04 | 5½ months |
| Form 1041, trust | 05 | 5½ months |
| Form 1041-N | 06 | 6 months |
| Form 1041-QFT | 07 | 6 months |
| Form 1042 | 08 | Always a calendar year; 6 months |
| Form 1065 | 09 | 6 months; see line 4 for partnerships with books abroad |
| Form 1066 | 11 | 6 months (general rule) |
| Form 1120 | 12 | 6 months; see the June 30 rule below |
| Form 1120-C | 34 | 6 months (general rule) |
| Form 1120-F | 15 | See lines 2 and 4 |
| Form 1120-FSC | 16 | 6 months (general rule) |
| Form 1120-H | 17 | An association electing Form 1120-H uses the code of the form type originally assigned to it |
| Form 1120-L | 18 | 6 months (general rule) |
| Form 1120-ND | 19 | 6 months (general rule) |
| Form 1120-ND (section 4951 taxes) | 20 | 6 months (general rule) |
| Form 1120-PC | 21 | 6 months (general rule) |
| Form 1120-POL | 22 | 6 months, whatever the year end |
| Form 1120-REIT | 23 | 6 months (general rule) |
| Form 1120-RIC | 24 | 6 months (general rule) |
| Form 1120-S | 25 | 6 months (general rule) |
| Form 1120-SF | 26 | 6 months (general rule) |
| Form 3520-A | 27 | 6 months (general rule) |
| Form 8612 | 28 | Cannot be e-filed |
| Form 8613 | 29 | Cannot be e-filed |
| Form 8725 | 30 | Cannot be e-filed |
| Form 8804 | 31 | 6 months (general rule); request due 5½ months after year end if records are kept outside the U.S. and Puerto Rico |
| Form 8831 | 32 | Cannot be e-filed |
| Form 8876 | 33 | Cannot be e-filed |
| Form 8924 | 35 | Paper Form 7004 for tax year 2025 |
| Form 8928 | 36 | Paper Form 7004 for tax year 2025 |
The general extension is 6 months. A C corporation with a tax year ending June 30 that began before January 1, 2026 gets 7 months (6 for Form 1120-POL); for tax years beginning in 2026 the instructions say 6 months. A short tax year ending at any time in June is treated as ending June 30. The extension for Form 706-GS(T) is always requested for a calendar year.
How to fill out Form 7004
The form is one page with a name and address block, Part I (line 1) and Part II (lines 2 to 8), which every filer completes. The numbers in the image match the line numbers below.
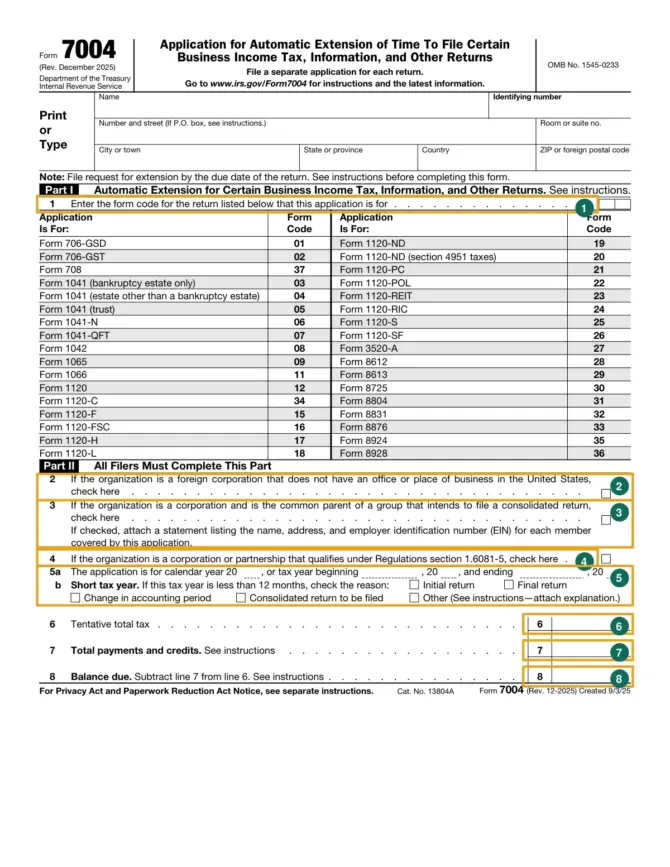
| Line | What to enter |
|---|---|
| Name and identifying number | The name exactly as on last year’s return, even if it has changed, and the EIN (or SSN). A name that does not match the IRS database or a wrong number means the extension is not valid. |
| Address | Street address with suite or room number; a P.O. box only if the post office does not deliver to the street. Foreign addresses: city, province or state, and the country name in full. |
| 1 | The two-digit form code from the table. |
| 2 | Check for a foreign corporation with no office or place of business in the United States. |
| 3 | Check if the corporation is the common parent of a group that will file a consolidated return, and attach the member list. |
| 4 | Check for an entity that qualifies under Regulations section 1.6081-5 and needs more time beyond its automatic extension. |
| 5a | Calendar year, or the beginning and ending dates of a fiscal year. |
| 5b | For a year shorter than 12 months, the reason: initial return, final return, change in accounting period, consolidated return to be filed, or other (attach an explanation). |
| 6 | Tentative total tax for the year, including any nonrefundable credits; enter -0- if you expect none. |
| 7 | Total payments and refundable credits. |
| 8 | Balance due: line 6 minus line 7. |
Two details on the top block. A new address written on Form 7004 does not change the IRS’s records; that takes Form 8822 or Form 8822-B. And Form 7004 needs no signature.
Line 3: the consolidated group member list
The attachment lists each member’s name, address and EIN. On a paper return the instructions set the layout: 8.5 x 11, 20 lb. white paper, 12-point Courier, Arial or Times New Roman, black ink, one-sided, margins of at least half an inch, two columns (names and addresses on the left, EINs on the right, half an inch apart) and two blank lines between affiliates. Leaving members off the list can cost the group its election to file a consolidated return. A member that must file a separate return for a short period files its own Form 7004 for that period.
Lines 2 and 4: entities with a different starting point
A foreign corporation with no office or place of business in the United States checks line 2 and files Form 7004 by the due date of its return, the 15th day of the 6th month after the tax year ends.
Line 4 covers entities that already have an automatic extension to file and pay until the 15th day of the 6th month after the year ends: partnerships that keep their books and records outside the United States and Puerto Rico, foreign corporations with a U.S. office or place of business, domestic corporations that do business and keep their books outside the United States and Puerto Rico, and domestic corporations whose principal income comes from U.S. territories. They attach a statement to the return saying they qualify. If they still cannot file by that date, Form 7004 with line 4 checked buys more time to file (not to pay): 3 months for partnerships and S corporations, 4 months for C corporations and Form 1120-POL filers.
Lines 6 to 8: the tax estimate and payment
Line 6 is not a placeholder: the extension depends on a proper estimate of the tax. Work it out with the instructions for the return being extended. A short example with our own figures: a calendar-year corporation expects $48,000 of total tax (line 6) and has made $40,000 of estimated payments (line 7), so line 8 is $8,000, payable by the return’s original due date. If the return later shows $50,000 of tax, the $48,000 on line 6 is at least 90% of it, so no late payment penalty applies as long as the remaining $2,000 is paid by the extended due date. Interest still runs on that $2,000 from the original due date.
Most entities must make federal tax deposits by electronic funds transfer, generally through EFTPS (EFTPS.gov, 800-555-4477), or through a tax professional, bank or payroll service that deposits for them. An e-filed Form 7004 can be paid by electronic funds withdrawal (see Form 8878-A). Other options are listed at IRS.gov/Pay. A corporation expecting a net operating loss carryback can reduce the deposit by the overpayment the carryback creates, provided all earlier tax liabilities are paid and Form 1138 is filed with Form 7004. Trusts filing Form 1041 and REMICs filing Form 1066 get the extension even if they cannot pay all of line 8, though they should pay as much as they can. For Form 1042, follow the deposit rules in its own instructions.
When Form 7004 is due
File it on or before the due date of the return being extended; each return’s instructions give that date. The IRS e-file page for Form 7004 links due date charts by tax period. For calendar year 2026 returns, the chart lists these due dates:
| Returns (calendar year 2026) | Return due date, and Form 7004 deadline |
|---|---|
| Forms 1065, 1066, 1120-S, 3520-A and 8804 | March 15, 2027 |
| Form 1042 | March 15, 2027 |
| Form 1120 and most of the 1120 series, Form 1120-POL | April 15, 2027 |
| Forms 1041, 1041-N and 1041-QFT | April 15, 2027 |
| Form 706-GS(T) | April 15, 2027 |
| Form 1120-C meeting IRC 6072(d) | September 15, 2027 |
| Form 1120 series, 1065 or 8804 with line 2 or 4 checked | June 15, 2027 |
The chart moves a due date falling on a weekend or federal holiday to the next business day. The IRS no longer sends a notice that an extension was approved; it writes only if the request is disallowed. It can also end an extension by mailing a notice of termination at least 10 days before the termination date.
One difference between the two IRS documents concerns June year ends. The December 2025 instructions give 7 months only to C corporations whose June 30 tax year began before January 1, 2026, and 6 months for tax years beginning in 2026. The chart on the e-file page still marks every June period, including June 2027, with its note on a 7-month extension. If your corporation has a June 2027 year end, confirm the length with the IRS business line, 800-829-4933 (7 a.m. to 7 p.m. local time).
How to file: e-file or the right IRS address
Form 7004 can be e-filed through the IRS Modernized e-File (MeF) platform for most returns. It cannot be e-filed for Forms 706-GS(D), 8612, 8613, 8725, 8831 and 8876. The IRS e-file page also lists requests that cannot go electronically, among them applications with a net operating loss carryback, applications with a Form 2848 attached, name change applications, refund requests, early filed returns and some change-in-accounting-period requests. On the carryback, the e-file page says Form 1138 should be sent separately and not with the 7004, while the instructions for line 8 speak of Form 1138 filed with Form 7004 on a paper request; the same business line, 800-829-4933, can confirm which applies to yours.
If you mail Form 7004 but e-file the return, the return may be processed before the extension is granted, and a penalty notice can follow. On paper, the address depends on the return and, for some returns, on where the principal business, office or agency is located:
- Eastern list: Connecticut, Delaware, District of Columbia, Georgia, Illinois, Indiana, Kentucky, Maine, Maryland, Massachusetts, Michigan, New Hampshire, New Jersey, New York, North Carolina, Ohio, Pennsylvania, Rhode Island, South Carolina, Tennessee, Vermont, Virginia, West Virginia, Wisconsin.
- Western list: Alabama, Alaska, Arizona, Arkansas, California, Colorado, Florida, Hawaii, Idaho, Iowa, Kansas, Louisiana, Minnesota, Mississippi, Missouri, Montana, Nebraska, Nevada, New Mexico, North Dakota, Oklahoma, Oregon, South Dakota, Texas, Utah, Washington, Wyoming.
| Return | Location | Mail Form 7004 to |
|---|---|---|
| 708, 706-GS(T), 706-GS(D) | Any settlor (resident or nonresident) | Department of the Treasury, Internal Revenue Service, Kansas City, MO 64999-0019 |
| 1041, 1120-H | Eastern list | Department of the Treasury, Internal Revenue Service, Kansas City, MO 64999-0019 |
| 1041, 1120-H | Western list | Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0045 |
| 1041, 1120-H | Foreign country or U.S. territory | Internal Revenue Service, P.O. Box 409101, Ogden, UT 84409 |
| 1041-QFT, 8725, 8831, 8876, 8924, 8928 | Any location | Department of the Treasury, Internal Revenue Service, Kansas City, MO 64999-0019 |
| 1042, 1120-F, 1120-FSC, 3520-A, 8804 | Any location | Internal Revenue Service, P.O. Box 409101, Ogden, UT 84409 |
| 1066, 1120-C, 1120-PC | United States | Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0045 |
| 1066, 1120-C, 1120-PC | Foreign country or U.S. territory | Internal Revenue Service, P.O. Box 409101, Ogden, UT 84409 |
| 1041-N, 1120-POL, 1120-L, 1120-ND, 1120-SF | Any location | Department of the Treasury, Internal Revenue Service, Ogden, UT 84409-0045 |
| 1065, 1120, 1120-REIT, 1120-RIC, 1120-S, 8612, 8613 | Eastern list, total assets at year end under $10 million | Department of the Treasury, Internal Revenue Service, Kansas City, MO 64999-0019 |
| 1065, 1120, 1120-REIT, 1120-RIC, 1120-S, 8612, 8613 | Eastern list, total assets $10 million or more | Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0045 |
| 1065, 1120, 1120-REIT, 1120-RIC, 1120-S, 8612, 8613 | Western list | Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0045 |
| 1065, 1120, 1120-L, 1120-ND, 1120-REIT, 1120-RIC, 1120-S, 1120-SF, 8612, 8613 | Foreign country or U.S. territory | Internal Revenue Service, P.O. Box 409101, Ogden, UT 84409 |
Two points where the sources do not line up exactly. Forms 1120-L, 1120-ND and 1120-SF appear both in the “any location” row (Ogden, UT 84409-0045) and in the foreign country or U.S. territory row (P.O. Box 409101); the instructions do not say which wins for a filer located abroad. And the instructions put Form 708 in the Kansas City row with Forms 706-GS(T) and 706-GS(D), while the IRS “Where to file Form 7004” web page, last updated August 27, 2026, lists only the two 706-GS forms in that row. The business line above can settle either question for your filing.
Official PDF: Form 7004 — Official PDF (irs.gov)
What changed in the December 2025 revision
- Forms 708, 8924 and 8928: for tax year 2025, use a paper Form 7004 to extend them. The instructions say electronic filing for them starts in tax year 2026.
- Electronic payments: the IRS recommends paying electronically whenever possible, with the options at IRS.gov/Pay and in the line 8 instructions.
Problems the IRS instructions warn about
- A name that does not match the IRS database, or a wrong EIN or SSN: the instructions say you will not have a valid extension.
- Filing after the return’s due date. The extension is granted only for a request filed by that date.
- Treating the extension as more time to pay. Unpaid tax draws a late payment penalty of ½ of 1% a month, up to 25%, unless there is reasonable cause, and interest from the regular due date even with an extension.
- One Form 7004 for several returns. Each return needs its own form.
- A paper Form 7004 followed by an e-filed return, which can be processed before the extension is granted and produce a penalty notice.
- Leaving consolidated group members off the line 3 list, which can cost the election to file a consolidated return.
- Using Form 7004 for Form 1041-A, which needs Form 8868.
If a penalty notice arrives after you file, the instructions say to send the IRS an explanation then; do not attach one to the return.
Questions about Form 7004
Will the IRS confirm that my Form 7004 extension was approved?
The IRS no longer sends approval notices. You will hear from it only if the extension is disallowed; a properly filed Form 7004 gives the maximum extension automatically.
Does Form 7004 also extend a state return?
Form 7004 is a federal request, so the answer comes from the state. Kentucky, for one, gives a corporation or pass-through entity the same extension when a copy of the federal Form 7004 is attached to the Kentucky return as it is filed; a Kentucky corporation can also file Form 720EXT.
Where do I get Form 7004?
The Form 7004 PDF and its instructions are on IRS.gov. The About Form 7004 page lists the December 2025 revision as the current one.
Sources
- Form 7004 (Rev. December 2025).
- Instructions for Form 7004 (Rev. December 2025).
- About Form 7004, IRS.
- Where to file Form 7004, IRS.
- E-filing Form 7004, IRS.
- Form 7004 due dates chart (PY2026), IRS.
- Let us help you (telephone assistance), IRS.
- 2025 Instructions for Kentucky Form 720, federal extension.