Nebraska Schedule II reduces federal taxable income on the corporation return in two separate computations. Lines 1 through 7 take foreign dividends out of the Nebraska base, and lines 8 through 12 give an adjustment for income that a foreign country taxed above the maximum federal corporate rate. The schedule sits on page 4 of the 2025 Form 1120N file, and both results flow through Nebraska Schedule A to line 4 of Form 1120N.
Which corporations use Schedule II
Schedule II belongs to Form 1120N, which every corporation engaged in business in Nebraska, or with Nebraska-source income, files if it is subject to federal corporation income tax. That includes cooperatives and exempt organizations that pay federal corporate tax on unrelated business income. The schedule matters when the federal return includes dividends from foreign corporations, Subpart F amounts treated as foreign dividends, an IRC § 78 gross-up, or income taxed abroad at a rate above the federal maximum.
S corporations file Form 1120-SN, and financial institutions file Form 1120NF. The 1120-SN package also has a “Schedule II”, but it is a different form: Nonresident Individual Shareholder’s Share of Nebraska Income. The foreign dividend computation described here is the Form 1120N schedule only.
Any corporation entering an amount on line 4 of Form 1120N must complete Schedule A. Schedule II is the worksheet behind two Schedule A lines: line 12 (total foreign dividends) and line 13 (special foreign tax credit adjustment).
How to fill out Schedule II, line by line
At the top, enter the name exactly as it appears on Form 1120N and the Nebraska ID number. All amounts are whole dollars; the pre-printed zeros in the cents column stay as they are, and 50 cents or more rounds up.
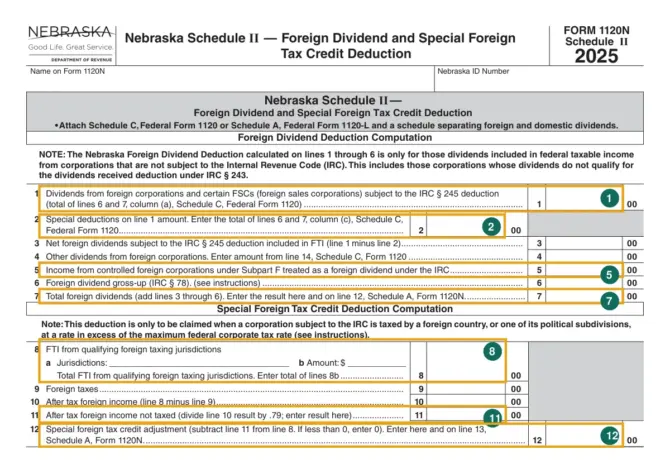
| Line | What goes on it | Where the figure comes from |
|---|---|---|
| 1 | Dividends from foreign corporations and certain FSCs subject to the IRC § 245 deduction | Federal Form 1120, Schedule C, lines 6 and 7, column (a); life insurers use Form 1120-L, Schedule A, lines 6 and 7, column (a) |
| 2 | Special deductions on the line 1 amount | The same lines 6 and 7, column (c) |
| 3 | Net § 245 dividends included in federal taxable income | Line 1 minus line 2 |
| 4 | Other dividends from foreign corporations | Form 1120, Schedule C, line 14, or Form 1120-L, Schedule A, line 15 |
| 5 | Subpart F income from controlled foreign corporations that the IRC treats as a foreign dividend | Foreign dividends on Form 1120, Schedule C, including line 16b; line 16c only with documents showing the dividend portion |
| 6 | Foreign dividend gross-up under IRC § 78 | Schedule C, line 18, less the § 78 amount included in the GILTI deduction |
| 7 | Total foreign dividends | Lines 3 through 6; also entered on Schedule A, line 12 |
| 8 | Federal taxable income from qualifying foreign taxing jurisdictions | List each jurisdiction on 8a with its amount on 8b; line 8 is the total of the 8b amounts |
| 9 | Foreign taxes paid on the line 8 income for which the foreign tax credit is taken | The federal foreign tax credit computation |
| 10 | After-tax foreign income | Line 8 minus line 9 |
| 11 | After-tax foreign income not taxed | Line 10 divided by .79 |
| 12 | Special foreign tax credit adjustment | Line 8 minus line 11, never below zero or above line 8; also entered on Schedule A, line 13 |
Lines 1 through 7: the foreign dividend deduction
The note printed above line 1 limits this part to dividends included in federal taxable income from corporations not subject to the Internal Revenue Code, which includes corporations whose dividends do not qualify for the dividends received deduction under IRC § 243. Line 2 removes the federal special deduction already taken on the line 1 dividends, so only the net amount still in federal taxable income reaches line 3.
On line 4, a U.S. life insurance company that claims a deduction for “Other corporate dividends” from line 19, Schedule A, Form 1120-L must include a detailed description of those dividends.
Line 5 accepts Subpart F inclusion income only when it is a foreign dividend or deemed foreign dividend under the IRC. Amounts from Schedule C, line 16b are supported by a copy of federal Schedule C. Line 16c is different: the instructions say most of those inclusions are not foreign dividends, and Schedule C, Form 5471 and Schedule I of Form 5471 do not identify any part of line 16c as a dividend. To deduct part of line 16c, attach those forms and a worksheet or other document that identifies the foreign dividend amount. The booklet refers to Revenue Ruling 24-21-1 for Nebraska’s treatment of Subpart F income.
Line 6 starts from the § 78 gross-up on Schedule C, line 18 and subtracts the part of that gross-up included in the GILTI deduction. Support it with Schedule C, Form 8993 and Forms 1118.
Lines 8 through 12: the special foreign tax credit deduction
This part applies only when income of a corporation subject to the IRC is taxed by a foreign country, or one of its political subdivisions, at a rate above the maximum federal corporate rate. The adjustment can be made country by country or for a group of countries. Line 8 takes federal taxable income from those jurisdictions, and line 9 takes the foreign taxes paid on that income which are not deductible because the corporation elected the foreign tax credit on its federal return.
Line 11 divides the after-tax income on line 10 by .79, the form’s figure for one minus the maximum federal corporate rate. Line 12 is the difference between line 8 and line 11. Attach a schedule showing federal taxable income and foreign taxes paid by country.
A worked example with invented figures: a corporation has $400,000 of federal taxable income from one qualifying country and paid $140,000 of foreign tax on it. Line 10 is $260,000. Divided by .79, line 11 is $329,114 after rounding to whole dollars. Line 12 is $400,000 minus $329,114, or $70,886, which goes to Schedule A, line 13. If line 11 were larger than line 8, line 12 would be zero.
Attachments to send with Schedule II
The schedule header and the booklet instructions list the supporting documents in two places. The header asks for one of the federal dividend schedules and a split of foreign and domestic dividends; the instructions add Parts A and B of Form 1118.
- Schedule C of federal Form 1120, or Schedule A of federal Form 1120-L for life insurers
- A schedule separating foreign and domestic dividends
- Parts A and B of federal Form 1118
- For line 5 amounts from Schedule C, line 16c: Forms 5471, Schedules I of Form 5471 and a document identifying the foreign dividend portion
- For line 6: Form 8993 and Forms 1118 with Schedule C
- For line 8: a schedule of federal taxable income and foreign taxes paid, by country
Where to get the form and when it is filed
Schedule II is printed on page 4 of the 2025 Form 1120N with Schedules A, I and II, and its instructions are in the 2025 Nebraska Corporation Income Tax Booklet. There is no separate Schedule II file on the Department of Revenue forms page. Use the 2025 form for calendar year 2025 or a fiscal year beginning in 2025.
Schedule II has no signature or payment line of its own. It is filed with Form 1120N, which is due on or before the date the related federal income tax return is due. A federal extension on Form 7004 gives an automatic Nebraska extension for the same number of months; Form 7004N covers a tentative payment or a Nebraska-only extension. An extension does not move the payment date, and the total cannot exceed seven months after the original due date.
Returns can go through the Federal/State e-file program. Paper returns go to Nebraska Department of Revenue, PO Box 94818, Lincoln, NE 68509-4818, with a copy of the federal return and supporting schedules as filed with the IRS. A corporate officer signs Form 1120N; another person can sign only with a power of attorney on file or attached, which is Nebraska Form 33.
Changes in the 2025 booklet
The What’s New section of the 2025 Corporation Income Tax Booklet does not mention Schedule II. Its first item is the corporate tax rate on Nebraska taxable income, reduced to 5.20% for the 2025 taxable year under LB 754 (2023). The other items cover credits, the foreign adversarial company rule and the gold and silver bullion adjustment.
Questions about Nebraska Schedule II
Where do the Schedule II results go on Form 1120N?
Line 7 goes to Schedule A, line 12 and line 12 goes to Schedule A, line 13. Schedule A, line 21 totals the decreasing adjustments and is entered on line 4 of Form 1120N.
Can an S corporation use this Schedule II?
S corporations file Form 1120-SN, whose Schedule II computes a nonresident individual shareholder’s share of Nebraska income. The foreign dividend and special foreign tax credit computation is part of Form 1120N.
Is there a separate Schedule II PDF?
The Department posts Schedule II inside the Form 1120N file (page 4) and the corporation booklet. The forms page lists that file as Form 1120N with Schedules A, I and II.